ICL Heads Into Q3 With Bromine Cooling And Sulfur Biting, Testing Its High-End Outlook
ICL Group spent the first half of 2026 proving that its specialty minerals engine could run hot. The third-quarter report, due before the market opens on November 11, asks a harder question: how much of that heat survives once bromine prices cool, sulfur costs flow through phosphate inventory, and Brazil fails to deliver its usual seasonal lift? Management already signaled that the back half would land a bit below the first. The market appears to have taken that warning more seriously than the company did.
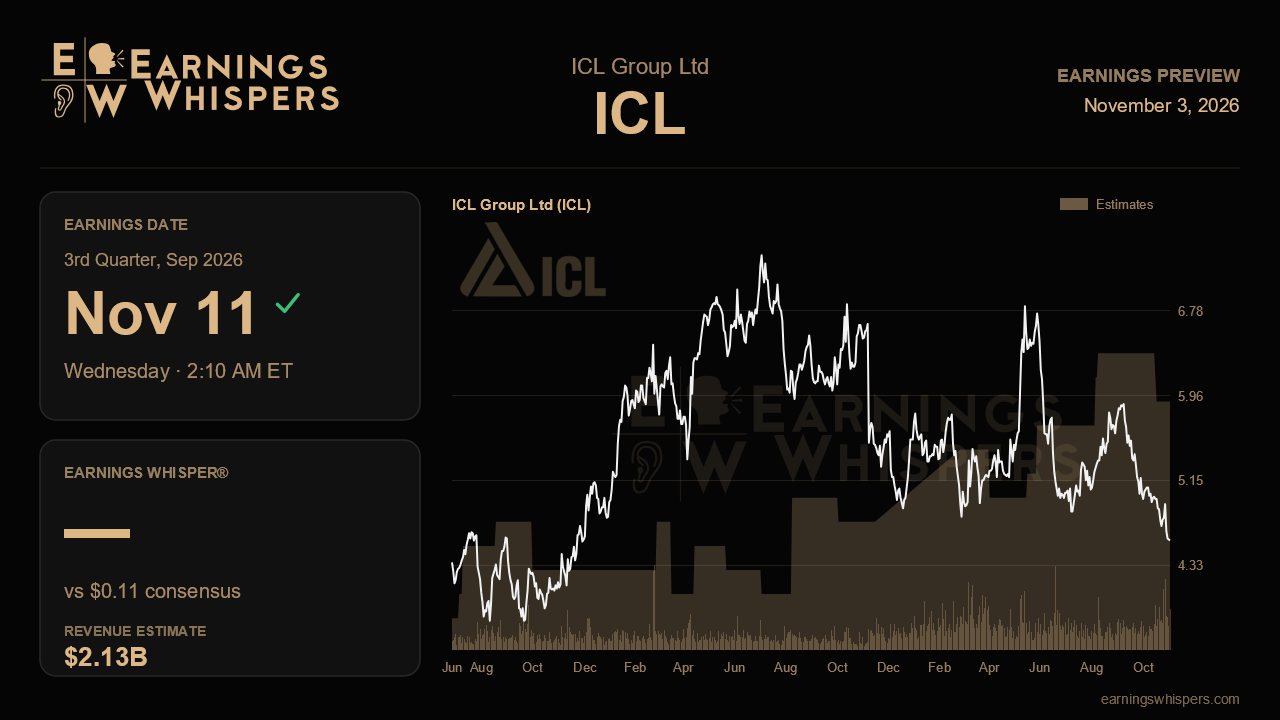
Wall Street expects earnings of $0.11 per share on revenue of roughly $2.13 billion. That would be about 10% EPS growth from $0.10 a year ago and a 15% jump in sales from $1.85 billion, which is solid growth by any measure. Sequentially, though, the picture is flat to slightly down, with revenue essentially matching the $2.14 billion of the prior quarter and EPS easing from $0.12. In other words, the Street has already modeled the softer second half management described. The more important comparison is against the company's full-year EBITDA outlook of $1.5 billion to $1.7 billion, which was raised by $100 million early in the year and reaffirmed last quarter with management pointing toward the upper end. With trailing EBITDA running near $1.65 billion, a third quarter that comes in light would quickly put that high-end positioning in doubt.
Industrial Products is the segment that carries the most weight. Its EBITDA surged 88% to $130 million last quarter, the best result since late 2022, on bromine prices that peaked near $6,000 per ton in April. By the time of the call, prices had slipped to around $4,500. That is still a healthy level, but it means the segment is unlikely to repeat its peak contribution. What would validate the bull case is evidence that Industrial Products holds most of its gains even at lower pricing, suggesting that volume and mix, not just a geopolitical price spike, drove the improvement. Potash is the other bright spot to monitor, after average prices climbed for three straight quarters to $376 per ton CIF alongside production up roughly 11%.
The pressure points are just as clear. Sulfur spot prices more than tripled year over year to around $1,200 per ton, and management explicitly guided to phosphate margin compression as costlier inventory works through the system. Phosphate EBITDA of $136 million barely grew last quarter, so any meaningful decline here would confirm the squeeze is arriving on schedule or worse. Growing Solutions, which already slipped below year-ago EBITDA, faces a seasonally important quarter in Brazil that management said is unlikely to be strong, given affordability problems and steep real interest rates. Add shekel strength, which cost about $40 million last quarter, plus elevated freight and raw material bills, and there are several ways for margins to disappoint even if revenue lands on target.
Investors also deserve early detail on the Elevate cost program, which targets more than $150 million of EBITDA benefit by end of 2027 and more than $350 million by end of 2028. The CEO hinted internal targets are even more ambitious. This quarter will not show much of that in the numbers, but concrete milestones would help bridge the gap between today's commodity headwinds and the longer-term story.
The setup is unusual. Sentiment has swung sharply to 82.8% bullish from a mildly bearish reading before the last report, yet the shares have fallen 13.3% since then, trailing the S&P 500 by about 10 points. At $4.57, the stock sits below its 200-day moving average of $5.39 and right at the bottom of its post-earnings range, just above the $4.54 low. That suggests the price already reflects considerable skepticism about the second half. The verdict will hinge on whether reaffirmed guidance near the top of the range survives this quarter. If ICL can show that bromine and potash offset sulfur and Brazil well enough to keep the high end intact, the narrative of improving momentum holds. If guidance slides toward the midpoint, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-21 | |
| Aug-18 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Jul-21 | |
| Jun-16 | |
| Jun-09 | |
| Jun-01 | |
| May-13 | |
| May-13 | |
| May-13 | |
| Apr-22 | |
| Mar-18 |
