ICL Misses On Sales And EPS As Growth Stalls, While Bromine Strength And A Guidance Lean Keep A 2027 Story Alive
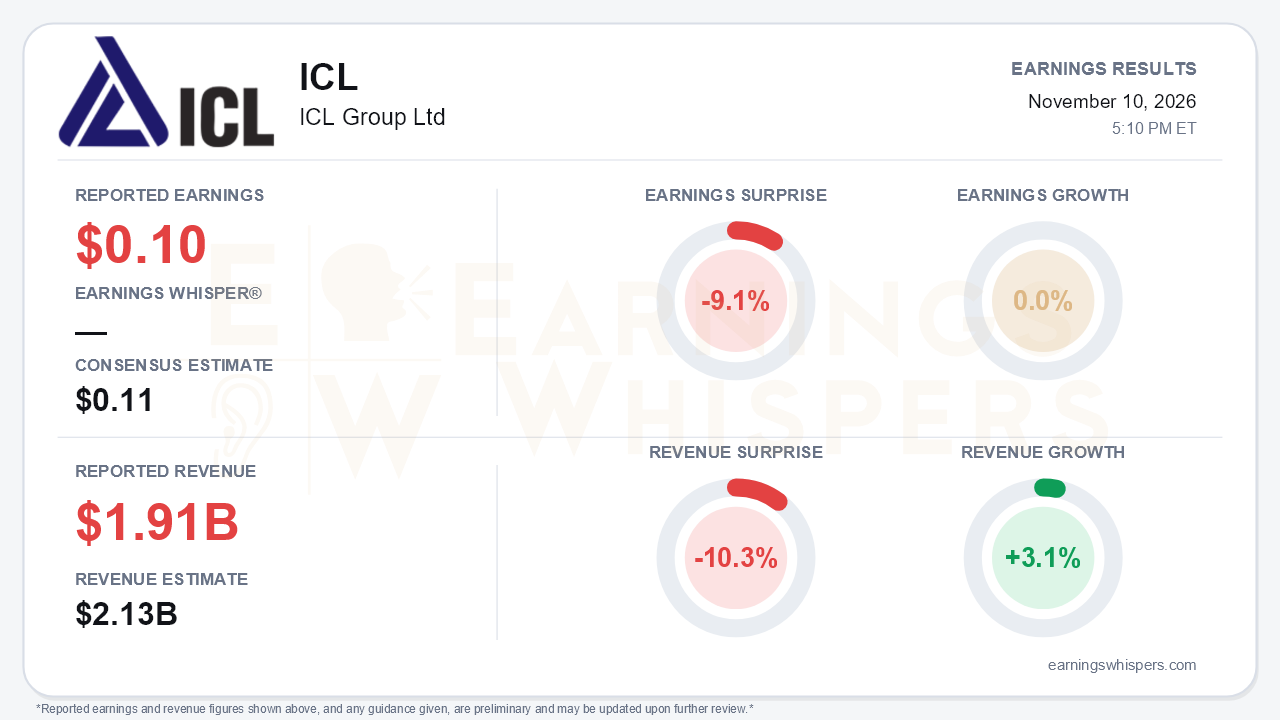
ICL Group's third quarter marked the point where its 2026 growth story ran out of momentum. Adjusted EPS of $0.10 missed the $0.11 consensus by 9.1% and was flat year over year. Revenue of $1.91 billion rose 3.1% but fell 10.3% short of the $2.13 billion consensus, a large miss for a diversified minerals company. The bigger problem is the trajectory. Sales growth slowed from +14% in the first quarter and +17% in the second to just +3%. Adjusted EBITDA growth went from +15% and +28% to +1% ($402 million). The central tension is that management still leaned its full-year guidance toward the upper half, even as nearly every segment outside Industrial Products weakened.
The quality of the quarter is mixed. Management highlighted a 32.9% gross margin, up 30 basis points and the best since the fourth quarter of 2024. That improvement did not reach the bottom line:
- Selling, transport and marketing expenses rose $23 million, and bulk freight rates were up 24% year over year.
- Adjusted operating margin fell to 12.2% from 13.0%.
- Adjusted EBITDA margin slipped to 21.0% from 21.5%.
GAAP net income attributable to shareholders rose to $120 million from $115 million, but diluted EPS held at $0.09. Pricing did the heavy lifting: a $171 million price/mix benefit offset a $134 million volume drag. Cash generation was the weakest link. Operating cash flow fell to $256 million from $308 million, and free cash flow was only $66 million after a $242 million inventory build tied to soft commodity phosphate demand. Net financial liabilities have risen $366 million since year-end to $2.63 billion.
Beneath the consolidated figures, the business split sharply.
- **Industrial Products** was the clear winner. Sales rose 18% to $347 million and EBITDA jumped 49% to $100 million on higher bromine prices, electronics demand and strong clear brine fluid volumes.
- **Potash** EBITDA fell about 7% to $157 million on energy, logistics and currency costs. The $370 per ton price was up 4.8% year over year but down roughly 2% sequentially.
- **Phosphate Solutions** EBITDA dropped to $118 million from $134 million. Sales fell to $589 million from $722 million in the second quarter as management curtailed fertilizer output through advanced maintenance and extended holiday breaks.
- **Growing Solutions** EBITDA slid to $44 million, hurt by a weak Brazil high season in which customers delayed purchases and traded down.
The sources conflict on one growth engine. The release cited a solid increase in food phosphate sales, while call commentary indicated specialty food phosphate sales declined in the quarter. That discrepancy deserves scrutiny.
Guidance is where the narrative gets more constructive and more demanding. ICL reiterated 2026 adjusted EBITDA of $1.5 billion to $1.7 billion and potash volumes of 4.5 to 4.7 million tons, and said it is now targeting ahead of the midpoint. With $1.262 billion of adjusted EBITDA through nine months, that implies a fourth quarter of roughly $340 million or more. Management also warned that fourth-quarter results will carry higher sulfur costs because of inventory lag and will be lower than first-half levels. Two factors support the near-term outlook:
- Bromine spot prices rebounded in October to first-quarter levels.
- A strong Industrial Products quarter is the swing factor.
The 2027 case rests on several catalysts:
- Sulfur prices have fallen since their August peak, which management expects to help results from the first quarter of 2027.
- Management reiterated the ELEVATE target of more than $150 million in 2027 savings with "high confidence."
- Management expects phosphate fertilizer demand to recover after farmers skipped 2026 on affordability.
- Management says Chinese potash restocking supports expected strong 2027 potash demand.
- A new segment structure takes effect in January.
Those are management expectations, not results, and bears have legitimate ammunition in the volume declines and rising leverage.
Investors were already leaning skeptical, and the skepticism deepened. Earnings Whispers sentiment moved from roughly neutral at -0.08 to -0.23, a meaningful shift into negative territory. The stock has fallen 11.4% since opening at $5.27 after the August report. At $4.67, it sits about 13% below its 200-day moving average of $5.37. Price and AVWAP trend readings remain negative, consistent with a market that had been discounting a slowdown before this report confirmed it.
The bottom line is that ICL's third quarter exposed how dependent the company has become on pricing and on a single standout segment. Revenue and EPS missed, consolidated growth nearly stalled, and cash flow weakened. Industrial Products, falling sulfur costs and committed ELEVATE savings give management a credible path toward a better 2027. In the near term, delivering a fourth quarter strong enough to land ahead of the guidance midpoint is the test that matters most.
Read our earnings preview for ICL Group Ltd: https://www.earningswhispers.com/article/ICL/22808
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Oct-21 | |
| Aug-18 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Jul-21 | |
| Jun-16 | |
| Jun-09 | |
| Jun-01 | |
| May-13 |
