Ryman Hospitality Beats And Raises Again As Group Pace Strengthens, But Entertainment And Booking Rates Need Watching
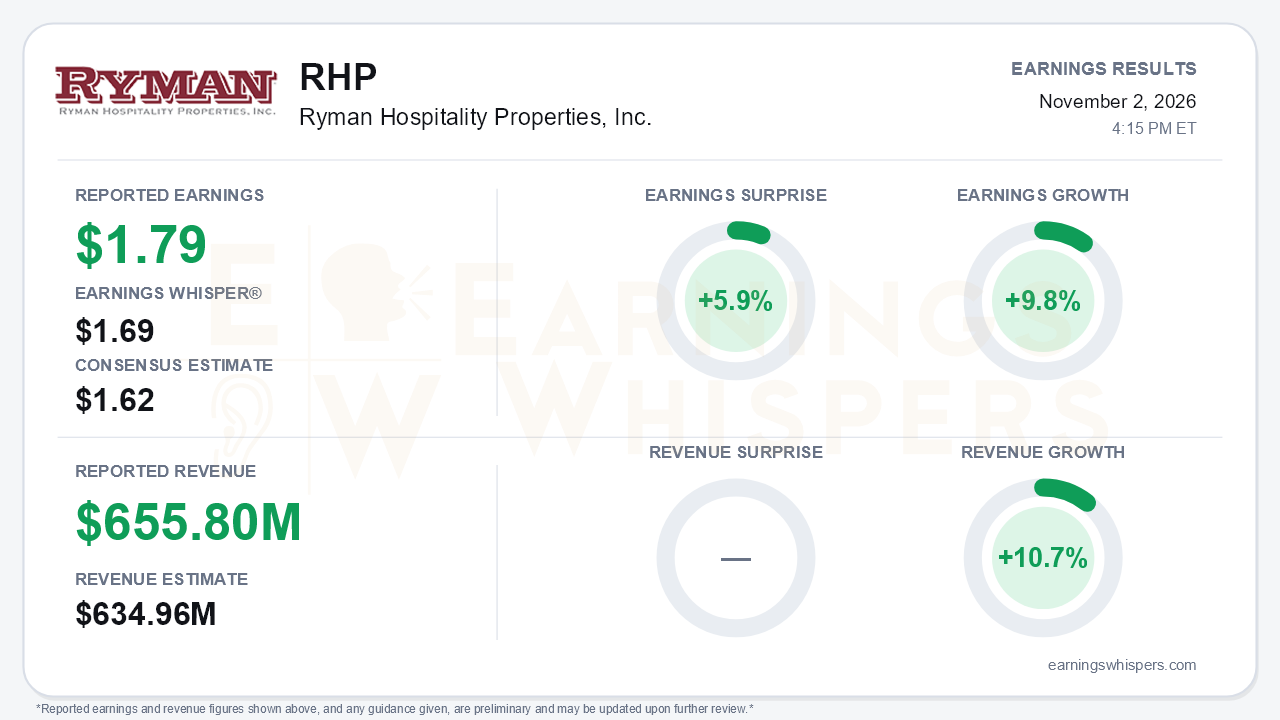
Ryman Hospitality Properties delivered a third consecutive beat-and-raise. Third-quarter adjusted FFO of $1.79 per share topped the $1.62 consensus and the $1.69 Earnings Whisper number. The 5.9% surprise came with 9.8% year-over-year earnings growth. Revenue of $655.8 million rose 10.7% and beat the $634.96 million consensus by 3.3%. The more important development lies beneath the headline. Same-store group pace for 2027 and 2028 improved meaningfully, and that gives the growth story more runway than one strong quarter could. The tension is that hospitality strength coexists with a softening Entertainment segment, flat booking rates, and a heavier balance sheet. Investors appear to have noticed.
The quality of the hotel beat is solid. Same-store RevPAR rose 7.9% and Total RevPAR rose 8.0%, each about 400 basis points above plan according to the call, a wider beat than the roughly 250 basis points delivered in the second quarter. Occupancy climbed 3.0 points to 70.3%. Same-store Adjusted EBITDAre grew 12% to $169.5 million, with margin up 120 basis points to 33.8%.
The gains did not depend on penalty income. Attrition and cancellation fees actually fell $2.8 million, to $8.8 million. Banquet and AV contribution per group room night rose 9.7%, extending the premium-group spending story. Gaylord Opryland led with a 15.5% RevPAR gain, and Gaylord Rockies expanded its EBITDAre margin by 3.8 points. The weak spot was JW Marriott Hill Country, which is under renovation; its RevPAR fell 4.4% and EBITDAre dropped 9.8%.
The headline growth rate also deserves context. Third-quarter AFFO-per-share growth of 9.8% trailed the 12.9% nine-month pace, and revenue growth of 10.7% trailed the 12.5% year-to-date rate. Part of that is dilution: about 5.9 million shares were issued in August at $117 to help fund Grande Lakes Orlando. Per-share growth is now working against a larger share count.
The call shifted the forward narrative in management's favor.
- **2027 pace:** Same-store group rooms revenue pace improved to +4.5%, from +3.2% in the second quarter and roughly +3% in the first.
- **2028 pace:** Pace turned positive at +1%, from -1% earlier in the year. That lends credibility to the strategy of shifting inventory into later years.
- **Mix:** Corporate mix on the 2027 books is about 300 basis points higher, and net definite room nights booked rose 9%.
- **Tone:** Management spoke of the "best times ahead," a notable shift from the "storm clouds" caution voiced earlier in the year.
Guidance followed suit. The same-store RevPAR growth midpoint rose to 5% from 4%. The AFFO-per-share midpoint moved to $9.29 from $9.08, roughly 10% growth, and GAAP EPS guidance rose to $4.08 from $3.93.
Bears still have legitimate ammunition. Production ADR on new bookings was $293, roughly flat year over year and well below the second quarter's record $310. Gross definite room nights fell 2.1% to about 654,000, compared with 768,000 in the prior quarter. Management attributes the softer rate to filling back-half booking patterns, but it bears watching.
Entertainment is the clearer drag:
- Segment revenue grew only 1.5%.
- Adjusted EBITDAre slipped 3.7%.
- GAAP operating income fell 40.9%, burdened by a $4.9 million impairment.
- Retiring the General Jackson Showboat cut the segment's EBITDAre guidance midpoint by $3 million to $122 million.
On the balance sheet, the Grande Lakes financing combined new equity with $700 million of 6.25% notes, lifting pro forma leverage to 4.4x from 4.2x. Integration also carries risk, because Ritz-Carlton margins run materially below Gaylord levels. The OEG strategic transaction remains unresolved.
There are offsetting catalysts:
- Category 10 Las Vegas opened ahead of expectations.
- The Gaylord Texan rooms renovation is complete.
- The Opryland meeting-space expansion arrives in mid-2027.
- Management expects less renovation disruption in 2027 than in 2026.
- Marriott procurement and fee-relief opportunities are slated for quantification in February.
The market setup is more complicated than the surprise implies. Shares have gained 8.3% since opening at $124.52 after the August report. At $134.90, they sit 18.8% above the 200-day moving average and comfortably above the $117 offering price. Momentum and AVWAP trend readings are positive.
Yet Earnings Whispers investor sentiment cooled from 0.38 to 0.26. That is a meaningful step down, although sentiment remains positive. The stock has already rewarded the hotel momentum, and investors may be weighing dilution, leverage, and the Entertainment softness more heavily than the raised guidance.
The bottom line is that Ryman's core convention-resort engine is running ahead of plan, and the improving 2027–2028 group pace gives the call a credible growth story beyond this year. The beat is real and broad-based in hospitality. Investors should keep watching three things: booking-rate momentum, Entertainment execution, and Grande Lakes integration, given a stock that already trades well above its long-term trend and a sentiment backdrop that has grown more cautious.
Read our earnings preview for Ryman Hospitality Properties, Inc.: https://www.earningswhispers.com/article/RHP/21426
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Oct-16 | |
| Sep-15 | |
| Sep-11 | |
| Sep-08 | |
| Sep-01 | |
| Aug-25 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 |
