Agi Must Show Its Spending Spree Is Paying Off As AgiPlus Fees Arrive
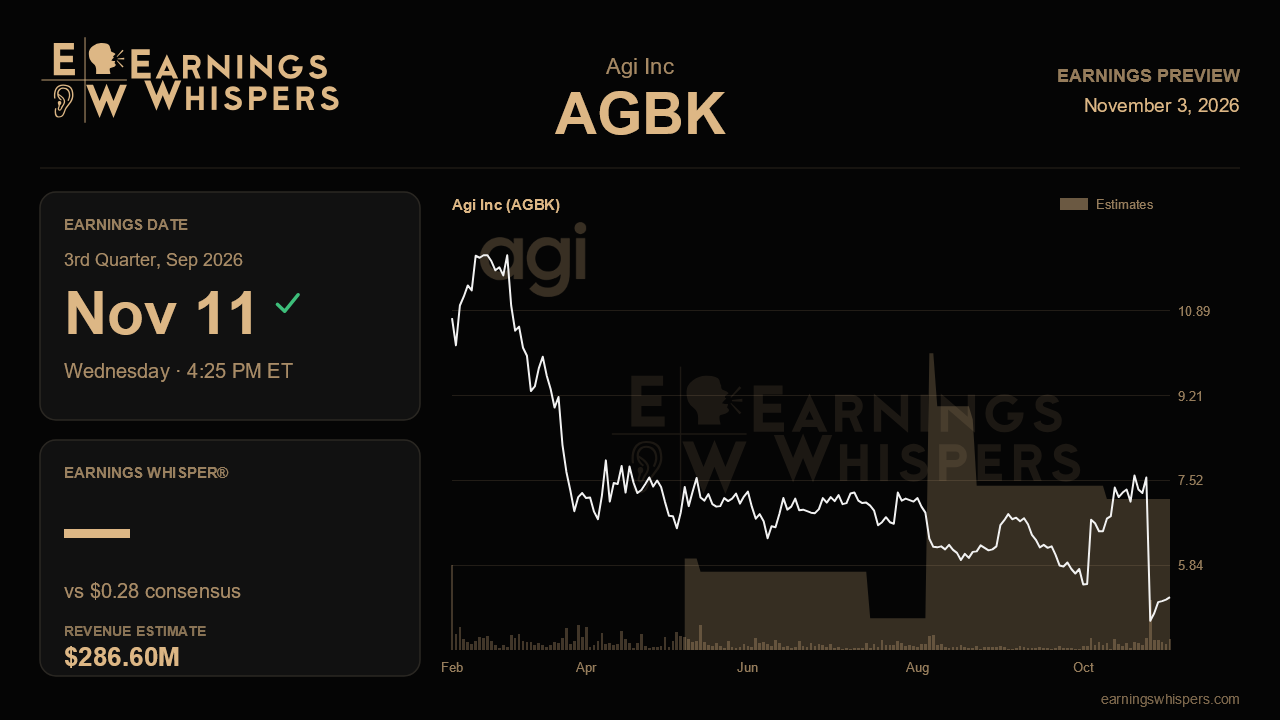
Agi heads into its September-quarter report with a straightforward problem: management spent last quarter telling investors the business had hit a positive inflection, and the market responded by selling the stock hard. The Brazilian lender delivered record revenue, more customers and rising payroll-loan market share, but pre-tax profit nearly halved from the prior quarter as costs ran ahead of revenue. This report is the first real chance to see whether that air pocket was a deliberate investment phase or the start of something less forgiving.
The Street is asking for earnings of $0.28 a share, matching the prior quarter, on revenue of roughly $286.6 million. A flat per-share figure sounds undemanding, but the composition matters more than the headline. Last quarter's bottom line was propped up by an unusually negative effective tax rate that supplied close to half of earnings, and management acknowledged that rate should drift higher. Holding EPS steady while the tax benefit fades would therefore require a meaningful rebound in pre-tax profit. Hitting $0.28 on another tax windfall would be a far weaker result than hitting it on operating improvement. The company does not issue formal guidance, so the earnings bar is set by consensus and by the recovery story management has been telling.
That story rests on a few specific claims. The biggest is AgiPlus, the subscription program launched last quarter that signed more than 250,000 members in about 45 days, attached to roughly two-thirds of new credit originations, and was described as carrying contribution margins near 80%. Management targeted around one million subscribers by year-end and said fee revenue would begin flowing this quarter. Evidence that subscriber growth is tracking toward that goal, and that fees are showing up in the income statement, would go a long way toward validating the idea that last quarter's expenses were seeds rather than leakage. The efficiency ratio, which jumped to 48.9% from 43.2%, is the cleanest scorecard: improvement would suggest revenue is catching up to the cost base, while further deterioration would challenge the inflection narrative directly.
Margins are the second test. Net interest margin after provisions slipped 50 basis points to 6.8%, squeezed by a SELIC rate running hotter than expected and by a smaller share of higher-yielding personal loans. Unsecured lending has been flat for consecutive quarters, so any pickup there would help the mix-driven margin recovery management is counting on. Private payroll, meanwhile, has been the growth engine, reaching about R$200 million a month in originations. The tradeoff is credit cost, already near 6%, because the product carries structurally higher delinquencies. Last quarter's 90-day NPL ratio improved to 3.3% and coverage was rebuilt to 182%. Holding those gains while payroll lending scales would ease concerns that growth is being bought with future losses. Watch, too, whether the falling share of retail funding, down to 38% from 45%, keeps sliding despite the recent Moody's and Fitch upgrades to AA.
The market has clearly voted with skepticism. Shares have fallen about 16% since the last report, trailing the S&P 500 by nearly 14 percentage points, and at $5.20 they sit well below the 200-day moving average of $7.39 and in the lower part of a post-earnings range stretching from $4.43 to $7.87. Sentiment remains bearish, though somewhat less so than heading into the prior report, which hints that some of the pessimism may already be priced in.
Ultimately, this quarter comes down to whether pre-tax profit recovers. If AgiPlus fees, operating leverage and stable credit allow earnings to hold up without help from the tax line, management's case for a full recovery in 2027 gains real credibility. If profit stays depressed and the tax benefit fades, the stock's slide will look less like an overreaction and more like an early warning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-01 | |
| Sep-23 | |
| Aug-20 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 | |
| Jul-22 | |
| Jun-18 |
