Agi Rebounds From A Weak Q2 With An Origination-Led Beat, But Thinning Credit Buffers Temper The Recovery
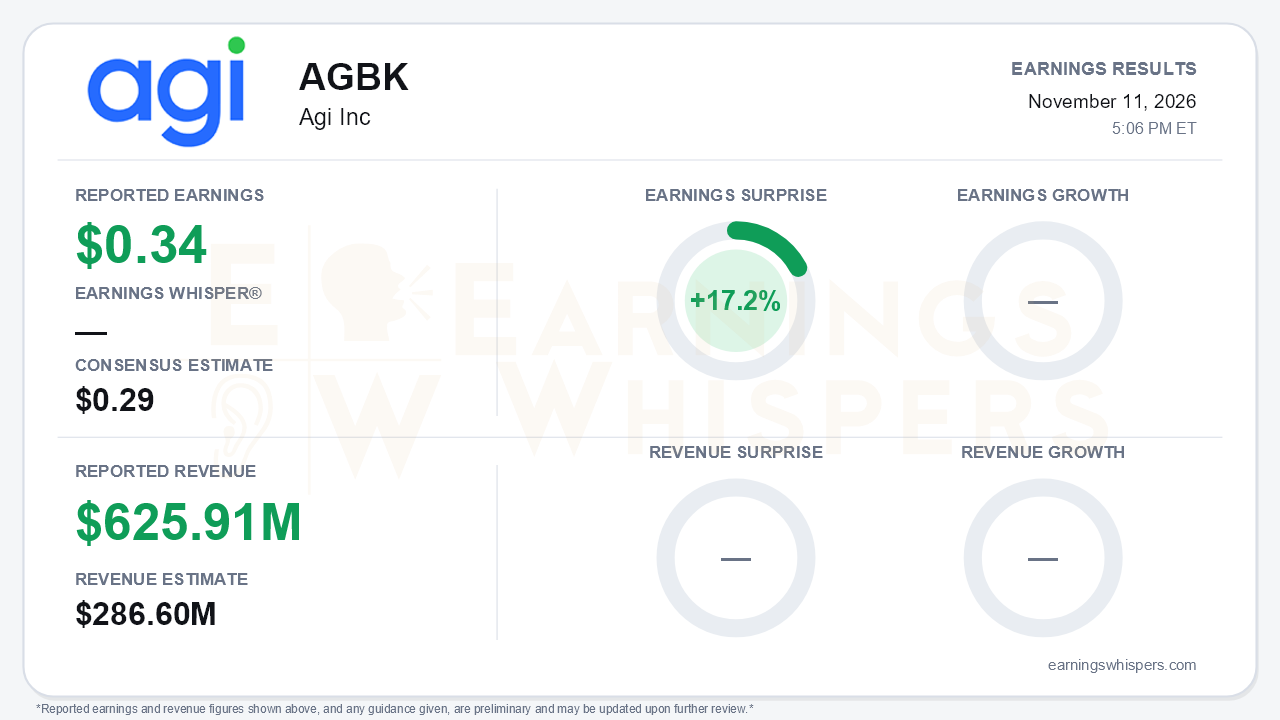
Agi Inc (NYSE: AGBK) delivered the rebound management had promised after a disappointing second quarter. The bank earned $0.34 per share for the quarter ended September 2026, beating the $0.29 consensus by 17.2%. Revenue of $625.91 million topped the $286.6 million consensus by 118.4%. A revenue surprise of that size says less about the business than the operating detail beneath it, and that detail tells a two-sided story. Origination, fees, and profitability turned sharply higher, while the cushions that protect those earnings (provisions coverage, risk-adjusted margin, and capital) all thinned. That is the central tension of the quarter.
The headline growth is real. Gross credit origination reached R$10.2 billion, up 42.5% sequentially and 76.5% year over year, the strongest pace in over a year. Fee revenues jumped 80.1% quarter over quarter to R$244.1 million, an acceleration from roughly 35% sequential fee growth in Q2. Earnings before taxes rose 62.8% to R$187.2 million, reversing a pre-tax decline of roughly 47% in Q2 that had missed expectations. Annualized ROE climbed to 22.4% from 16.9%, and the efficiency ratio improved 470 basis points to 44.2%.
The quality of the beat still deserves scrutiny. Net income of R$276.0 million exceeded pre-tax earnings, which means tax effects lifted the bottom line. Net interest income rose only about 1% sequentially, so the earnings recovery leaned on fees, operating leverage, and below-the-line items rather than on spread expansion.
The call showed a business gaining share in its core franchise. INSS payroll market share reached 10.0%, the company's first double-digit share, extending a steady climb from 8.9% in Q4, 9.0% in Q1, and 9.6% in Q2. The private payroll book grew to R$2.3 billion from R$1.4 billion in Q2 and R$1.0 billion in Q1. Management also lifted its monthly origination appetite in that product to R$250-300 million from about R$200 million. Active customers rose to 8.3 million from 7.6 million last quarter. Agi+ subscriptions topped 700,000, up from 250,000 at Q2, and contributed revenue for the first time. The unsecured book stabilized and grew for the first time this year, and management pointed to a minimum wage increase as a Q1 2027 tailwind. Management's tone shifted noticeably, from Q2's language of a 'transitory' setback and 'recovery' to describing the business as 'fully normalized.' Management said fees should grow from the Q3 level and that the NIM trend should improve in Q4. No formal guidance was provided.
Bears have legitimate ammunition on the credit side:
- NPLs over 90 days rose to 3.5% from 3.3%, and cost of risk increased to 6.1%.
- Coverage dropped sharply to 157% from roughly 182%.
- NIM after provisions compressed for a second straight quarter, to 6.3% from 6.8% in Q2 and 7.3% in Q1, while headline NIM slipped to 11.8%.
- Year-over-year loan growth decelerated to 12% from 21% in Q2 and 30% in Q1, even as origination surged.
- The capital adequacy ratio fell 60 basis points to 18.1% just as a buyback of up to three million Class A shares begins.
Management also cautioned that Q4 INSS growth should normalize, because September was partly boosted by the expiry of a provisional measure. Executives flagged rising funding costs and a tougher Brazilian macro backdrop as additional headwinds. Some positives offset these concerns: the S&P upgrade to AA leaves all three agencies at that level, and the hire of an AI platformization leader signals continued investment. Still, the Agi+ trajectory has yet to show it can reach the roughly 1 million year-end subscriber aim discussed in Q2.
The market setup is more complicated than the surprise implies. Investor sentiment entering the period was deeply negative at -0.60 following the Q2 report. The stock was highly volatile between reports. Shares opened at $6.21 after the August release and rallied to a quarter high of $7.87 on October 20, above the $7.30 200-day moving average. They then collapsed to a 52-week low of $4.43 just six days later, on October 26. The buyback was announced the following day. That swing shows how fragile confidence has been, and it suggests turnaround skeptics were heavily positioned going into this print. The Earnings Whispers trend readings are mixed, with momentum neutral and AVWAP still negative.
The bottom line is that Agi's third quarter preserved a credible growth story: record origination, rising share, accelerating fees, and an ROE back above 20%. That growth is being bought with lower risk-adjusted margins, weaker reserve coverage, and less capital headroom, and part of the bottom-line beat came from taxes rather than operations. The next test is whether Q4 delivers the NIM improvement and fee growth management expects while delinquencies hold steady, as INSS volumes normalize and funding costs rise.
Read our earnings preview for Agi Inc: https://www.earningswhispers.com/article/AGBK/22819
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-11 | |
| Nov-03 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-01 | |
| Sep-23 | |
| Aug-20 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 |
