Integra Resources Must Prove Its Back-Half Gold Ramp As Costs And Capex Climb
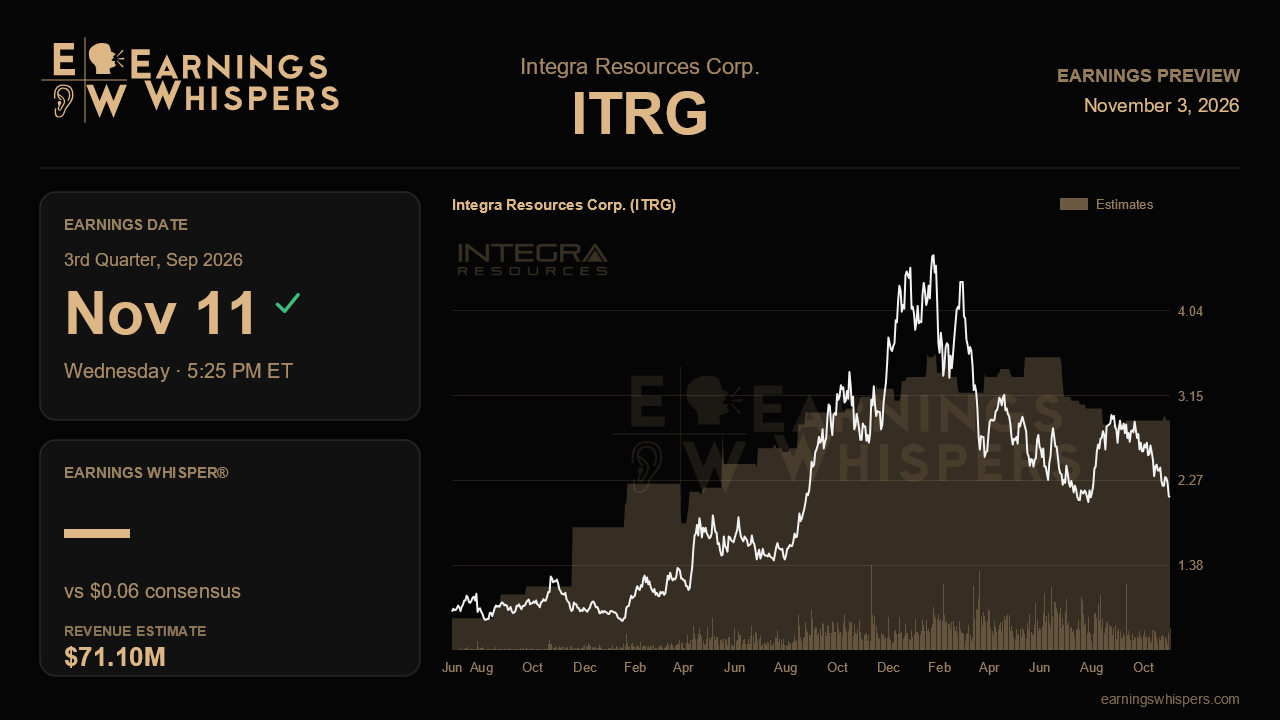
Integra Resources heads into its third-quarter report with a striking disconnect. Three months ago management delivered the long-promised overhaul of the Florida Canyon mine plan, lifting reserves by roughly three-quarters and stretching active mine life to eight years, and it posted a record cash balance. Since then the stock has fallen about 21%, badly trailing a market that slipped only modestly. The report due after the close on November 11 is the first real chance to show that the improved long-term story can coexist with a heavier, costlier present.
The Street is not asking for much. Consensus calls for earnings of $0.06 a share, matching the prior quarter but down 40% from the $0.10 earned a year ago, on revenue of about $71.1 million, essentially unchanged from both last quarter and the year-ago period. That profile describes a business running in place: stable top line, thinner per-share profit. The earnings compression is consistent with what management signaled when it raised 2026 mine-site all-in sustaining cost guidance to $3,300 to $3,500 an ounce from $2,750 to $2,950, and total cash costs to $2,300 to $2,500 from $1,900 to $2,100.
Production is the swing factor. Integra has held its 70,000 to 75,000 ounce annual target through four straight calls, but the first half ran behind pace. Second-quarter output of 16,379 ounces, up 30% sequentially on record throughput, implies a first half of roughly 29,000 ounces. Hitting the guided range therefore requires something like 20,000 to 23,000 ounces in each of the final two quarters, a meaningful step up from the second quarter's record. Flat revenue consensus suggests analysts are not fully baking in that acceleration. A third quarter that clearly moves toward the low-20,000s would validate the reaffirmed target; a print stuck near second-quarter levels would put pressure on fourth-quarter execution and invite questions about whether guidance survives.
Costs deserve a careful read rather than a reflexive one. Management attributed much of the increase to higher tons mined and stacked, royalties and excise taxes tied to strong gold prices, and pricier diesel and explosives. Royalty drag runs about $7 an ounce for every $100 move in gold, and the revised guidance assumes $4,200 gold, so price-driven cost creep is less worrying than creep from operations. Unit costs trending toward the bottom of the new range as ounces sold rise would support the argument that the first half was a volume problem. Costs breaching the top of the range would suggest something structural.
Cash is the other test. The second half carries a heavy load of stripping and the Phase 3C heap-leach pad, pulled forward from 2027, with non-sustaining growth capital guidance nearly doubled to $16.5 million to $18.5 million. Management itself flagged execution risk here. Some drawdown from the record $111.1 million balance would be understandable, but a sharp one would undercut the pitch that Florida Canyon cash flow can help fund Delamar, where the federal permitting process launched in May and a record of decision is targeted for the second half of 2027. Updates on Delamar engineering and early drilling at Wildcat, which was slated to start in August, add color but are unlikely to move near-term numbers.
Sentiment has thawed from deeply bearish to merely skeptical, yet the stock sits at $2.09, well below its 200-day average near $2.85 and just above the $2.04 low of its post-earnings range. That positioning lowers the bar somewhat. The question the report must answer is simple: are ounces finally arriving fast enough to carry costs and capital spending, or is the transformed mine plan still a story about the future rather than the current quarter?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-22 | |
| Oct-13 | |
| Oct-13 | |
| Sep-23 | |
| Sep-17 | |
| Sep-15 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-23 | |
| Jun-26 | |
| Jun-25 | |
| Jun-02 | |
| May-29 |
