Integra Resources Matches On EPS, But A 17% Production Guidance Cut Exposes Florida Canyon's Leach-Pad Bottleneck
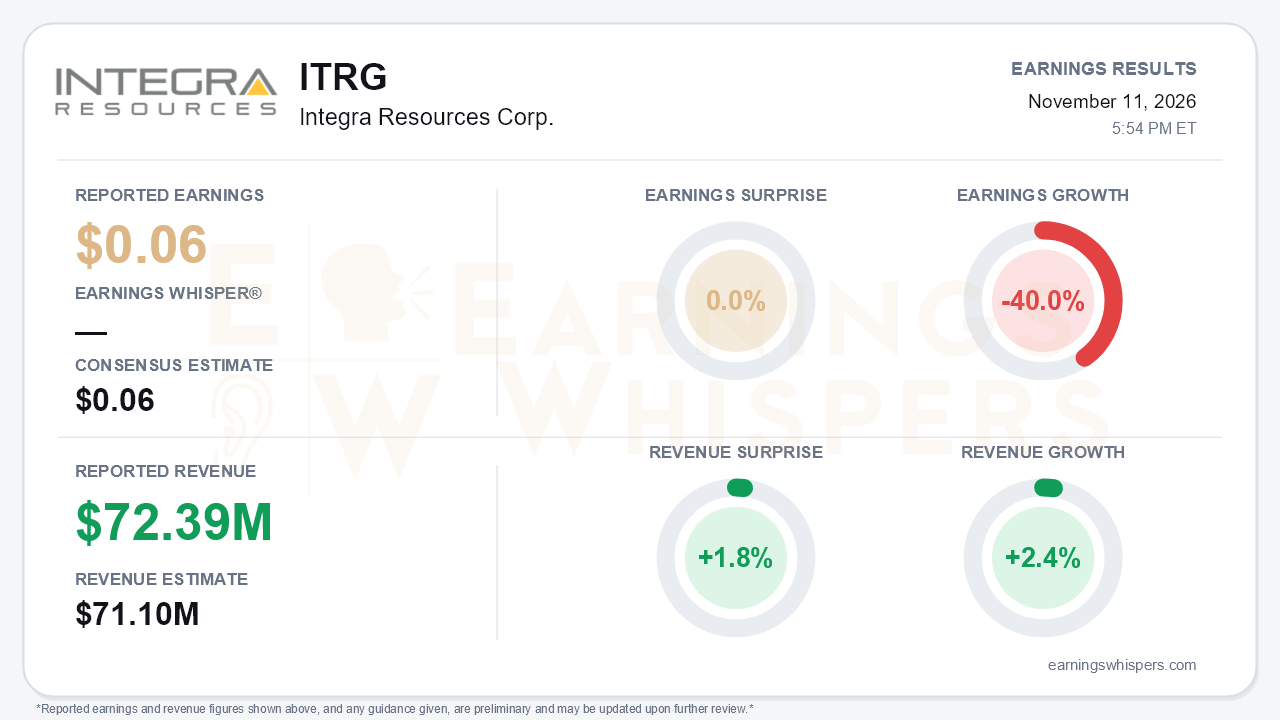
Integra Resources delivered a third quarter that matched expectations on paper and disappointed on the metric that matters most for a single-mine producer. Adjusted EPS of $0.06 matched consensus. Revenue of $72.39 million beat estimates by 1.8% and grew 2.4% year over year. Earnings, however, fell 40.0% from a year ago. The real news was the cut to 2026 Florida Canyon production guidance, from 70,000–75,000 ounces to 59,000–62,000 ounces. Management had reaffirmed that range on three consecutive calls and defended it with 'high conviction' in Q2. That is the central tension: record mining rates and a fortified balance sheet now sit alongside an admission that the processing side of the operation cannot keep up.
The quality of the quarter deserves scrutiny. Revenue grew only because the average realized gold price jumped to $4,272 per ounce from $3,464. Ounces sold fell to 16,760 from 20,265 a year earlier. GAAP results look far better than they are: net earnings of $12.9 million compare with an $8.2 million loss in Q3 2025, but that prior-year loss was driven by a $17.7 million non-cash derivative charge on convertible debt. On an adjusted basis, earnings slipped to $12.8 million from $16.3 million as diesel, explosives and royalty costs climbed. Per-share figures also absorbed dilution, with the basic share count rising to roughly 203 million from 169 million. Operating cash flow dropped to $21.8 million from $35.6 million, largely on a $15.3 million inventory build. Free cash flow fell to $11.1 million from $20.2 million.
The call made clear where the operation is breaking down. Mining reached a record 97,428 tonnes per day, up from 87,867 in Q2 and 76,800 in Q1. Production rose 8% sequentially to 17,652 ounces. But a larger share of run-of-mine ore went to a pad that management described as too small for effective blending. Recovery slid to 52.5% from 57.8% in Q2 and 59.9% in Q1. Operating margin has compressed every quarter: 46% in Q4 2025, then 40%, 33%, and now 32%. Mining rates will be reduced for the rest of the year to protect pad performance.
The revised range also implies a weaker fourth quarter. With 46,666 ounces produced through September, full-year guidance implies roughly 12,000–15,000 ounces in Q4, below Q3's output. Management says the ounces are already stacked and will recover more slowly rather than being lost.
There are offsets. Mine-site AISC of $3,059 per ounce improved from $3,371 in Q2 and came in below the previously raised $3,300–3,500 range. Context matters, though: that cost guidance had already been lifted by $550 per ounce earlier this year. Cash reached a record $119.5 million, helped by the $57.5 million equity raise, and working capital stands at $159.5 million.
The forward catalysts are real but back-end loaded:
- **Central Pit:** Management says stripping remains on schedule, with access to higher-grade ore in the first half of 2027.
- **Exploration:** Drilling at the Central Pit–Radio Tower saddle returned 1.3 g/t over 62.5 meters, the best Florida Canyon intercepts since the acquisition, and a new near-mine target emerged at the north end of the Madre Shear zone.
- **DeLamar:** GenCap was hired to structure financing, long-lead equipment orders are expected by year-end, and the Record of Decision is still targeted for the second half of 2027.
The gaps are equally real. 2027 production and cost guidance was deferred, with management offering only that it sees no 'major impacts.' Sustaining capital will stay elevated in Q4.
Investor sentiment improved sharply heading into the report, rising from -0.79 to -0.33. It remains negative, but expectations had become far less hostile. The stock has not followed. Shares at $2.10 are down 20.5% since the open after the August report and sit 24.4% below the 200-day moving average of $2.78. Earnings Whispers price and AVWAP trend readings both remain negative, consistent with a market that has steadily marked the shares down. That backdrop helps explain why softer sentiment had not translated into price support. The guidance cut gives bears fresh evidence that operational execution, not gold prices, is the binding constraint.
The bottom line is that Integra's in-line EPS and modest revenue beat were carried by gold prices, while the underlying volume, recovery and margin trends weakened. Abandoning a guidance range management had repeatedly defended damages credibility at a moment when the company is asking investors to underwrite a 2027 grade recovery at Florida Canyon and a financed build at DeLamar. The balance sheet buys time, and the drilling results are encouraging. But until leach rates stabilize and 2027 guidance arrives, the burden of proof sits squarely with management.
Read our earnings preview for Integra Resources Corp.: https://www.earningswhispers.com/article/ITRG/22832
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-11 | |
| Nov-03 | |
| Oct-22 | |
| Oct-13 | |
| Oct-13 | |
| Sep-23 | |
| Sep-17 | |
| Sep-15 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-23 | |
| Jun-26 | |
| Jun-25 |
