OptimizeRx Rallied 38% On Margins; Now It Must Show Demand Has Stopped Shrinking
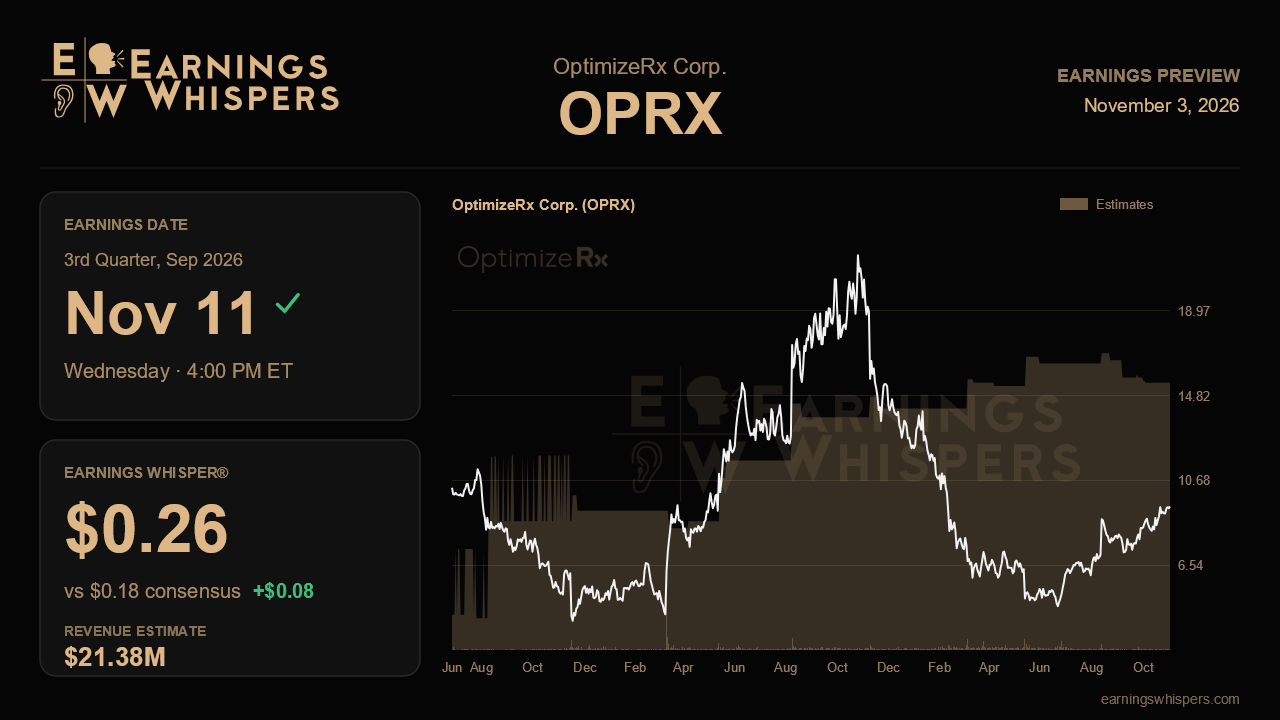
OptimizeRx heads into its third-quarter report with an odd mix of shrinking sales and a soaring stock. Revenue is expected to fall sharply from a year ago, and the company has cut its full-year outlook twice. Even so, the shares have climbed 38% since the last report while the S&P 500 slipped 2.9%. The market has decided that the margin story, the cleaner balance sheet and a new programmatic channel matter more than the top line. This report will show whether that bet was early or simply optimistic.
The Street is looking for non-GAAP earnings of $0.18 per share on revenue of about $21.4 million. That revenue figure is down 18% from the $26.1 million reported a year earlier and only modestly above the second quarter's $20.5 million. The earnings bar looks much steeper. Consensus implies roughly three times last quarter's $0.06, and the Earnings Whisper of $0.26 sits well above that. Some of the jump is mechanical. The second quarter carried a $1.7 million severance charge from a reduction in force, and the cost savings from those cuts should start to show up now. Gross margin should also improve as the company leaves low-margin managed services behind. Still, a whisper that far ahead of consensus says traders expect the operating leverage to arrive quickly and decisively.
Management reaffirmed 2026 revenue guidance of $95 million to $100 million. Consensus of $97.89 million sits in the upper half of that range. That matters because the run rate so far points to a heavily back-end-loaded year, so a big share of the target depends on a strong fourth quarter. Third-quarter revenue near or above $21.4 million, along with confident commentary on year-end bookings, would make the range look achievable. A soft quarter paired with another bare reaffirmation would raise doubts about the low end. This guidance has already been cut from an initial $118 million to $124 million, so credibility is the real asset at stake.
The demand indicators from last quarter are the ones to recheck. Net revenue retention collapsed to 90% from 110% one quarter earlier. Average revenue per top-20 pharma customer slipped to $2.7 million, and contracted revenue has run 15% to 20% behind the prior year since late 2025. Management blamed several factors:
- shorter contract durations
- pharma budget caution tied to most-favored-nation pricing
- one large customer that produced zero revenue for two straight quarters
The company assumes no back-half contribution from that customer, so any return would be upside. What would validate the recovery story is stabilization in retention and a narrowing of the contracted revenue gap. Without those, the 2027 rebound management keeps pointing to stays a promise rather than a trend.
The newer catalysts need early proof points as well. The DeepIntent integration with the authenticated EHR network went live last quarter, and management suggested the programmatic channel could roughly double the business over about two years. Nobody should expect that to be material yet. Even so, signs of customer adoption, pipeline additions, or traction for the NLAB audience builder and CopayQ would support the idea that growth can restart. Continued 25% growth in AI-enabled software and 30% growth in DAP would further strengthen the case that the revenue mix is shifting toward more durable, higher-margin dollars. Debt paydown and the $10 million buyback round out the shareholder-friendly side of the ledger.
Sentiment has flipped from modestly bearish before the last report to modestly bullish now. The stock trades at $9.41, well above its 200-day moving average of $7.31 and within about 2.5% of its post-earnings high of $9.64. In other words, it is pressing against a breakout with expectations noticeably higher than three months ago. The central question is whether OptimizeRx can pair margin gains with evidence that demand has bottomed. Better profits on a still-shrinking base would likely look priced in, while stabilizing retention and bookings would give the rally something sturdier to stand on.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Sep-22 | |
| Sep-22 | |
| Sep-14 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 | |
| Jul-23 | |
| Jun-30 |
