OptimizeRx Misses The Whisper As Margin Gains Run Into Another Revenue Guidance Cut
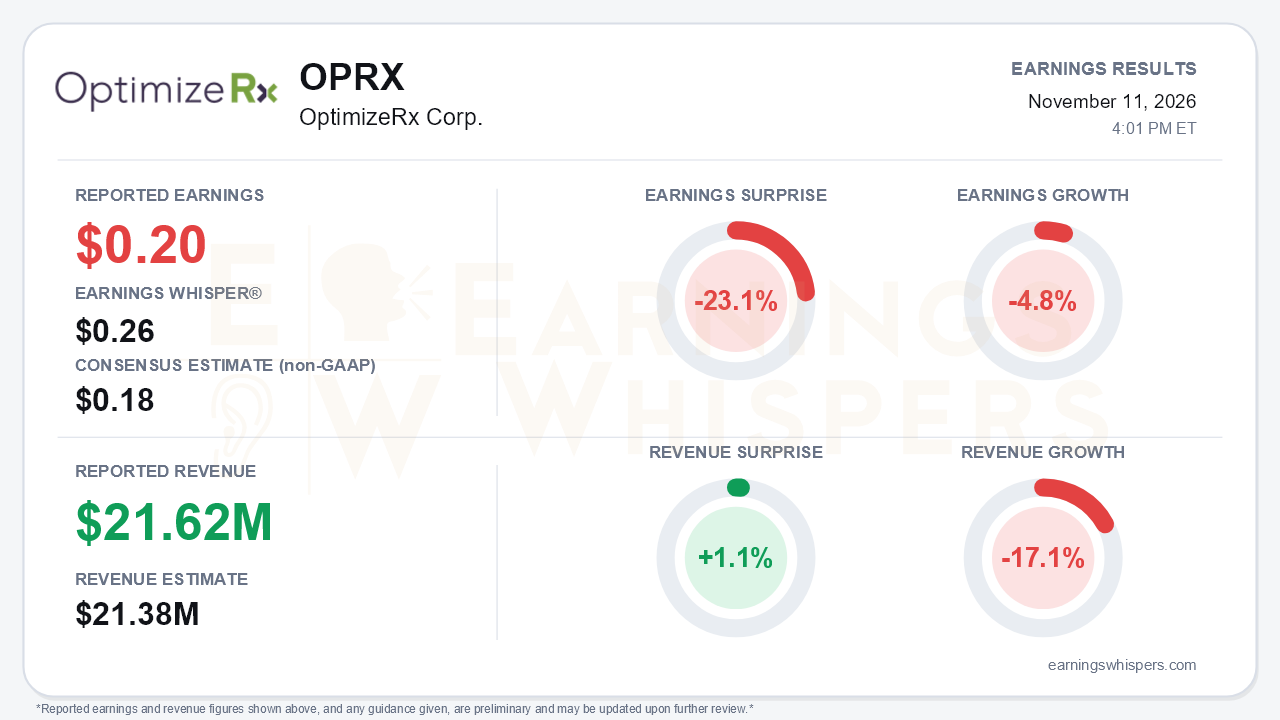
OptimizeRx (NASDAQ: OPRX) reported third-quarter non-GAAP earnings of $0.20 per share. That beat the $0.18 consensus but fell 23.1% short of the $0.26 Earnings Whisper number, a gap that matters for a stock that rallied hard into the report. Revenue of $21.62 million edged past the $21.38 million consensus by 1.1% but fell 17.1% year over year. On Earnings Whispers' normalized basis, earnings declined 4.8%, although the company's own non-GAAP presentation shows $0.20 versus $0.16 a year ago. The central tension is familiar: OptimizeRx keeps squeezing more profit out of a shrinking revenue base. This quarter, management again lowered full-year revenue guidance, to $87-$93 million, while holding adjusted EBITDA guidance at $21-$25 million.
The profitability story is real. Cost of revenues fell to $5.4 million from $8.6 million, and sales and marketing and G&A both declined. As a result, adjusted EBITDA rose to $6.3 million from $5.1 million, and adjusted EBITDA margin expanded to roughly 29% from about 20%. GAAP net income improved to $1.2 million from $0.8 million a year ago and from a loss in the second quarter. Much of that came from interest expense dropping to $177,000 from $1.15 million as debt came down. The quality of the beat still deserves scrutiny. Non-GAAP results again added back severance, about $0.7 million this quarter and $2.4 million year to date. The margin gains are also partly a function of a smaller, leaner business rather than demand recovery.
The operating metrics show the top line has not stabilized. Revenue declines have run -10%, -20%, and now -17% this year, so the rate of contraction moderated slightly, but there is no inflection yet. Net revenue retention slid to 83%, down from 90% in Q2, 110% in Q1, and 121% a year earlier. Average revenue per top-20 pharma customer fell to about $2.5 million from $3.1 million. Contracted 2026 revenue remains roughly 20% below the prior year, with no improvement since early in the year, and the hoped-for buy-ups have not materialized. Revenue guidance has now gone from $109-$114 million in March, to $95-$100 million, to the current range. Management had said in Q1 that it did not expect to adjust guidance again. Year-to-date revenue is $62.0 million, so the new range implies a fourth quarter of roughly $25-$31 million, well above Q3's run rate. Only a little over 90% of the midpoint is contracted, versus the mid-90s historically. Bears have legitimate ammunition on credibility and Q4 execution.
The call did preserve a credible 2027 growth story. A previously displaced top-five client, which generated no revenue in the first three quarters, returned and began spending in Q4. Early-RFP-season 2027 contracted revenue is tracking about 20% ahead of last year. Programmatic access expanded from DeepIntent alone to include The Trade Desk and PulsePoint. Management estimates those three platforms cover 60-70% of programmatic volume. The company also said growth outside the top 20 pharma accounts is "well into double digits," and it has added a new CMO. On the balance sheet, debt principal has been cut to $10.4 million from $19.7 million at the end of Q2, and management signaled more aggressive buybacks in Q4. Offsetting risks include a CFO transition effective January 1, policy uncertainty for pharma following the Congressional shift, and 2028 loss-of-exclusivity events that could pressure brand marketing budgets.
The market setup is more complicated than the consensus beat implies. Shares opened at $6.82 after the August report and stood at $9.35 heading into this release, a 37.1% gain. That left the stock about 29% above its 200-day moving average and just 5.7% below its November 5 inter-earnings high of $9.92. Investors had priced in a recovery, which helps explain a whisper well above consensus. Investor sentiment improved from -0.13 to -0.04 but remained slightly negative, so the rally came without broad conviction. Earnings Whispers trend signals for price, AVWAP, and sequential growth are positive, while momentum is negative. That mix fits a stock that has run ahead of a still-deteriorating revenue base.
The bottom line is that OptimizeRx delivered another quarter of margin expansion, cash generation, and deleveraging, but the revenue engine is still shrinking. Guidance now depends on an unusually large fourth-quarter ramp. The returning top-five client and stronger 2027 contracting give the turnaround narrative something concrete. However, falling retention and repeated guidance resets mean investors who bid the stock near its quarterly high are being asked to look past 2026 entirely. Q4 delivery and evidence that 2027 bookings convert into revenue are now the decisive tests.
Read our earnings preview for OptimizeRx Corp.: https://www.earningswhispers.com/article/OPRX/22834
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Sep-22 | |
| Sep-22 | |
| Sep-14 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 |
