NexPoint Residential Misses As A Third Guidance Cut, Unhedged Rate Exposure And A Dividend Review Overturn The Recovery Narrative
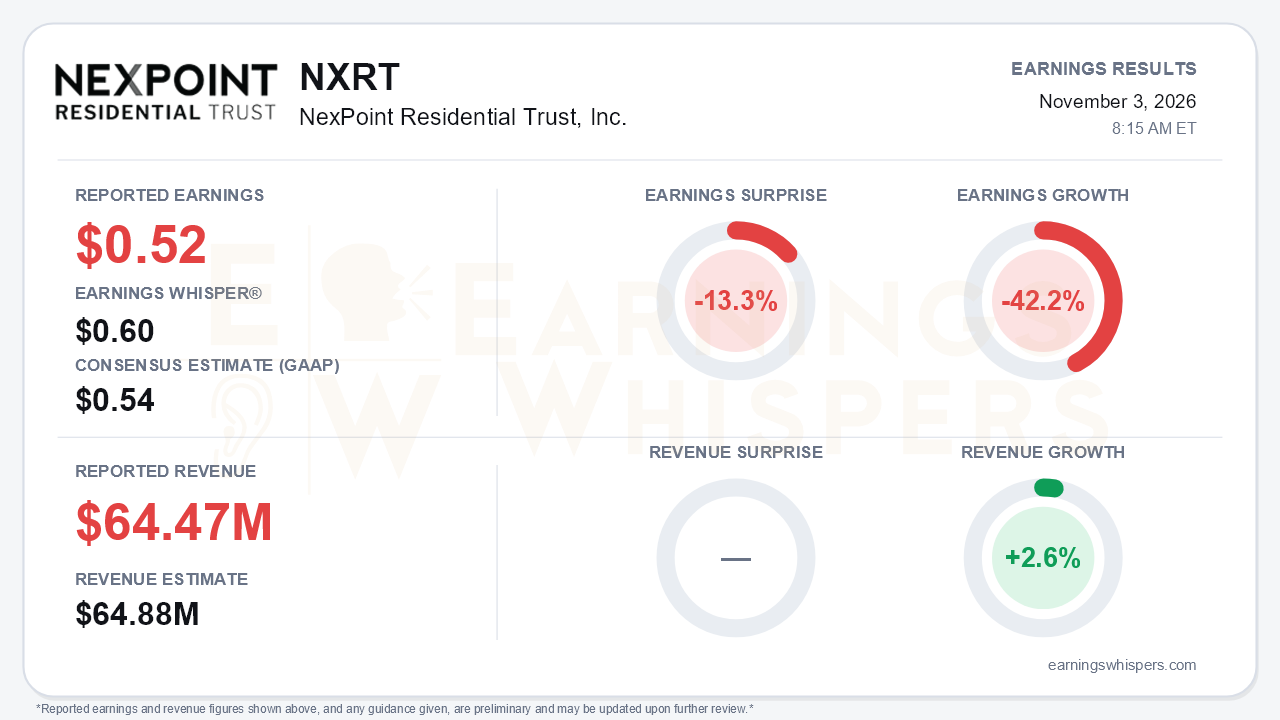
NexPoint Residential Trust (NYSE: NXRT) reported third-quarter Core FFO of $0.52 per share. That missed the $0.54 consensus by 13.3% and fell well short of the $0.60 Earnings Whisper number. Earnings fell 42.2% year over year. Revenue of $64.47 million rose 2.6% but missed the $64.88 million consensus by 0.6%. The miss was modest, but the guidance behind it was not. The quarter marked a clear break from the recovery story management had been telling. The Core FFO midpoint has now been cut a second consecutive time, and by a wider margin. The net asset value estimate was marked down sharply. The rate hedges are largely gone. And the $0.53 dividend is formally under review. That combination, not the two-cent consensus gap, is the central development.
The quality of the quarter deserves scrutiny. Total revenue grew only because of a non-same-store property. On a same-store basis, revenue fell 0.7%, occupancy slipped 70 basis points and average effective rent declined 0.7%. Same-store NOI dropped 8.2% to $35.6 million, after a 4.6% year-to-date decline, so the trend is accelerating lower. Expenses drove much of the damage. Same-store operating costs rose 11.2%, with repairs and maintenance up 16.4% year to date and marketing up 39.4%. Interest expense climbed $2.6 million. GAAP net loss widened to $0.45 per share from $0.31. Core FFO coverage of the dividend fell to 0.99x from 1.37x a year earlier, so the payout was not fully covered on that basis this quarter.
The guidance path tells the story. The Core FFO midpoint went from $2.57 initially, to $2.45 after the second quarter, to $2.22 now, on a range of $2.17 to $2.27. The same-store NOI midpoint deteriorated from -0.5% to -1.0% to -4.3%. NAV was cut to $38.33 from $46.76 just one quarter ago. Several sources of earlier optimism reversed. The expense improvement management cited last quarter fully unwound, a roughly $0.10 hit. Interest income from DST loans fell by about $0.10 as those loans were repaid faster. The Earnings Whispers guidance note characterizes the outlook as raised. That reflects a higher acquisition range of $32 million to $200 million, including Midtown Crossing, and a higher concession assumption. The earnings and NOI outlook itself was clearly lowered.
The call also exposed balance-sheet and dividend risks. About $717.5 million of swaps at roughly 1.14% rolled off in September, leaving only about 13% of floating-rate mortgage debt hedged. Management acknowledged it missed its hedging targets and said it will not hedge further at current levels. Each 25-basis-point move in SOFR is worth roughly $0.14 per share. Leverage rose to 62% of NAV, a level management itself called too high for the rate environment. Implied fourth-quarter Core FFO of about $0.35 will not cover the $0.53 dividend, and the board will decide on a possible reset by its first meeting of 2027. Earlier in the year, management had described itself as "fully committed" to the payout. Its tone shifted from confidence that recovery was "more certain than ever" to "we're not panicking," along with admissions of having been too optimistic.
There is a credible counter-narrative, though it is mostly about later periods.
- **Supply:** Submarket deliveries are 42% below the 2024 peak, starts are down 54%, and 2028 deliveries are projected as the lowest of the cycle.
- **Leasing:** Renewals were positive in every market, October retention improved to 57.5%, and blended tradeouts improved about 100 basis points sequentially to roughly flat.
- **Costs and credit:** Insurance costs fell, and bad debt held at 80 basis points.
- **Capital allocation:** Management bought Midtown Crossing, targeting a cap rate above 7%. It authorized a $150 million buyback to be funded by planned "rifle shot" dispositions.
Against that, new-lease tradeouts fell to -6% in September. Developer concessions are spreading to older assets. October physical occupancy of 92.3% is already below the 92.8% fourth-quarter assumption.
The market moved ahead of the report. Shares fell 30.3% since the post-August open to $18.04. They sit about 30% below the 200-day moving average and just 2.4% above a 52-week low of $17.62 set October 28. Price and AVWAP trend readings remain negative. Investor sentiment stayed negative but improved meaningfully, to -0.32 from -0.55. That suggests a good deal of disappointment was already expected heading into the print.
The bottom line is that NXRT's modest headline miss understates how much changed. Management cut guidance again, marked down NAV, gave up most of its rate protection and opened the door to a dividend reset. Receding supply and improving renewals keep a recovery case alive for 2027 and beyond. For now, bears have legitimate ammunition: rising rate exposure, high leverage and an uncovered dividend. With shares already near their lows, the next swing factors are execution on dispositions and the board's dividend decision.
Read our earnings preview for NexPoint Residential Trust, Inc.: https://www.earningswhispers.com/article/NXRT/21501
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-06 | |
| Sep-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 | |
| Jul-09 | |
| May-28 | |
| Apr-29 | |
| Apr-28 |
