Denali's AVLAYAH Launch Blows Past Guidance As Q4 Outlook Nearly Triples, But A Shrinking Stock Prices In Doubt
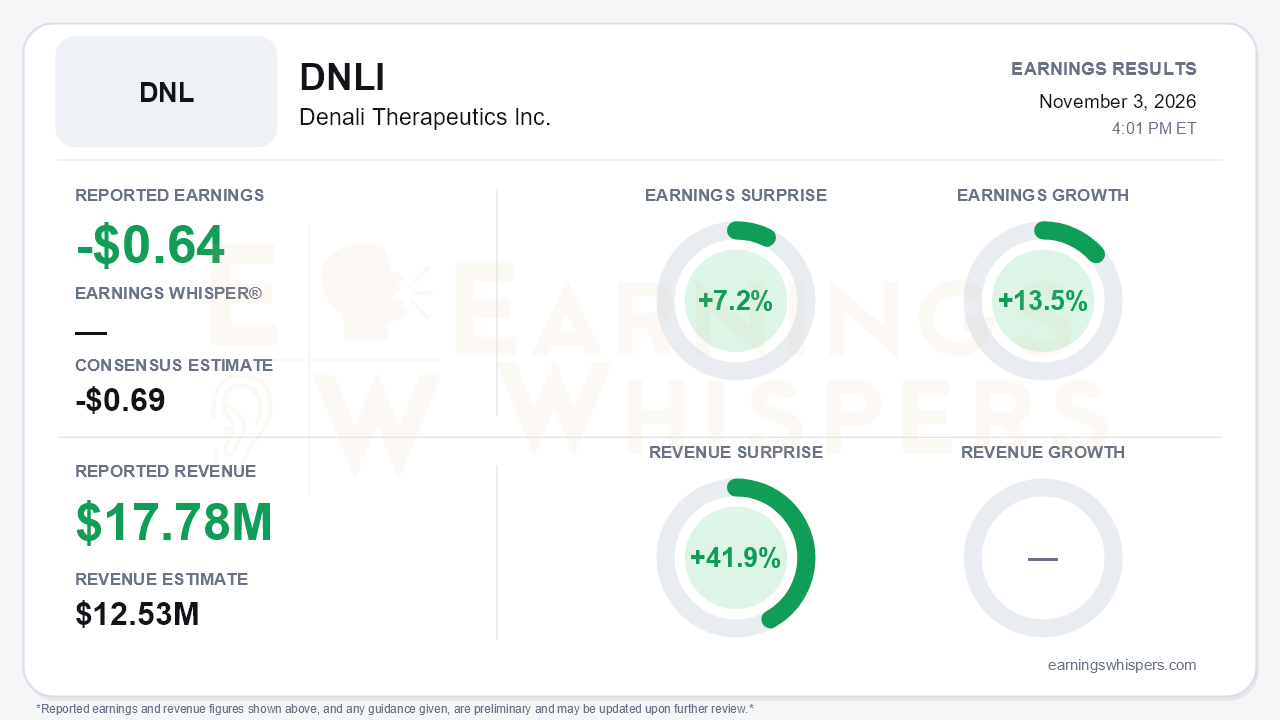
Denali Therapeutics delivered the commercial inflection its skeptics doubted. Third-quarter revenue reached $17.78 million, beating the $12.53 million consensus by 41.9%. On Earnings Whispers' normalized basis, the company lost $0.64 per share against a consensus loss of $0.69, a 7.2% beat and 13.5% earnings growth from the year-ago loss of $0.74. All of that revenue came from AVLAYAH, the Hunter syndrome therapy, in only its second full quarter on the market. It rose from $3.6 million in the second quarter and cleared management's own $10 million to $12 million guide by a wide margin. The bigger statement was the outlook. Fourth-quarter guidance of $30 million to $32 million implies more than 65% sequential growth and nearly triples the forward guide management gave three months ago. The central tension is that this launch is clearly working while the stock has spent the entire quarter going the other way.
The quality of the reported profit deserves scrutiny. GAAP net income of $70.1 million, or $0.37 per diluted share, came entirely from a one-time $194.0 million net gain on the sale of a Priority Review Voucher. The normalized loss of $0.64 reflects the underlying economics with that gain removed. Operationally, Denali still lost $126.8 million, modestly better than the $137.4 million loss a year ago.
- **Expenses:** Total operating expenses rose only about 5% as launch costs were absorbed.
- **Gross margin:** Cost of goods sold was just $0.2 million. That figure is artificially flattered because inventory built before approval was already expensed as R&D, so it will not persist.
- **Interest income:** Interest and other income fell to $2.9 million from $10.5 million.
- **Royalty-style obligation:** The balance sheet now carries a $209.7 million liability tied to a revenue participation right agreement. That claim on future product revenue is worth keeping in mind when modeling AVLAYAH's economics.
Beneath the headline, the call showed every launch metric moving the right way:
- Commercial coverage expanded from more than 50% to more than 70% of U.S. lives.
- State Medicaid listings rose from 14 to 20.
- Reach into targeted treatment centers climbed from roughly 80% to 90%.
- A permanent J-code took effect October 1, which should ease billing friction.
Management said the revenue S-curve it had previously framed for 2027 is arriving sooner. Management was also unusually candid about why. Phase 1/2 trial patients moved to commercial drug faster than expected and at maintenance dosing, which pulled growth forward. Executives explicitly warned that the Q2-to-Q3 step-up is not a run rate and that steadier growth should follow. They also still decline to disclose patient counts or start forms and have not decided on annual guidance. Bears have legitimate ammunition there: investors are being asked to extrapolate a launch without the denominator.
The forward calendar is dense. Zafinofusp alfa for Sanfilippo syndrome type A has completed the treatment period for its primary endpoint. Full data from all 20 participants are due at a medical congress in the first quarter of 2027, and a BLA seeking accelerated approval is on track for 2027. The call flagged two caveats:
- Filing timing depends on in-house manufacturing readiness for the chemistry and manufacturing section of the application.
- Infusion-reaction and anti-drug antibody questions await the full dataset.
Beyond that, Denali expects data next year from five TransportVehicle programs, including two Alzheimer's candidates, DNL628 and DNL921, where competing transferrin-receptor shuttle approaches are crowding in. The COMPASS confirmatory study for AVLAYAH is fully enrolled at 65 participants, with data in the first half of 2028. That study underpins adult label expansion and international filings, alongside distributor-led expansion into Latin America, the Gulf states and Asia-Pacific. Cash slipped to about $1.0 billion from more than $1.1 billion pro forma in the second quarter. Management still describes that as funding its goals through 2028.
The market setup is more complicated than the surprise implies. Shares opened at $25.41 after the August report and peaked at $25.74 that same day. They have since fallen 25.8% to $18.86, leaving the stock 11.1% below its 200-day moving average of $21.22. It entered this report just 8.8% above its October 19 inter-earnings low of $17.33. The Earnings Whispers price and AVWAP trend readings both remain negative, consistent with that steady erosion. Investor sentiment improved modestly from -0.30 to -0.24 but remains negative. The crowd is somewhat less pessimistic, not convinced.
The bottom line is that Denali produced a genuine commercial beat-and-raise: revenue well above both consensus and its own guide, and a fourth-quarter outlook that implies continued steep growth. The reported profit is a voucher-sale artifact, and management itself cautioned that part of the third-quarter surge was pulled forward. With no patient metrics and the stock pinned near its lows, the fourth-quarter print and the early-2027 zafinofusp alfa data now carry the burden of proving the launch curve is durable rather than front-loaded.
Read our earnings preview for Denali Therapeutics Inc.: https://www.earningswhispers.com/article/DNLI/21563
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-30 | |
| Oct-26 | |
| Oct-22 | |
| Aug-06 | |
| Jul-27 | |
| Jul-21 | |
| Jul-20 | |
| Jul-16 | |
| Jul-15 | |
| Jul-13 | |
| Jul-09 | |
| Jun-18 |
