Champion Homes Beats As Orders Surge 17% And Backlog Nears $500 Million, But Re-Accelerating Cost Inflation Clouds The Margin Outlook
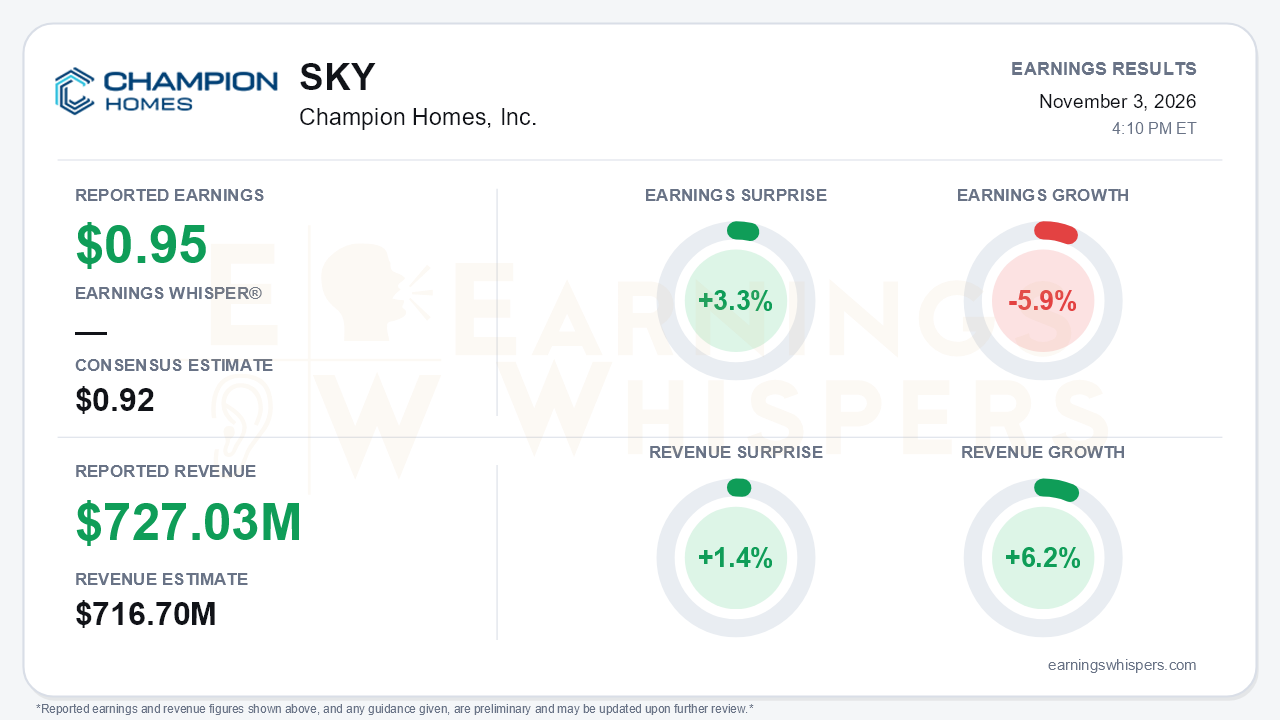
Champion Homes delivered a modest beat that matters less than what it revealed about the business's direction. Adjusted EPS of $0.95 topped the $0.92 consensus by 3.3%, and revenue of $727.03 million beat the $716.7 million estimate by 1.4%. Revenue grew 6.2% year over year, a clear acceleration from 1.3% in the prior quarter and 4.6% two quarters ago. Earnings still fell 5.9% from a year earlier. That is the central tension: demand is improving quickly, while cost inflation keeps eroding profitability, and management expects that pressure to worsen before it improves.
The quality of the beat deserves scrutiny. Gross profit slipped to $185.6 million from $187.9 million despite $42.6 million more in sales, and the 25.5% gross margin landed at the low end of management's 25-26% guidance range. Operating income fell to $65.8 million from $74.8 million. Adjusted EBITDA of $76.6 million, a 10.5% margin, was down from $83.4 million a year ago. GAAP EPS of $0.97 compared with $1.03 a year earlier. Below the operating line, rising interest income and a $2.0 million gain on debt extinguishment helped GAAP results, although the debt gain was excluded from adjusted figures. Buybacks provided a larger cushion. Diluted shares fell to about 54.5 million from 56.7 million, so per-share earnings declined less than net income did. The company repurchased another $50 million of stock in the quarter and refreshed its authorization to $150 million.
The top line, by contrast, gave investors real substance. U.S. homes sold rose 2.3% to 6,724, and average selling price climbed 4.1% to $102,700. Price realization drove much of that gain, with help from captive retail rising to 39% of sales from 35% in the prior quarter. Manufacturing orders jumped 17% year over year, compared with 7% growth two quarters earlier. Backlog swelled to roughly $500 million from $421.8 million last quarter, $316 million two quarters ago, and $266 million three quarters ago. On that strength, management guided third-quarter revenue growth to 8-10%, the most aggressive forward outlook in recent quarters. Earlier calls had pointed to mid-single-digit growth, roughly flat results, and low-single-digit growth.
The margin outlook moved the other way, and management was candid about it. Management acknowledged that material inflation did not plateau as it had assumed on the prior call. Steel and petroleum-based inputs instead accelerated, and steel is expected to rise further. Third-quarter adjusted gross margin is guided to 24-25%, below both the second-quarter result and the prior quarter's 25-26% guide, with pricing and other mitigation lagging. Operating cash flow also weakened to about $43 million from $72.5 million in the prior quarter. Cash ended at $702.8 million, still a large cushion, though down from the prior quarter after funding the Homes Direct acquisition and buybacks. Lead times of 11 weeks now sit near the top of the company's 4-12 week target range, so backlog conversion and production capacity become more important from here. Bears also have legitimate macro ammunition: interest rates moved higher during the quarter, and affordability remains strained.
The strategic catalysts are building. Homes Direct, which closed August 1 and carries roughly $70 million in revenue, contributed two months to the quarter. The planned Timberline Homes acquisition adds nine Southeast retail locations and more than $100 million in annualized revenue and is expected to close in the fiscal fourth quarter. Together, the deals extend a retail-led mix shift that supports ASP but also adds SG&A; adjusted SG&A rose 5.4% on the larger retail footprint. On the regulatory front, the New Horizon two-story HUD-code home and a visit from the HUD Secretary underscore a favorable policy backdrop. However, the timeline for implementing the ROAD Act's no-chassis provisions remains undefined.
Investor sentiment moved from slightly negative at the prior report to modestly positive, a meaningful but not euphoric improvement. Shares are up 9.4% since the opening after the prior report and trade about 4.9% above the 200-day moving average. That suggests the market had already begun to price in the demand recovery. Momentum readings have turned positive, while sequential growth and AVWAP trends remain negative, which mirrors the split between rising volume and falling profitability.
The bottom line is that Champion's quarter strengthened its growth story more than its earnings story. Accelerating orders, a record-sized backlog, and an 8-10% revenue guide show demand improving faster than the housing market. However, margin guidance is moving lower and year-over-year earnings are still declining. With shares already above their 200-day average and sentiment improved, the next test is whether pricing and scale can overtake inflation before the margin squeeze offsets the volume gains.
Read our earnings preview for Champion Homes, Inc.: https://www.earningswhispers.com/article/SKY/21626
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-07 | |
| Oct-05 | |
| Sep-29 | |
| Sep-22 | |
| Sep-18 | |
| Sep-09 | |
| Aug-26 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
