SolarEdge's 3000% Beat Rests On Tariff Refunds As Guidance Cut And Flat 2027 Outlook Stall The Turnaround
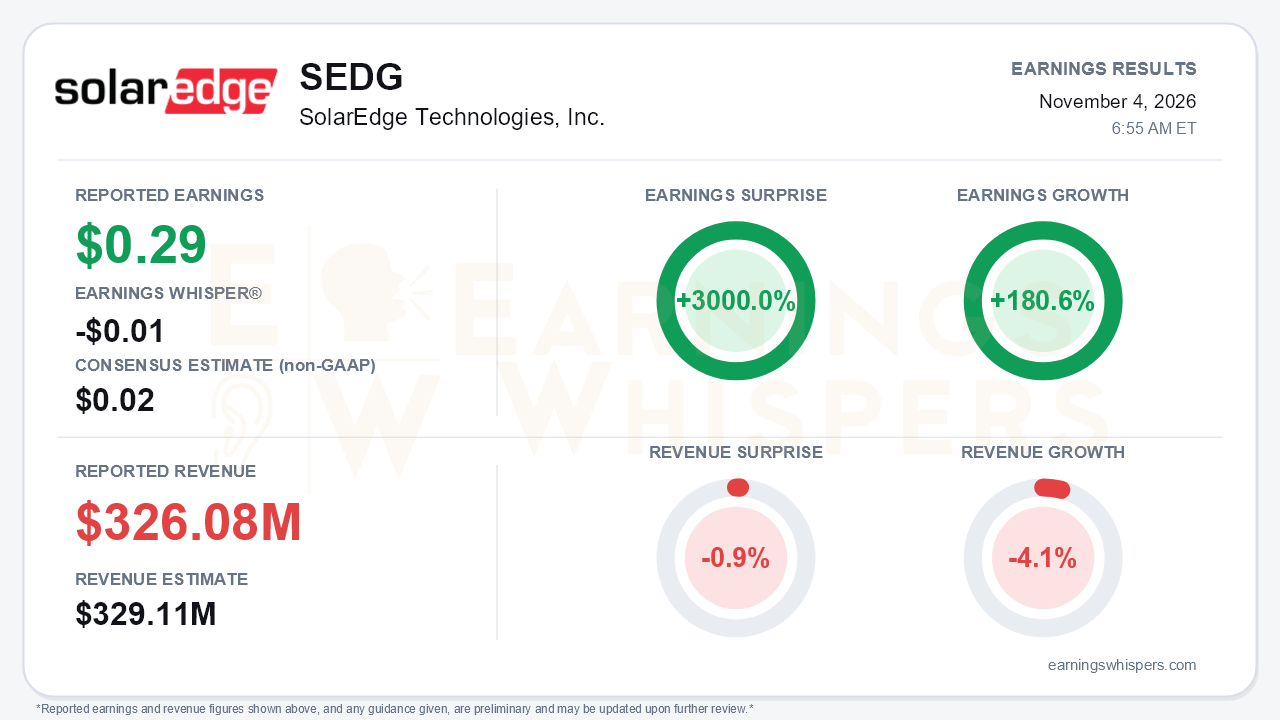
SolarEdge reported third-quarter non-GAAP earnings of $0.29 per share, far above the $0.02 consensus and the Earnings Whisper number of -$0.01. That works out to a 3000.0% surprise and 180.6% year-over-year growth, a swing from a non-GAAP loss of $0.31 a year earlier. Revenue of $326.08 million landed at the midpoint of management's guidance but missed the $329.11 million consensus by 0.9% and fell 4.1% from a year ago. Those headline figures are the least informative part of the report. The quarter's profit was flattered by a one-time tariff refund, and the forward outlook was cut well below the targets management set at its investor day. That is the central tension: the earnings beat is real on paper, but the growth turnaround it was supposed to validate has stalled.
The quality of the beat deserves scrutiny. Non-GAAP gross margin jumped to 34.7% from 28.6% in the second quarter and 18.8% a year ago, but that figure includes a $36.0 million benefit tied to IEEPA tariff matters. Excluding the refund, underlying margin was roughly 23.6%, essentially flat with the first quarter's 23.5% rather than a step change. Non-GAAP operating income was $23.9 million, which is smaller than the refund itself. Without that benefit, the quarter would have shown an operating loss. On a GAAP basis, SolarEdge still lost $0.14 per share, although that was a clear improvement from losses of $0.50 in the prior quarter and $0.84 a year ago. Free cash flow of $7.8 million marked a fifth straight positive quarter, but it was down from $22.8 million a year earlier. Net cash edged down to $260.9 million, and inventory climbed to $621.1 million from $552.6 million at year-end.
The revenue trajectory is the bigger problem. Year-over-year growth went from +46% in the first quarter to +20% in the second and then to a 4.1% decline in the third. Europe fell 8.2% sequentially to $141.7 million. That is a sharp reversal from earlier calls that highlighted European strength, and Germany's EEG feed-in-tariff reform now looms as a new demand risk. U.S. residential softness, flagged since the first quarter, persists amid delayed FEOC guidance and higher rates. Fourth-quarter revenue guidance of $245 million to $275 million sits about $50 million below the roughly $310 million implied at the investor day. Management broke the gap into three pieces:
- about $35 million from channel inventory discipline in the U.S. and Germany;
- about $10 million from exiting underperforming markets;
- about $5 million from currency.
Gross margin guidance of 17% to 21% compares with 22% to 26% guided for the third quarter, reflecting under-absorption, and only about $4 million of refunds remain. Management also guided first-quarter 2027 revenue down 10% or more sequentially and framed 2027 as flat revenue with only adjusted EBITDA breakeven. Capex was cut to $45 million to $55 million from $60 million to $80 million. That is a notable retreat from the 'offense' posture management struck in late 2025.
The call did preserve a credible long-term product story. Nexis contributed more than $100 million in the quarter, and its U.S. rollout began in July after a California utility approved its meter collar. Battery upsell and retrofit revenue topped $30 million, up from more than $20 million in the second quarter, and storage was the largest product category for a second straight quarter. Management quantified safe-harbor agreements at $1.7 billion, potentially $3.3 billion including optimizers. The solid-state transformer program for AI data centers advanced with 34.5kV-class insulation testing, an 800V DC whitepaper with NVIDIA and an extended Infineon collaboration. However, the commercial timeline is unchanged: a lab system by the end of 2026, pilots in 2027 and volume in 2028. Restructuring should yield about $5 million in net quarterly savings, with the full benefit arriving in the first quarter of 2027. Market exits, meanwhile, will remove $40 million to $50 million of annual revenue.
Investors were already bracing for trouble. Earnings Whispers sentiment stayed negative and weakened modestly, moving from -0.32 to -0.40 heading into the report. Shares closed at $32.88 before the release, down 17.7% since the open following the August report. That left them 22.2% below the 200-day moving average of $42.24 and 21.2% below the inter-earnings high of $41.74, set on the day of the prior report. The stock hit a 52-week low of $28.11 on October 28 and had rebounded 17.0% from that level. Price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral.
The bottom line is that SolarEdge's eye-catching beat was largely a tariff-refund event. The fundamental news cut the other way: decelerating revenue, a guide roughly $50 million below investor-day targets, compressed margin guidance and a 2027 framed around breakeven rather than growth. Nexis, storage and the SST program give bulls a longer-dated narrative. Over the next several quarters, though, bears have legitimate ammunition.
Read our earnings preview for SolarEdge Technologies, Inc.: https://www.earningswhispers.com/article/SEDG/21738
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 12 hours | |
| 13 hours | |
| 14 hours | |
| 14 hours | |
| 16 hours | |
| Oct-27 | |
| Oct-15 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 |
