Ternium Misses On A Peso-Driven Tax Hit, But The Bigger Story Is A Recovery That Is Leveling Off
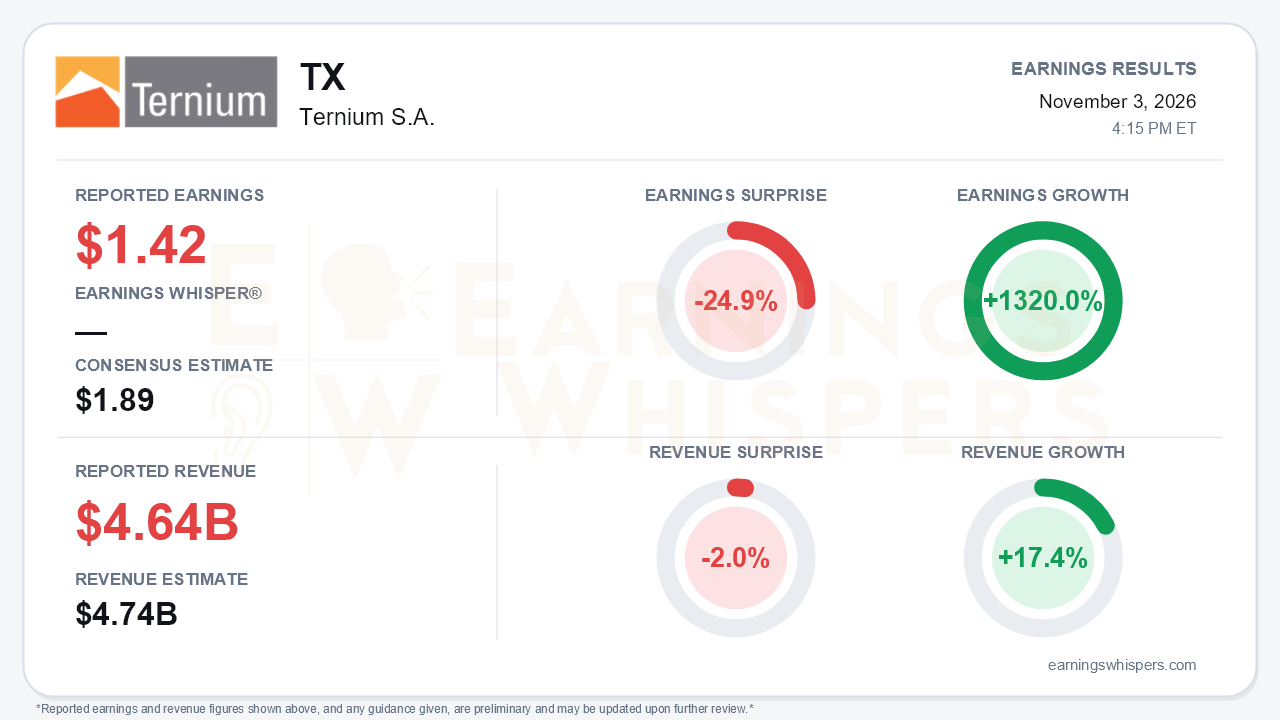
Ternium (NYSE: TX) reported third-quarter earnings of $1.42 per ADS, missing the $1.89 consensus by 24.9%. Revenue of $4.644 billion rose 17.4% year over year but came in 2.0% below the $4.74 billion estimate. On the surface, earnings grew 1320.0% from a year ago, when equity holders' net income was only $21 million and the consolidated result was a $270 million loss. Neither the miss nor the growth figure reflects operations well. The shortfall came largely from below the operating line, while the operating recovery continued. The more important question is how much further that recovery can run, and management's fourth-quarter outlook suggests it is leveling off.
The miss deserves context. Ternium booked a $116 million deferred tax loss, mainly because the Mexican peso depreciated against the dollar, which pushed the income tax line to $215 million from $23 million in the second quarter. Net income fell to $368 million from $465 million, and equity holders' share dropped to $279 million from $344 million, even though pre-tax profit rose to $583 million from $487 million. The company also recognized a $74 million decline in the fair value of Argentine securities. Operating results moved the other way. Adjusted EBITDA rose 10% sequentially to $785 million, compared with $420 million a year earlier, and the margin held near 17%. Steel cash operating income per ton rose to $186 from $169 in the prior quarter and $104 a year ago, as higher realized prices and a 5% increase in shipments to 4.04 million tons more than offset rising raw material and purchased-slab costs.
Cash generation improved meaningfully. Operating cash flow reached $613 million in the release, while the call referenced roughly $630 million. Either figure was achieved despite a $148 million working-capital build. Combined with capex of $398 million, that produced $215 million of free cash flow, after negative free cash flow in each of the prior comparable periods shown. The balance sheet moved back to a $22 million net cash position from $112 million of net debt in June. Nine-month capex of about $1.2 billion is well below the $2.0 billion spent a year earlier, and management pointed to roughly $1.2 billion again in 2027.
Mexico is the engine of the story. Shipments there hit an all-time high, rising 13% over nine months as Ternium replaces imported steel in both commercial and industrial channels. Management now also cites underlying demand from data centers and gas pipelines. Mexican prices rose about 5% sequentially, and because industrial contracts reprice with a lag, management expects higher Mexican volumes and EBITDA in the first half of 2027 than in the fourth quarter. The Pesquería slab mill now has a firmer February 2027 start-up date. The rest of the portfolio is weaker:
- **Brazil:** apparent steel consumption is expected to fall 2.7% this year amid surging imports from Vietnam, Korea and Egypt.
- **Mining:** sales fell 18% sequentially after part of the Usiminas mining operations were idled, and shipments will fall further in the fourth quarter.
- **Argentina:** construction, appliances and autos remain soft.
The deceleration is the central tension. Sequential EBITDA growth has gone from 21% in the first quarter to 50% in the second to 10% now, and fourth-quarter EBITDA is guided broadly flat. That breaks the pattern of sequential-increase guidance on prior calls. The Mexican customer restocking cited last quarter has not materialized, and Pesquería's earnings contribution has largely slipped to 2028. The interim dividend was held at $0.90 per ADS. Management did signal that payouts should move back toward pre-cut levels and could rise if current trends hold.
Investors had already turned more constructive heading into the print. Earnings Whispers sentiment rose to 0.32 from -0.06 at the prior report, a meaningful shift from slightly negative to clearly positive. The stock, however, has moved little: it is up just 3.3% from the $50.00 open after the August report to $51.65, though it sits about 8.3% above its 200-day moving average. The trend readings are mixed, with momentum positive while AVWAP remains negative. Together, these suggest improving fundamentals that have not yet translated into sustained price strength.
The bottom line is that Ternium's EPS miss looks more like a currency-driven tax artifact than an operating failure. EBITDA, steel margins, free cash flow and the balance sheet all improved, and Mexico continues to take share. Bears still have legitimate ammunition, however. Growth is plateauing into a flat fourth quarter, Brazil and mining are deteriorating, and the Pesquería payoff is further out than hoped. The next leg depends on Mexican pricing and volume carrying through to early 2027 while the rest of the footprint stabilizes.
Read our earnings preview for Ternium S.A.: https://www.earningswhispers.com/article/TX/21987
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-08 | |
| Aug-21 | |
| Aug-05 | |
| Aug-04 | |
| May-12 | |
| May-05 | |
| Apr-15 | |
| Mar-31 | |
| Mar-20 | |
| Mar-01 | |
| Feb-19 | |
| Feb-18 |
