Navios Partners Doubles Adjusted EPS As Tanker And Dry Bulk Strength Lifts Earnings; Deleveraging Goal Met, Capital-Return Decision Set For Q1
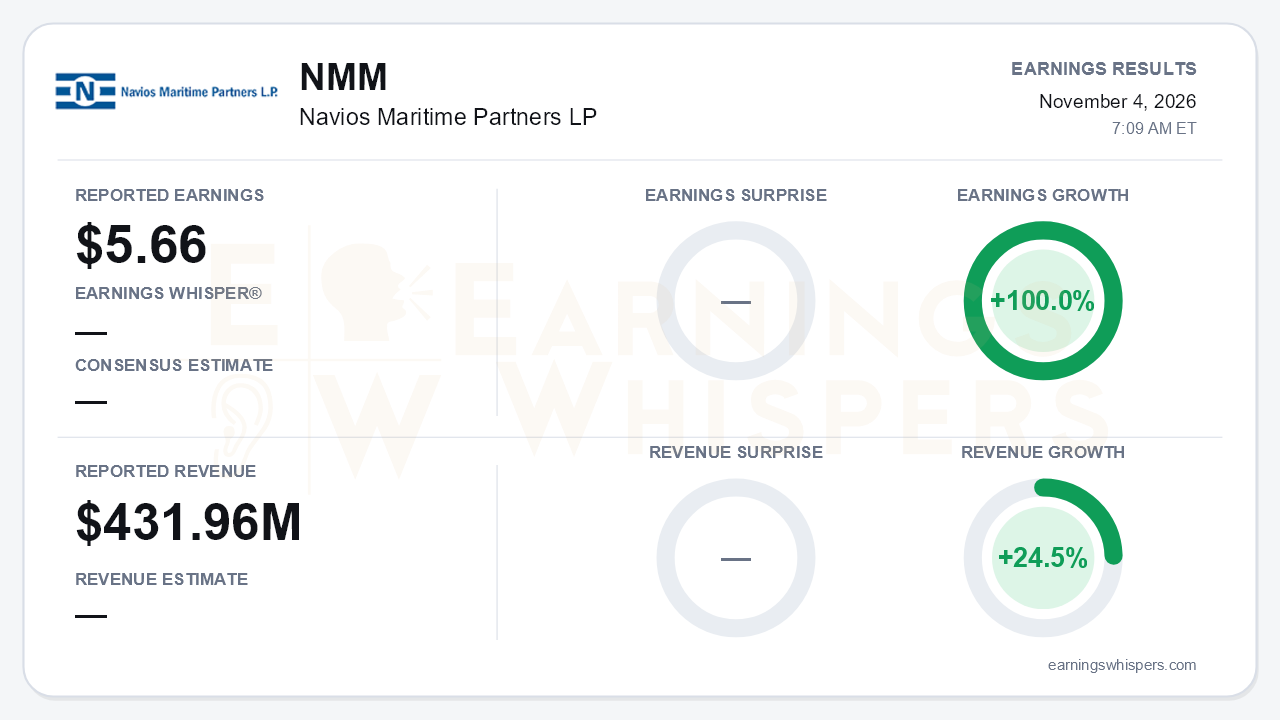
Navios Maritime Partners (NYSE: NMM) delivered its third straight quarter of sequential improvement. Adjusted earnings came in at $5.66 per unit, up 100.0% from a year ago, on revenue of $431.96 million, up 24.5%. No consensus estimate was available, so the quarter has to be judged on its own trajectory, and that trajectory is strong. Revenue has climbed from $357 million in Q1 to $410 million in Q2 and $432 million in Q3. Adjusted net income rose from $98 million to $135 million to $164 million over the same span. The central development, however, is not the earnings line. Navios has reached its 20-25% net loan-to-value target at 23.1%, and management says it will recalibrate capital returns in the first quarter of 2027. That shifts the investment debate from whether the balance sheet can be repaired to what unitholders will actually receive.
The quality of the quarter is mostly solid, but the GAAP figure needs context. GAAP earnings of $6.42 per unit include a $21.9 million gain on vessel sales. Across nine months, sale gains total $63.4 million, which flatters reported net income of $459.9 million. Comparisons with last year also cut both ways. The year-ago adjusted figure of $2.83 excluded a $27.3 million accelerated amortization charge, and that charge helps explain why reported depreciation fell to $83.2 million from $109.0 million. Stripping out those items, the core story is clean. Adjusted EBITDA rose $78.0 million to $272.0 million, almost entirely on rate, not volume. Available days rose just 0.3%, while the combined time charter equivalent (TCE) rate jumped 25.7% to $30,371 per day. Operating cash flow more than doubled to $235.4 million, which gives the earnings real support.
The gains came from two of the three segments. Dry bulk TCE surged 43% to $25,708 per day, and tankers rose 38% to $36,183. Containerships slipped about 1% to $31,619. That is the long-dated, contracted part of the fleet, so the dip signals stability rather than distress. The call also flagged a real cost issue. Daily opex rose roughly 8% to $7,320, driven by maintenance, repairs and spares, after running flat in Q2. Rate gains currently dwarf that increase, but it is the one margin metric moving the wrong way.
On the outlook, management now cites an adjusted EBITDA run-rate above $1 billion, up from above $900 million last quarter. The contracted backlog reached a record $5.0 billion, up from $4.4 billion in Q2 and $3.75 billion at year-end, helped by $735 million of new charters, $537 million of it in containers. Navios committed about $703 million to seven more newbuildings. The four 10,100 TEU containerships are already chartered for 5.6 years at about $48,263 per day. Bears have legitimate ammunition here:
- The newbuild program has grown to 34 vessels and $3.1 billion, versus $2.1 billion in Q1.
- Investing outflows reached $613.6 million through nine months.
- Management is now open to deals outside its three core segments, which raises questions about capital discipline.
- About 87% of 2027 dry bulk days are open or index-linked, leaving earnings exposed to rate swings.
- Management again warned that a prolonged Hormuz closure could trigger a recessionary demand shock, as attacks in Hormuz and the southern Red Sea increase.
Forward visibility is good but not uniformly higher. Q4 is 80.2% fixed at $31,837 per day. For 2027, 56.5% of days are fixed at $29,605, slightly below the Q3 combined TCE. Contracted revenue already covers 2027 cash costs, so the downside is cushioned. The upside, though, depends on spot markets, including VLCC rates that management said spiked to about $1.4 million per day.
The market context is limited. Current pricing and sentiment readings were not available for this report. For reference, shares opened at $86.48 after the August report, comfortably above a 200-day moving average now at $75.50. That suggests the market had already been rewarding the rate cycle and the deleveraging heading into this print.
The bottom line is that Navios produced a high-quality, rate-driven quarter with improving cash flow, a record backlog and a balance sheet that has hit its target. The unresolved tension is capital allocation. The distribution remains just $0.06 per quarter, while newbuild commitments keep growing. Rising opex and spot exposure are watch items, but the Q1 2027 capital-return recalibration is now the catalyst that will define how much of this earnings power reaches unitholders.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-27 | |
| Sep-18 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-17 | |
| Jul-30 | |
| Jul-28 |
Navios Maritime Shipping, Stock Of The Day, Eyes Buy Point After 50% Rally
NMM
Investor's Business Daily
|
| May-27 | |
| May-21 | |
| May-21 | |
| May-19 |
