Burford Capital Beats On Third Quarter But Pauses New Commitments To Cut Debt
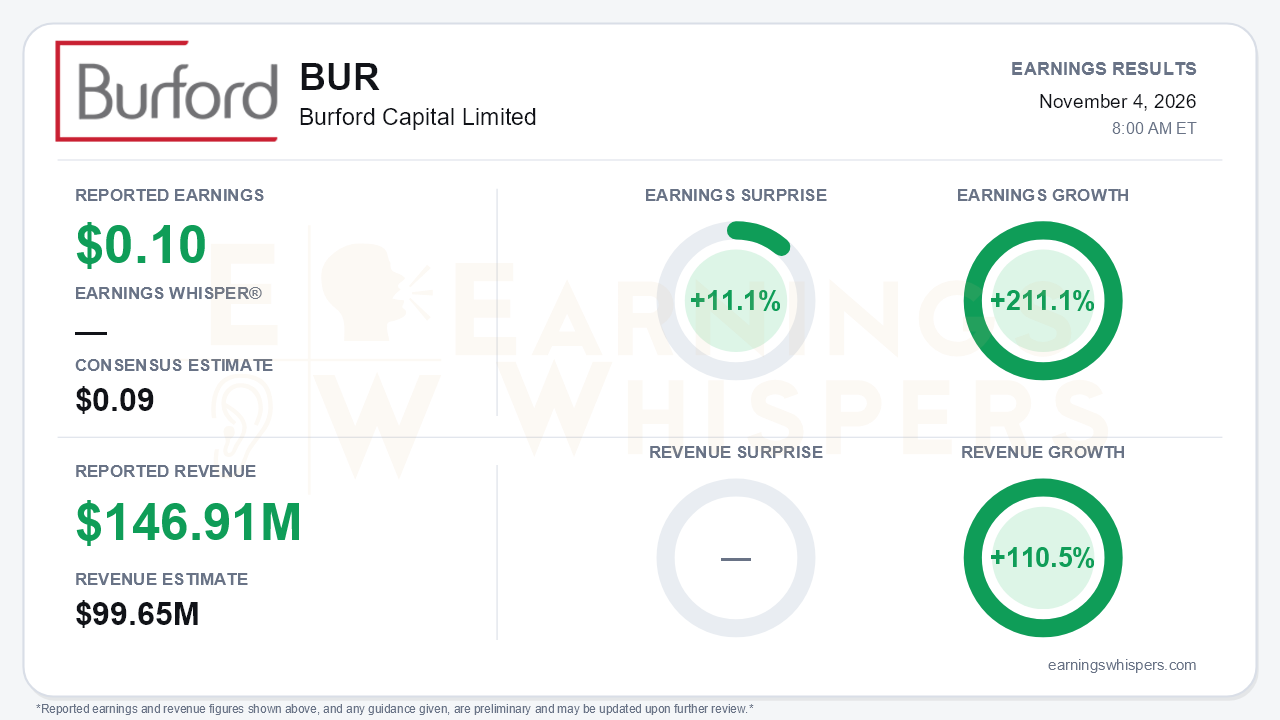
Burford Capital delivered its most constructive quarter since the YPF reversal upended the story earlier this year. The litigation financier reported third-quarter earnings of $0.10 per share, topping the $0.09 consensus by 11.1% and rising 211.1% from a year ago. Revenue of $146.91 million beat the $99.65 million consensus by 47.4% and grew 110.5% year over year. The central tension is that Burford is choosing balance-sheet repair over growth. The quarter showed the earnings power of the existing portfolio, but new business is being held back on purpose while leverage stays well above where it needs to be.
The quality of the quarter is better than the GAAP figures alone suggest, though a few caveats apply. Burford's own release cites total revenues of $135 million, below the normalized $146.91 million figure, which likely reflects a different revenue definition. Either way, management argues the number would have been well over $200 million without a record adverse move in market discount rates of roughly 90 basis points, a non-cash fair-value hit. Capital provision income reached $116 million, compared with a roughly break-even second quarter and a first quarter pushed into a loss by the YPF write-down. Annualized ROE was 13.4%, and management said it would be "into the 40s" excluding rates. That adjusted framing is management's view, not a GAAP result. Even so, the direction from Q1 to Q3 is unambiguous. Fair value of capital provision assets rose to about $2.5 billion from $2.3 billion, and cumulative cash realizations passed $4 billion.
The call's real shift was in tone and in execution on the balance sheet. Management pledged deleveraging in Q1 and Q2, and this quarter it delivered:
- Debt fell by $100 million.
- The 2028 maturity was retired, funded by new 2029 notes.
- Debt to tangible book improved to 3.2x from 3.5x cited earlier in the year.
The roughly $10 million in annualized compensation savings announced last quarter is holding, and G&A is tracking below the prior year. The cost of this pivot is visible. Year-to-date new definitive commitments are below last year because management is explicitly passing on mid-band, lower-return deals. That is a sharp turn from a 39% commitment surge in fiscal 2025 and a strong first quarter. Other figures also slipped:
- Year-to-date net realized gains fell to $82 million from $93 million.
- Liquidity dropped to $514 million from $733 million at the end of Q2, after the debt redemption.
- Leverage remains above the 2.0x incurrence covenant, which leaves no incremental debt capacity, and management has set no formal leverage target.
The catalyst list lengthened meaningfully. After the quarter, a 2015-vintage matter carried at about $31 million produced roughly $64 million in cash. The release cites a 12x return, while the call characterized it as more than 11x ROIC. The result supports management's argument that older vintages are not impaired vintages. Burford is entitled to roughly one-third of a Cameroon mining arbitration award of more than $600 million. A funded case also produced a record U.S. patent jury verdict against Apple. On YPF, nine amicus briefs, including one backed by 15 U.S. states and territories, were filed at the Supreme Court in support of Burford's position. Bears have legitimate ammunition, however. Each of these wins still faces lengthy enforcement or appeal processes. About $28 million of year-to-date deployments were expensed as non-capitalizable, including an $18 million reversal of prior-period amounts. Management also gave no formal guidance and did not update the $5.2 billion modeled-realizations figure.
The market setup reflects deep skepticism. Investor sentiment entered the report negative and slightly weakened, moving from -0.51 to -0.55. That is a modest shift, but it came from an already pessimistic base. Shares at $3.79 are down 10.8% since the open following the August report and sit 29% below the 200-day moving average of $5.34. The stock hit a 52-week low of $2.86 on October 19 and has since rebounded 32.5% from that level, though it remains 16.1% below the inter-earnings high of $4.52. The Earnings Whispers momentum and AVWAP trend readings remain negative, consistent with a stock that is bouncing rather than re-rating.
The quarter changes the investment setup in one important way. Burford is no longer playing pure defense. It is converting assets to cash, retiring debt, and adding legally significant wins to the docket. What it has not yet shown is a return to growth, because new commitments are being deliberately constrained and liquidity has shrunk.
The bottom line is that Burford posted a clean beat and a credible case that its portfolio still generates substantial value beneath non-cash rate noise. Investors are still being asked to wait on enforcement timelines, further deleveraging, and a restart of new business before the stock's deep discount to its longer-term trend can narrow.
Read our earnings preview for Burford Capital Limited: https://www.earningswhispers.com/article/BUR/21683
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 13 hours | |
| Oct-27 | |
| Oct-26 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 | |
| Jul-24 | |
| Jul-07 |
