Protalix Faces A Lumpy Elfabrio Quarter As Street Braces For Revenue Dip
Protalix BioTherapeutics heads into its third-quarter report with an unusual setup: management spent the last call describing a business with genuine momentum, yet Wall Street is modeling a sharp step backward. The tension comes down to how the company's Elfabrio sales to partner Chiesi actually land on the books. Orders are driven by inventory decisions, so a strong quarter can be followed by a thin one even when underlying patient demand is healthy. This report will test whether the Street is simply respecting that lumpiness or anticipating something softer.
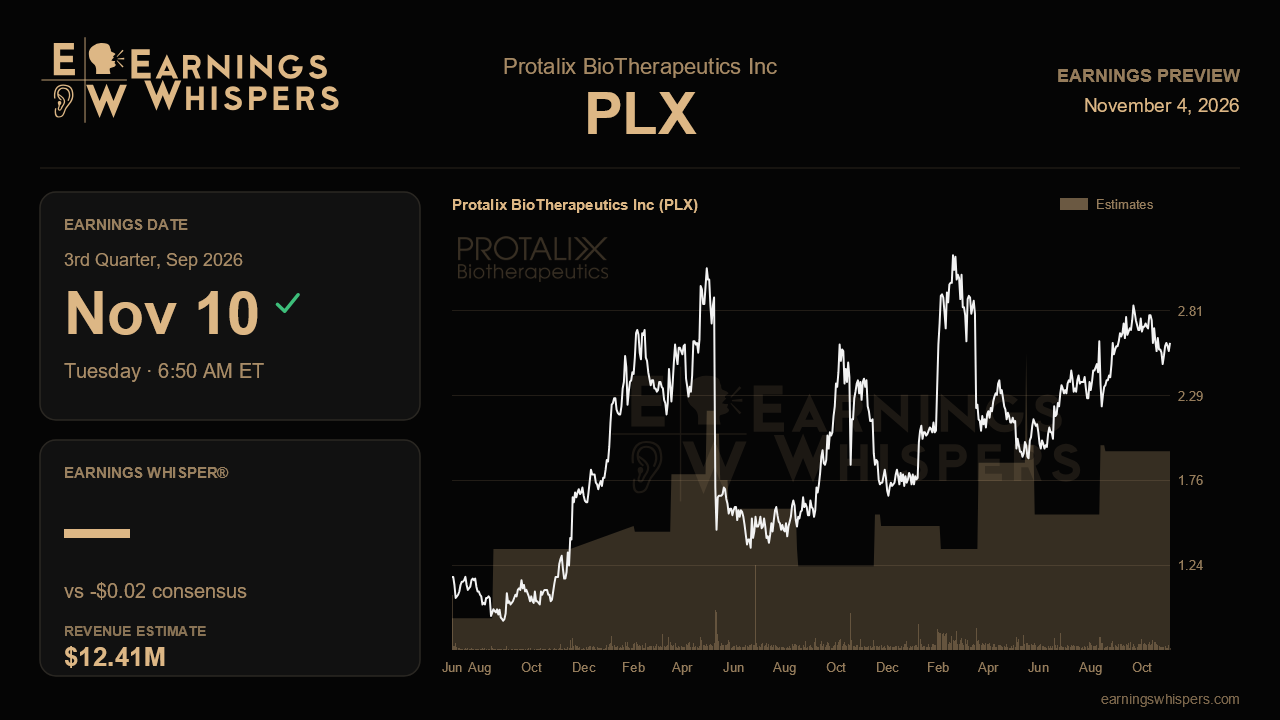
Consensus calls for revenue of about $12.4 million, down roughly 30% from $17.9 million a year ago and well below the $19.9 million posted last quarter. On the bottom line, analysts expect a loss of $0.02 per share, compared with a $0.03 profit in the year-ago period and $0.05 last quarter. That is a meaningful contraction, not a rounding error, and it would interrupt the profitability swing that made the second quarter look like an inflection point.
The guidance math helps explain the caution. Management has reaffirmed its full-year 2026 revenue target of $78 million to $83 million three times now, including $33 million to $35 million from Chiesi excluding milestones and $20 million to $23 million from Eliso. With $53.6 million already booked in the first half, inflated by a $25 million Chiesi milestone, the second half needs roughly $24 million to $29 million. A $12.4 million third quarter sits right on that pace and leaves the fourth quarter needing something between flat and moderately higher. In other words, the consensus is not a bearish call on the year; it is consistent with the low to middle of the range. The more telling question is why management declined to raise guidance after a strong first half. A beat this quarter would make that reaffirmation look conservative, while a miss would suggest the warnings about ordering patterns were a genuine signal.
The bigger narrative claim from last quarter was that the every-four-weeks Elfabrio dosing regimen approved in Europe is beginning to drive second-half growth. That is the piece worth scrutinizing. Investors should look for commentary on Chiesi's underlying sell-through rather than just shipments, any early contribution from the newly approved South Korean market, and whether the patent term extension changes how management frames the product's long-term economics. Margins also deserve attention. Cost of revenues climbed last quarter, and the tax line roughly doubled on GILTI and Section 174 effects, so lower revenue could magnify the drag. The ongoing R&D grant that trimmed spending to $4.4 million should help cushion the loss, and confirmation that it remains a steady offset would support the cost story. On the pipeline, the company said PRX115 enrollment in its gout study should finish by year-end with top-line data in the second half of 2027, and an update on the long-promised PRX119 indication selection is overdue.
The market has leaned in. Shares are up nearly 5% since the last report while the S&P 500 slipped, an outperformance of about 7.5 percentage points, and sentiment readings have turned more constructive than they were a quarter ago. At $2.61 the stock sits above its 200-day moving average of $2.42 and in the upper half of a post-earnings range that has shifted meaningfully higher than the prior quarter's, though it remains well short of the $2.85 high.
Ultimately, a soft quarter is already expected. What matters is whether management can convincingly tie any revenue dip to inventory timing while showing that Elfabrio demand, especially under the new dosing regimen, is still building. If it can, the full-year guidance holds and the improving story stays intact; if not, the unraised outlook will start to look like a ceiling rather than a floor.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Sep-22 | |
| Sep-08 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| May-13 | |
| May-13 | |
| May-13 | |
| May-06 | |
| Mar-18 | |
| Mar-18 |
