Protalix Beats Easily On Elfabrio-Driven Margin Expansion, But Conservative Guidance And Softer Trial Timing Temper The Setup
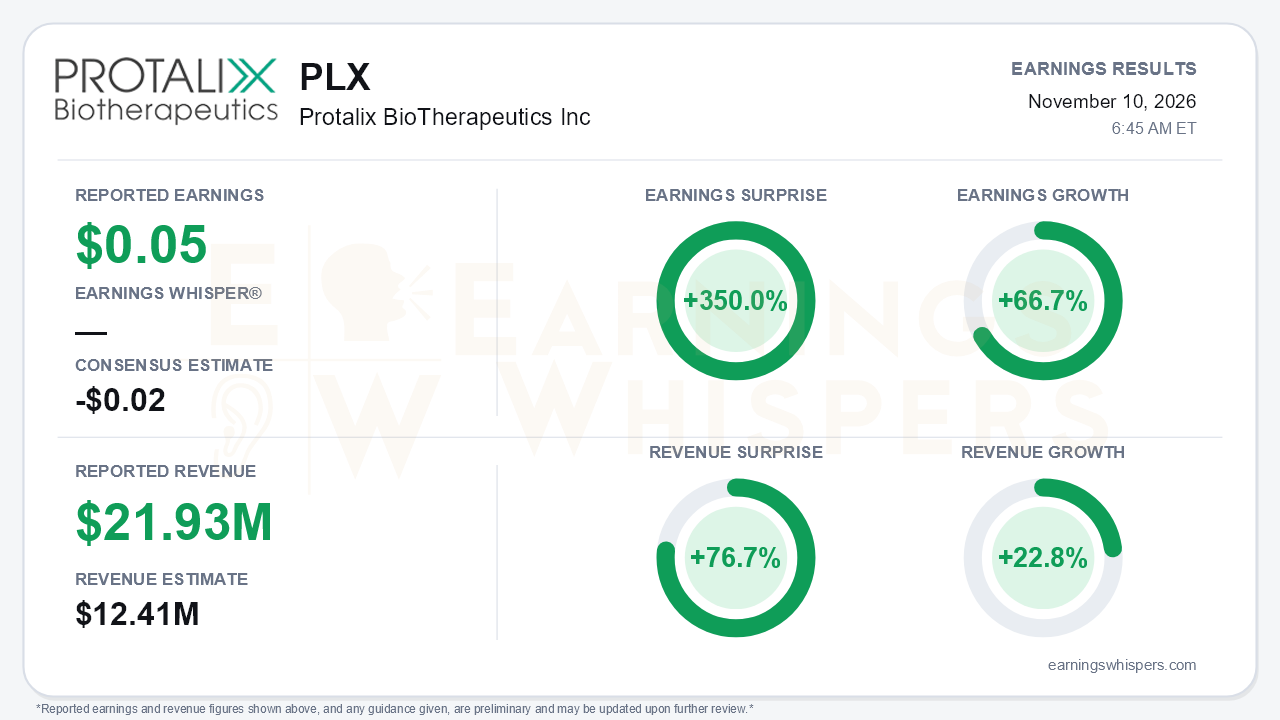
Protalix BioTherapeutics delivered a decisive beat in the third quarter. Earnings of $0.05 per share topped a consensus estimate calling for a $0.02 loss, a 350.0% surprise. Revenue of $21.93 million beat the $12.41 million consensus by 76.7%. Earnings grew 66.7% year over year and revenue rose 22.8%. The bigger story is that the Street was positioned for a loss in a quarter with no milestone payment, and the company instead posted its third consecutive quarter of sequential product-revenue growth. That shows the underlying commercial supply business is becoming self-sustaining. Total revenue moved from $17.9 million a year ago to $19.9 million in Q2 and $21.9 million in Q3.
The quality of the beat holds up better than the headline surprise might suggest. License and R&D revenue was a negligible $0.1 million, so essentially all of the quarter came from product sales of $21.8 million, up from $17.7 million a year earlier. Management attributed the gain primarily to higher sales to Chiesi. Cost of revenues fell to $7.9 million from $8.3 million despite the higher sales, helped by lower Fiocruz volume, which the company tied to delivery timing. Implied product gross margin reached roughly 64%, up from about 61% in Q2 and about 45% in Q1. Operating income nearly doubled to $4.0 million from $2.1 million, even as R&D jumped to $6.9 million from $4.5 million a year earlier. There are some below-the-line items. Net financial income of $0.6 million, partly from shekel-dollar fluctuations, offset most of the $0.7 million GILTI-related tax charge. Neither item changes the conclusion that operations drove the improvement.
The call reinforced that the momentum is structural rather than lumpy. According to management, Chiesi is seeing accelerated European patient additions following the March 2026 approval of every-four-weeks Elfabrio dosing. Management expects Chiesi sales growth to continue into 2027, with formal 2027 guidance coming alongside annual results. The CFO endorsed the current gross margin as a new baseline as the revenue mix tilts toward higher-margin Chiesi sales. That may be the most consequential comment of the quarter, because it implies the earnings power seen in Q3 is repeatable. Cash and deposits rose to $48.5 million from $40.7 million at the end of Q2, with no debt or warrants.
Guidance is where the messaging gets murky. The press release reaffirmed 2026 guidance of $78 million to $83 million in total revenue and said management expects to "meet or exceed" it. On the call, however, the guide was not explicitly reaffirmed or raised, and management offered only that it expects "a good 2026." The arithmetic makes the range look stale. Nine-month revenue already stands at $75.6 million, including the $25 million Q1 milestone, and product sales of $49.1 million sit close to the implied $53 million to $58 million product guide. Hitting the range requires only a fraction of the Q3 run rate in Q4. Delivery timing to Pfizer and Fiocruz can swing quarters, but declining to lift an evidently conservative outlook leaves upside unquantified.
On the pipeline, PRX-115 remains the long-dated catalyst. New individual-patient Phase 1 data at ACR 2026 showed plasma levels measurable up to 85 days, and the CEO framed a once-every-six-weeks regimen as potentially best-in-class. Top-line Phase 2 RELEASE results are still guided to the second half of 2027. Still, enrollment-completion language shifted from "by year end" last quarter to "hope to finalize next quarter," a modest slip worth monitoring. Bears also have some legitimate ammunition:
- Q3 R&D was $6.9 million, up from $4.4 million in Q2, with a smaller R&D-law grant offset of $1.0 million versus $2.1 million.
- The PRX-119 renal update promised by the end of Q2 has still not been provided.
- The earlier 15-20% Fabry share target was not repeated.
Investor sentiment headed into the report remained positive but weakened noticeably, falling from 0.29 to 0.15. The stock has done little since the last report. At $2.57 on November 9, shares were up 3.2% from the $2.49 post-Q2 open and sat about 5.9% above their 200-day moving average of $2.43. They traded roughly midway through an inter-earnings range defined by a $2.17 low on August 14 and a $2.85 high on September 23, about 9.8% below that high. Price trend and momentum readings are neutral, while AVWAP remains negative. That profile suggests the market had not been pricing in the margin step-up this quarter demonstrated.
The bottom line is that Protalix posted a high-quality operating beat, driven by Elfabrio volume and a gross margin management now calls a baseline, against expectations that had braced for a loss. The fundamental story improved more than sentiment or the share price reflected going in. The open questions are why management did not formally lift a guide it appears poised to clear, and whether RELEASE enrollment closes on the revised timeline.
Read our earnings preview for Protalix BioTherapeutics Inc: https://www.earningswhispers.com/article/PLX/22850
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Sep-22 | |
| Sep-08 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| May-13 | |
| May-13 |
