Aveanna's Raised Outlook Faces Its First Big Test As California Rate Details Arrive
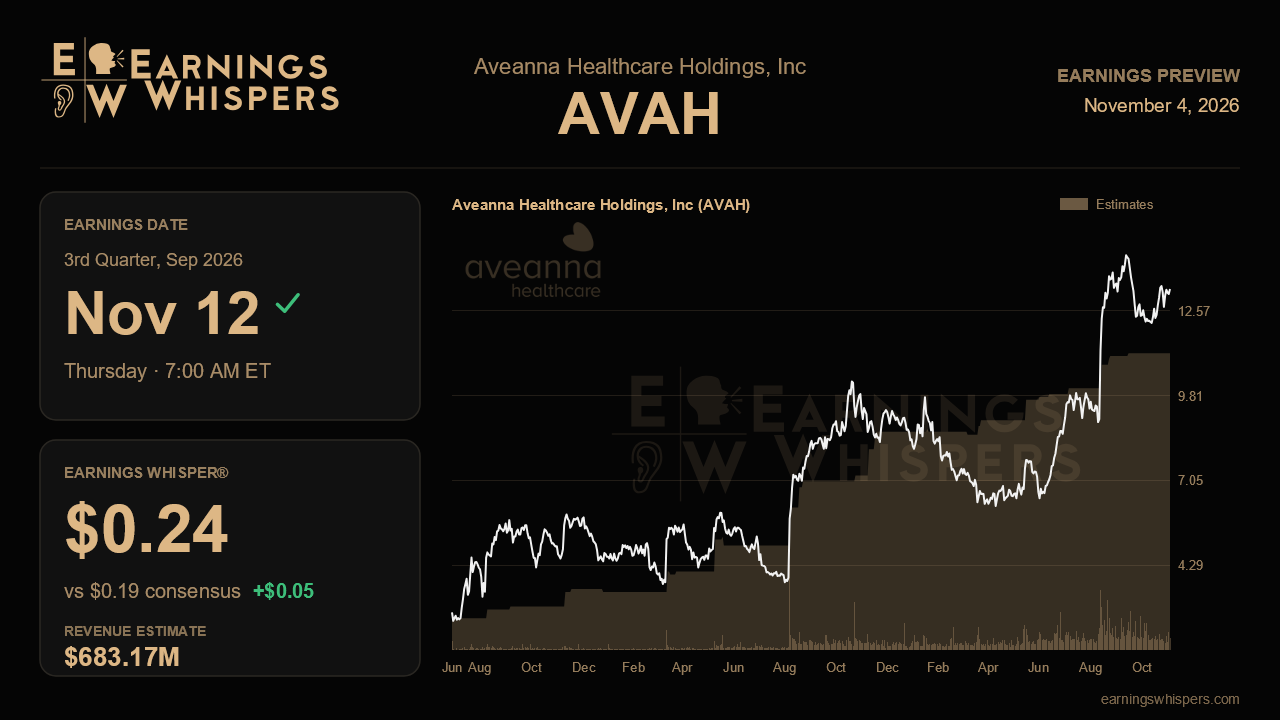
Aveanna Healthcare heads into its third-quarter report with an unusual problem for a home care company: management has been more optimistic than Wall Street. The company has raised its 2026 outlook several times and now expects revenue above $2.68 billion, up from a prior $2.63 billion to $2.65 billion. Full-year consensus still sits near $2.65 billion, below management's stated floor. That gap means the quarter matters less as a beat-or-miss exercise and more as a test of whether the Street has been too cautious about a business that now says it can grow faster for years.
For the September quarter, analysts expect earnings of $0.19 a share on revenue of $683.2 million. That would be a 58% jump in profit from the year-ago $0.12 and revenue growth of about 9.8%. The growth rate looks slower than the 13.7% posted in the second quarter, and the composition is worth unpacking. Family First, the Florida pediatric business acquired in early June with roughly $120 million of annual revenue, should contribute about a full quarter of sales. That leaves implied organic growth closer to the mid-single digits, which looks conservative next to the long-term targets management just raised. The whisper number of $0.24 sits well above consensus, a meaningful gap suggesting that more engaged investors expect another clean beat, helped in part by the roughly $10 million a year in interest savings from the term-loan repricing.
The last call laid out a clear narrative, and this report should show whether it is holding. Management lifted long-term organic growth frameworks for the first time, to 5% to 6% in private duty services and 8% to 10% in home health and hospice. Those numbers need early support. In private duty, the key signals are continued gains in preferred-payer managed care mix, which climbed from 57% to 64% over two quarters, and evidence that the few additional state rate enhancements expected in the third quarter actually landed. In home health, episodic mix reached 81% with episodic volume up 18.5%, and further progress there would back up the higher growth target. The California pediatric nursing rate increase, the first since 2018 and effective January 2027, is the headline catalyst. Medi-Cal was expected to finalize the details in late September, so this call should be the first chance to size the benefit and judge whether pent-up census can be recruited and staffed ahead of the effective date.
There are also places where the story could weaken. Private duty spread per hour has been drifting higher as planned, and management has guided gross margins to stay roughly flat, so any sign that wage pass-through is lagging would undercut the volume-led model. State Medicaid budgets remain a worry as states absorb more costs, even though private duty nursing has so far looked insulated. The unresolved temporary home health rate adjustment is another swing factor for the 2027 outlook. Investors will also want an update on Family First integration and leverage, which rose after the cash-funded deal, along with confirmation that the path below 3x remains on schedule.
The market has already paid for much of this optimism. Shares have gained about 32% since the last report while the S&P 500 slipped nearly 3%, and at $13.28 the stock trades far above its 200-day average of $9.27. It sits roughly 10% below its post-earnings high of $14.71, so it is consolidating rather than pressing a breakout. Bullish sentiment has cooled to about 35% from roughly 53% a quarter ago, which hints that some holders are wary after the run.
The central question is whether Aveanna can show that its stronger organic trajectory is real enough to support another lift toward or above $2.68 billion in revenue and $365 million in adjusted EBITDA, with California offering a credible 2027 bridge. If it can, the gap between management and consensus likely closes in the company's favor. If it cannot, the rally could look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-22 | |
| Aug-27 | |
| Aug-25 | |
| Aug-20 | |
| Aug-20 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Jul-23 | |
| Jun-03 | |
| Jun-02 | |
| May-28 | |
| May-14 |
