DPC Needs A Fivefold Profit Jump On Flat Sales To Steady A Stock Down 39%
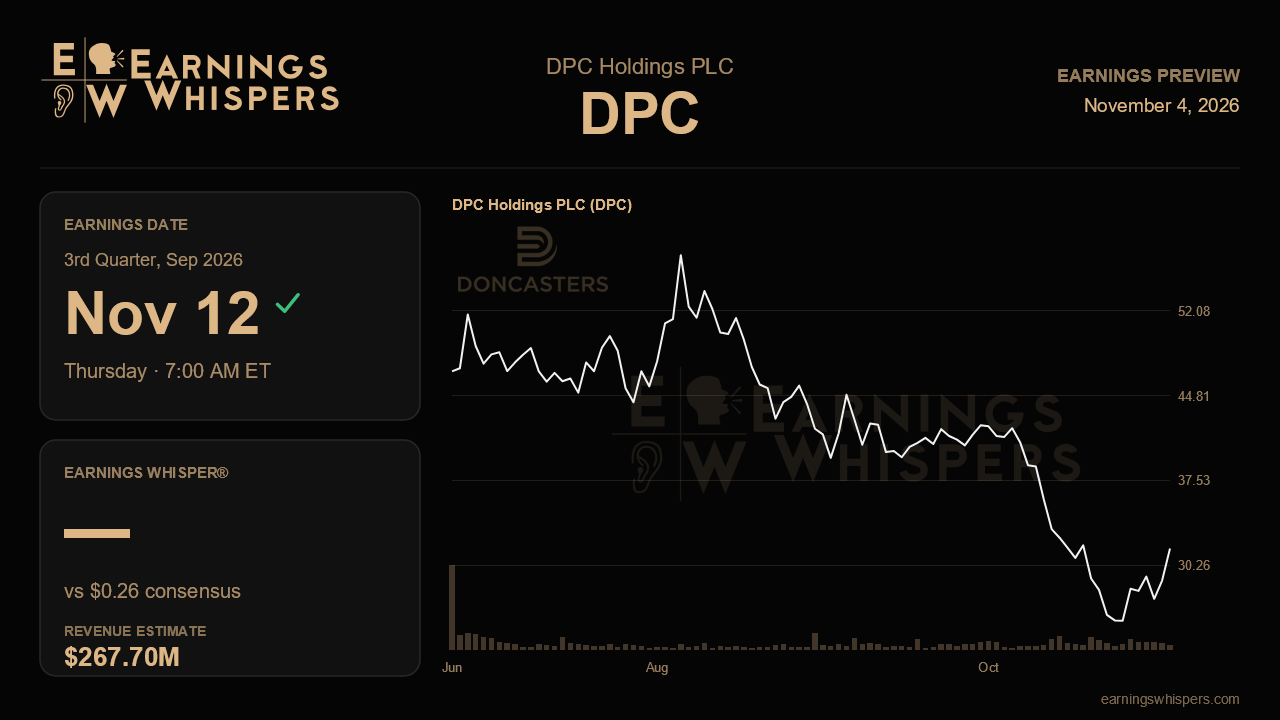
The math behind DPC Holdings' upcoming report is unusually stark. Wall Street expects the precision castings and superalloy maker to earn $0.26 a share for the September quarter, more than five times the $0.05 it posted last time, yet the revenue forecast barely moves. Consensus calls for about $267.7 million in sales, essentially flat with the $268.7 million reported in the prior quarter. In other words, analysts are not betting on a demand surge. They are betting on a dramatic improvement in how much of each dollar of revenue reaches the bottom line, and that is the question the November 12 release, due before the opening bell, has to answer.
That kind of earnings swing on a stable top line usually points to one of a few things: costs that weighed on the prior quarter fading away, better pricing flowing through, a richer mix of higher-value parts, or improved factory efficiency. For a business like Doncasters, which makes complex, highly engineered cast components and nickel- and cobalt-based alloys for aerospace engines and industrial gas turbines, margins are highly sensitive to production yields, scrap rates, raw material costs and how fully plants are loaded. Casting work of this kind carries heavy fixed costs, so small changes in throughput or yield can move profits far more than revenue. The upcoming report needs to show which of these levers is doing the work and whether the improvement looks repeatable rather than a one-off rebound from an unusually weak quarter.
Without explicit company guidance to anchor the forecast, the burden of proof falls on the numbers themselves. A result that lands near $0.26 on revenue in the $268 million neighborhood would validate the idea that the prior quarter's thin profit was an aberration and that the underlying earnings power of the business is considerably higher. A shortfall, especially one paired with flat sales, would raise harder questions about whether margin pressure is structural. Revenue matters here too, but mostly as a check: a sales miss would make the margin recovery harder to achieve, while modest upside could give the Street confidence that aerospace and turbine demand remains a tailwind.
The market has clearly grown skeptical. Shares have fallen 39.1% since the last report, a drop of roughly 36.5 percentage points worse than the S&P 500, which slipped only 2.6% over the same stretch. Sentiment has swung accordingly, moving from a marginally bullish reading heading into the previous report to a decidedly bearish one now. That shift does not predict the outcome, but it does suggest investors are braced for disappointment, and a lower bar can work in a company's favor if results simply meet expectations.
The chart reflects that bruised but stabilizing mood. At $31.70, the stock sits well below its post-earnings high of $57.24 and closer to the $25.00 low, though it has climbed back above its 200-day moving average of about $29.96. That recovery from the lows hints that some buyers see value after the selloff, but the stock remains far from repairing the damage, and a disappointing print could easily send it back toward the bottom of its range.
Ultimately, this report comes down to margins. If DPC can demonstrate that profitability is rebounding sharply on steady revenue, and explain why that improvement should persist, the steep decline in the shares could start to look overdone. If earnings again fall well short of what a roughly $268 million quarter should produce, the market's newfound pessimism will look justified, and the case for a recovery in the company's earnings power will be pushed further into the future.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-20 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jul-20 | |
| Jul-10 |
Airlines and Hyperscalers Clamor for Turbines. Only a Few Companies Make the Parts.
DPC
The Wall Street Journal
|
