DPC Holdings Blows Past Q3 Estimates And Lifts Outlook, But A Tax-Aided Beat And Capex-Heavy 2027 Temper The Story
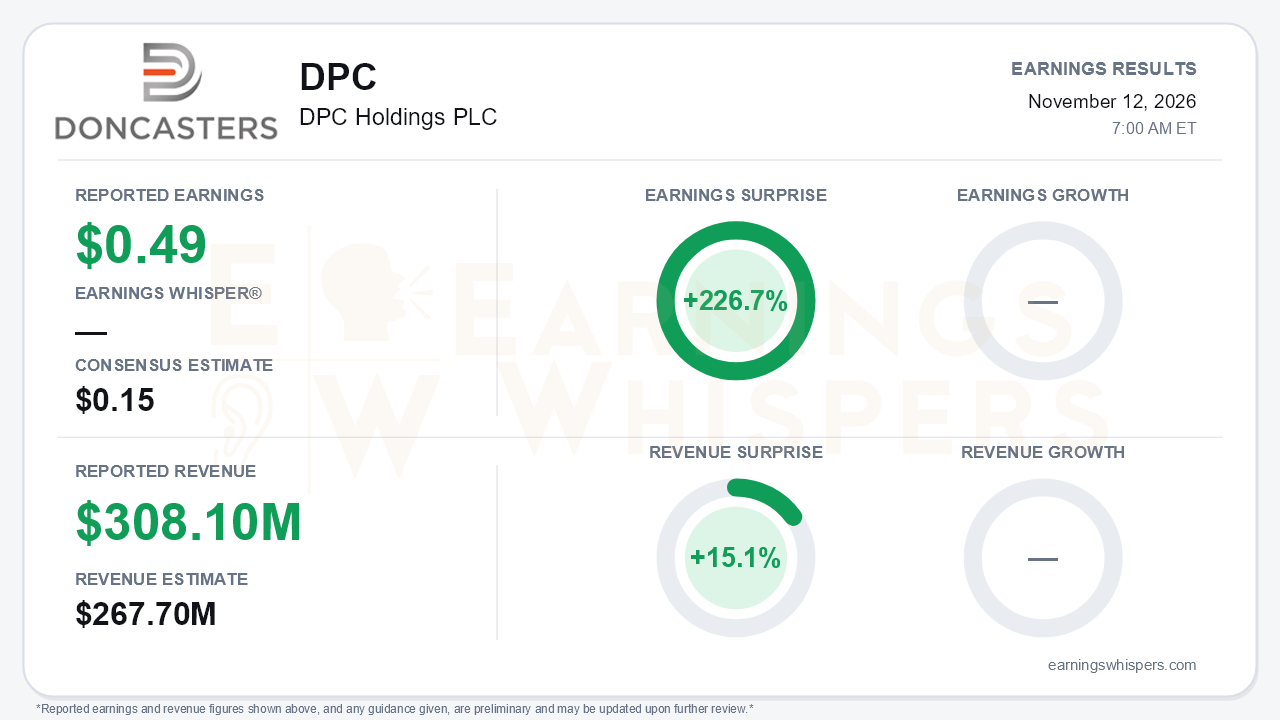
DPC Holdings (Doncasters) delivered a decisive beat in its second quarter as a public company. Adjusted EPS came in at $0.49, against a $0.15 consensus estimate, a 226.7% surprise. Revenue of $308.1 million topped the $267.7 million consensus by 15.1%. The top line also accelerated: revenue grew 39% year over year, up from 34% in the second quarter. Adjusted EBITDA rose 56% to $58.2 million, compared with 33% growth last quarter. Management raised full-year 2026 guidance well above the prior range and introduced a 2027 outlook. On its face, this is the quarter that turnaround skeptics were not positioned for. The quality of the EPS beat, however, deserves scrutiny.
On a GAAP basis, DPC posted net income of $31.8 million, or $0.21 per share, versus a $42.2 million loss a year ago. That swing owes much to a $49.2 million income tax benefit; the company actually recorded a pretax loss of $17.4 million. The adjusted figures strip out share-based compensation, a $17.8 million write-down on the Ivostud disposal group, FX losses and IPO costs. They do not remove that tax benefit, which flows largely into adjusted net income of $72.8 million. Deferred tax assets also jumped to $110.7 million from $44.1 million at year-end. The context matters: management guides 2027 to a normalized tax rate of about 27% and adjusted EPS of $1.00 to $1.10 on roughly 149 million shares. That outlook implies a quarterly run rate well below the $0.49 just reported. Investors should treat the magnitude of the EPS surprise as inflated relative to the operating beat, which was strong but less extreme.
The operating story is genuinely good. Aerospace revenue grew 45%, IGT 43%, and Transportation 21%, the last after being flat in the second quarter. Engine Products segment margin expanded 380 basis points to 23.8%. North America was the standout, with margin up 950 basis points to 23.5% and segment EBITDA up 129%, as new equipment at Groton lifted output and value-based pricing stuck. The blemishes are worth noting. Europe's margin slipped 20 basis points to 23.9%, and metal cost pass-through, chiefly hafnium, diluted group margin by 90 basis points, up from 60 in the second quarter. Turbo Wheels remains a low-margin appendage at 10.2% excluding Ivostud.
Guidance is where the call earned its credibility. Full-year 2026 revenue is now $1.115 billion to $1.13 billion, up from $1.0 billion to $1.04 billion. Adjusted EBITDA guidance rose to $204 million to $207 million, from $182 million to $187 million. For 2027, management guided to revenue of $1.23 billion to $1.33 billion and adjusted EBITDA of $240 million to $260 million, at roughly a 19.5% margin. The fifth strategic partnership, the largest yet, is a minimum 10-year IGT contract. It is expected to add more than $100 million of annual margin-accretive revenue by 2032, with the customer funding about 80% of a capacity build exceeding $200 million in Bochum. That lifts the aggregate partnership target to more than $300 million by 2031, from more than $200 million last quarter. The order book stands near $1 billion, versus $725 million at the end of 2025. Management also bought the remaining outside 50% stake in Montana Precision Products, its joint venture with GE Aerospace's Unison, for about $73 million per the call, and expects it to be accretive within a year.
The trade-off is cash. Reported free cash flow was negative $100.5 million because of the $211.7 million management incentive plan payout. The $111 million adjusted figure benefited from customer prepayments, as deferred revenue rose to $81.9 million. More importantly, 2027 capex is guided to $145 million to $170 million, and free cash flow to a range of negative $20 million to positive $20 million. Management also acknowledged that volumes are approaching capacity limits until new partnership capacity arrives in late 2027. Taken together, the 2027 revenue guide implies growth slowing materially from the current near-40% pace. Bears have legitimate ammunition there.
The market setup is more complicated than the surprise implies. Shares entered the report at $31.68, down 39.1% from the $52.05 open after the August report. The stock had fallen from a $57.24 high on that day to a 52-week low of $25.00 on October 26. It has since rebounded about 27% and sits roughly 4.6% above its 200-day moving average. Investor sentiment slipped from slightly positive to modestly negative, at -0.18, ahead of the print. The AVWAP trend remains negative, consistent with a stock still digesting its post-IPO drawdown.
The bottom line is that Doncasters delivered accelerating growth, real margin expansion and materially higher guidance, backed by an expanding base of customer-funded contracts. The adjusted EPS beat is flattered by a large tax benefit, however, and 2027 trades near-term cash generation and growth pace for capacity. The quarter improves the fundamental case. Whether it repairs a badly damaged chart depends on investors accepting a capex-heavy bridge to 2028.
Read our earnings preview for DPC Holdings PLC: https://www.earningswhispers.com/article/DPC/22870
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 9 hours | |
| Nov-04 | |
| Oct-20 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 |
