CorMedix Faces Its First Post-TDAPA Quarter With Revenue Expected To Halve
CorMedix is about to show investors what DefendCath looks like without its training wheels. The quarter ending in September is the first full period after the TDAPA add-on payment expired on June 30, which moved the catheter lock solution into the standard dialysis bundle. Management spent its last call framing 2026 as a transition year. This report will show whether that transition is orderly or messier than the company's measured tone suggested.
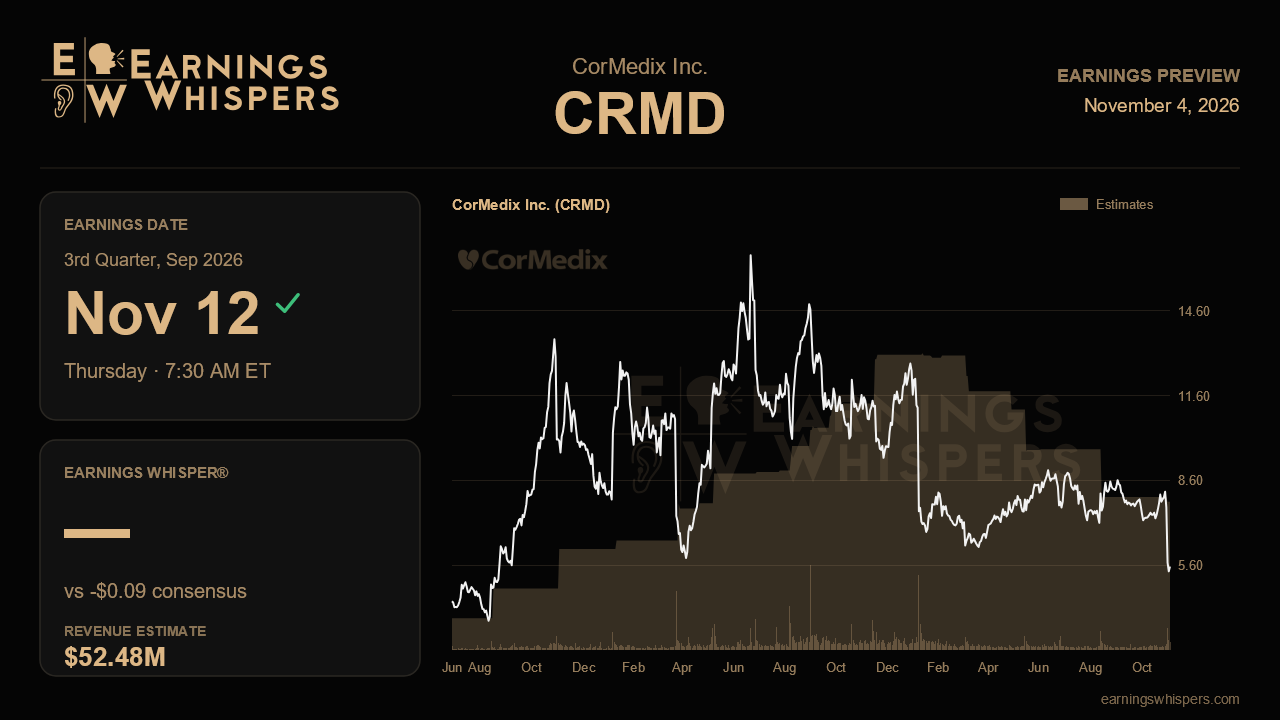
Wall Street is braced for a sharp step down. Consensus calls for a loss of $0.09 per share on revenue of about $52.5 million. That compares with $101.9 million last quarter and $104.3 million a year ago, a decline of roughly half from both periods. Earnings are expected to swing from a $0.57 profit in the year-ago quarter to a loss. None of this should shock anyone who read the guidance closely. CorMedix reaffirmed full-year revenue of $325 million to $345 million, and the Street's $334.7 million sits almost exactly at the midpoint. More telling is the DefendCath outlook of $175 million to $195 million. The product already booked $97.5 million in the first quarter and $66.1 million in the second. That leaves only about $11 million to $31 million for the entire second half. The cliff is built into the guidance. The real question is whether the floor holds.
That floor depends on what management described as stabilized July volumes with the large dialysis operators, offset by attrition among very small accounts. Investors should look for evidence that the contract amendments locking in third- and fourth-quarter pricing actually kept patients on therapy. Any sign that attrition spread beyond the smallest players would challenge the idea that demand is flat rather than eroding. Steady utilization at the big chains, plus early read-outs from the pilot at the newly signed fifth large dialysis organization, would support the case. That pilot covers roughly a couple hundred clinics and completes coverage of all five top U.S. providers, making it the most important new catalyst from last quarter. Commentary on how it is converting toward a 2027 expansion matters more than the current-quarter dollars. Medicare Advantage, flagged for three straight calls without being included in guidance, is another lever that needs concrete progress rather than more patience.
Profitability offers the clearest test of credibility. CorMedix has raised its adjusted EBITDA outlook twice this year, to $125 million to $140 million, and tightened cash operating expenses to $145 million to $155 million on Melinta synergies. With revenue stepping down, holding or nudging that EBITDA range would show the cost discipline is real. A cut would suggest the post-TDAPA squeeze is cutting deeper than planned. On the pipeline, confirmation that Mundipharma filed the Rozeo prophylaxis supplement in the third quarter would keep a first-half 2027 FDA decision on track. Further slippage in the nutrition trial, already pushed to 2028, would add to concerns about execution.
The market has delivered its verdict in advance. Shares have fallen about 34% since the last report, trailing the S&P 500 by roughly 31 points. At $5.56, the stock sits well below its 200-day moving average near $7.65 and just above its post-earnings low of $5.30. Sentiment has flipped from moderately bullish before last quarter to clearly bearish now. That pessimism lowers the bar somewhat, but it also means a weak trough signal could push the stock through support.
Ultimately, this report hinges on one question. Is the third quarter a trough that holds at the major dialysis chains, or the start of a slide? If CorMedix shows stable volumes at the large operators, an intact EBITDA outlook and visible momentum at the new customer, the 2027 recovery story survives. If not, the transition year could start to look like something longer.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-19 | |
| Oct-15 | |
| Sep-01 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Jul-29 | |
| Jun-08 | |
| May-15 | |
| May-14 |
