CorMedix Beats A Lowered Bar As The DefenCath Cliff Arrives, And Heron Becomes The New Growth Story
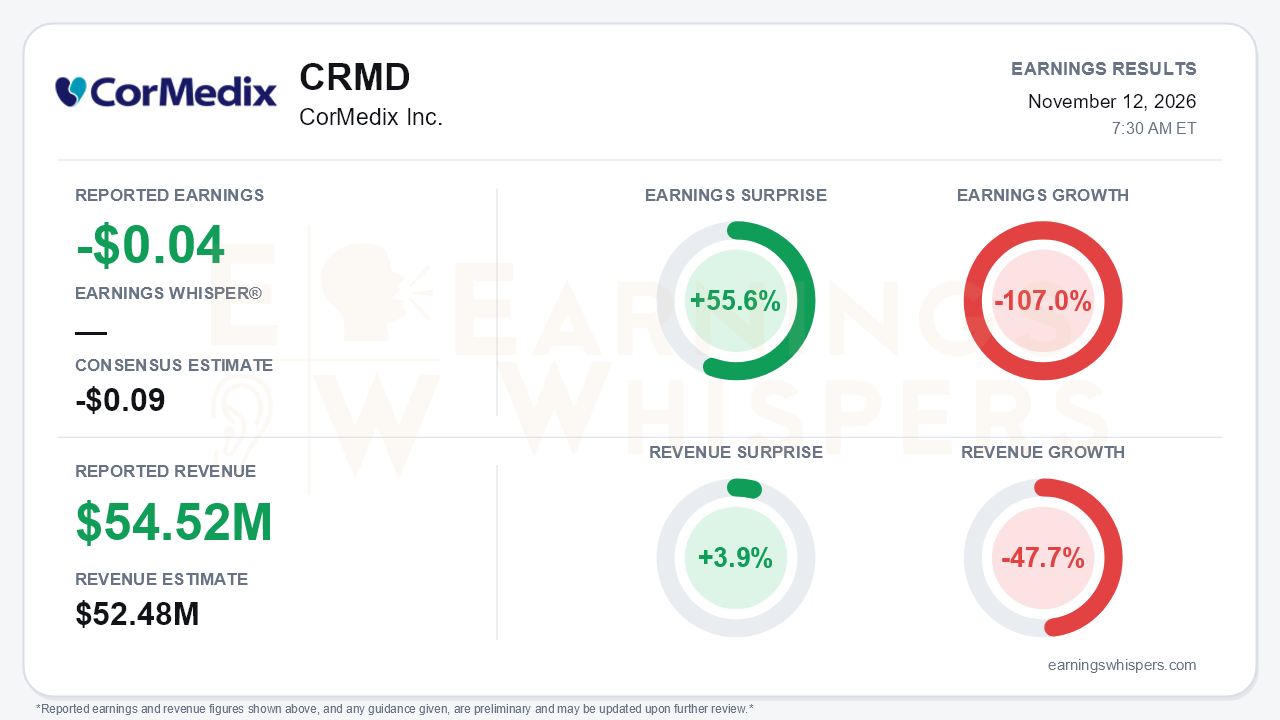
CorMedix cleared expectations in the quarter where its DefenCath revenue cliff finally hit the income statement. Earnings Whispers recorded a loss of $0.04 per share against a consensus loss of $0.09, a 55.6% surprise. Revenue was $54.52 million, 3.9% above the $52.48 million consensus. The company cited a lower $51.2 million Street figure, which would make the beat look larger. The year-over-year comparisons show the damage: earnings fell 107.0% and revenue dropped 47.7%. The company swung from $108.6 million of GAAP net income a year ago, a period that included a $59.7 million one-time tax benefit, to a $14.7 million GAAP loss, or $(0.19) per share. The central tension is that management is asking investors to trade a collapsing legacy franchise for an acquisition-led diversification story, while visibility into 2027 DefenCath economics has actually gotten worse.
The quality of the beat deserves scrutiny.
- **GAAP versus normalized loss.** The gap between the normalized $0.04 loss and the GAAP $0.19 loss is mostly an $11.5 million non-cash remeasurement of Melinta contingent consideration.
- **A one-time boost to DefenCath.** DefenCath sales of $17.2 million included a $5.0 million favorable change in sales-allowance estimates. That puts the underlying run rate near $12 million a quarter, compared with $66.1 million in Q2 and $97.5 million in Q1.
- **The sequential slide.** Consolidated revenue fell from $127.4 million in Q1 to $101.9 million in Q2 to $54.5 million in Q3.
- **EBITDA collapse.** Adjusted EBITDA, which excludes the allowance benefit, dropped to $3.1 million from $58.7 million in Q2.
- **Margin squeeze.** Gross profit was pressured further by $10.3 million of intangible amortization and higher cost of sales from the Melinta portfolio.
The remaining portfolio, at $37.3 million including grant income, is now the larger revenue base.
Guidance offers some offsetting reassurance:
- **Revenue.** Full-year 2026 revenue guidance of $325-$345 million was reaffirmed.
- **Adjusted EBITDA.** The range was narrowed to $130-$140 million from $125-$140 million, the third consecutive upward adjustment.
- **Cash operating expenses.** Guidance was cut to $140-$145 million from $145-$155 million.
That guidance is less bullish than it sounds. Nine-month adjusted EBITDA already stands at $131.9 million, so the range implies roughly breakeven-to-modest EBITDA in Q4. Balance-sheet strength is real: cash rose to $355.2 million from $256.7 million at Q2, helped by $218.3 million of nine-month operating cash flow as receivables from the TDAPA era were collected.
On the call, management pivoted hard toward 2027 catalysts.
- **Heron acquisition.** The Heron asset purchase brings Zynrelef, Aponvie, Cinvanti and Sustol, with about $150 million of trailing revenue. Management expects a $125-$150 million contribution in 2027, $45-$60 million of run-rate cost synergies by the end of 2027, and immediate accretion to earnings and free cash flow. The company says the deal effectively doubles non-DefenCath product revenue.
- **REZZAYO.** The prophylaxis sNDA received Priority Review, with FDA action expected in Q1 2027 and promotion planned for the second half of 2027.
- **CMS add-on.** The 2027 final rule set the Q1 post-TDAPA add-on at $8.32, well above the current $2.37. Management expects every 2027 quarter to exceed today's rate, with the full-year average at least about twice the current level.
Bears have legitimate ammunition, however.
- **2027 DefenCath guidance withdrawn.** CMS adopted a quarterly reset methodology, so the 2027 average add-on will fall below $8.32 and decline from Q1 to Q2. Management suspended its prior $100-$125 million 2027 DefenCath guidance rather than reaffirm it.
- **Commercial traction.** Medicare Advantage contracting remains unsigned. The new large dialysis organization pilot produced no repeat orders.
- **TPN Phase 3.** Enrollment is still meaningfully behind, and alternative regulatory pathways are now under evaluation.
- **Heron deal risks.** The transaction needs Heron stockholder and regulatory approval. Cinvanti faces litigation and a potential at-risk competing launch.
- **Funding and dilution.** The deal adds leverage through a $75 million initial draw on a Pharmakon term loan and involves issuing shares to Heron.
The market got ahead of much of this. Investor sentiment swung sharply, from a modestly positive 0.23 after the prior report to a clearly negative -0.41. That is a meaningful deterioration rather than a drift. Shares entered the report at $5.30, down 36.8% from the $8.39 open after the August release. That leaves them roughly 30% below the $7.60 200-day moving average and 41% off the inter-earnings high of $8.98 set the day of that report. The stock set a 52-week low of $5.10 on November 6, just days before this release, and sits only about 4% above it. The Earnings Whispers price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral.
That positioning cuts both ways. A stock pressed against its lows with deeply negative sentiment has already discounted the DefenCath reset. It has not necessarily discounted the removal of 2027 DefenCath guidance or the execution burden of absorbing a third major portfolio in roughly 18 months.
The bottom line is that CorMedix delivered a clean beat on a deliberately lowered bar, but the quarter confirmed that DefenCath is now a roughly $12 million-a-quarter product with uncertain 2027 pricing. The investment case has shifted from a high-margin single-asset story to a leveraged, acquisition-driven institutional portfolio built around Heron, REZZAYO and a strong cash position. Until Heron closes, Medicare Advantage is signed and 2027 guidance is restored, the burden of proof sits with management.
Read our earnings preview for CorMedix Inc.: https://www.earningswhispers.com/article/CRMD/22869
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| 7 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-19 | |
| Oct-15 | |
| Sep-01 | |
| Aug-13 | |
| Aug-13 |
