Hudbay Needs Record Sales And A Copper World Cost Number To Back Its Rebound
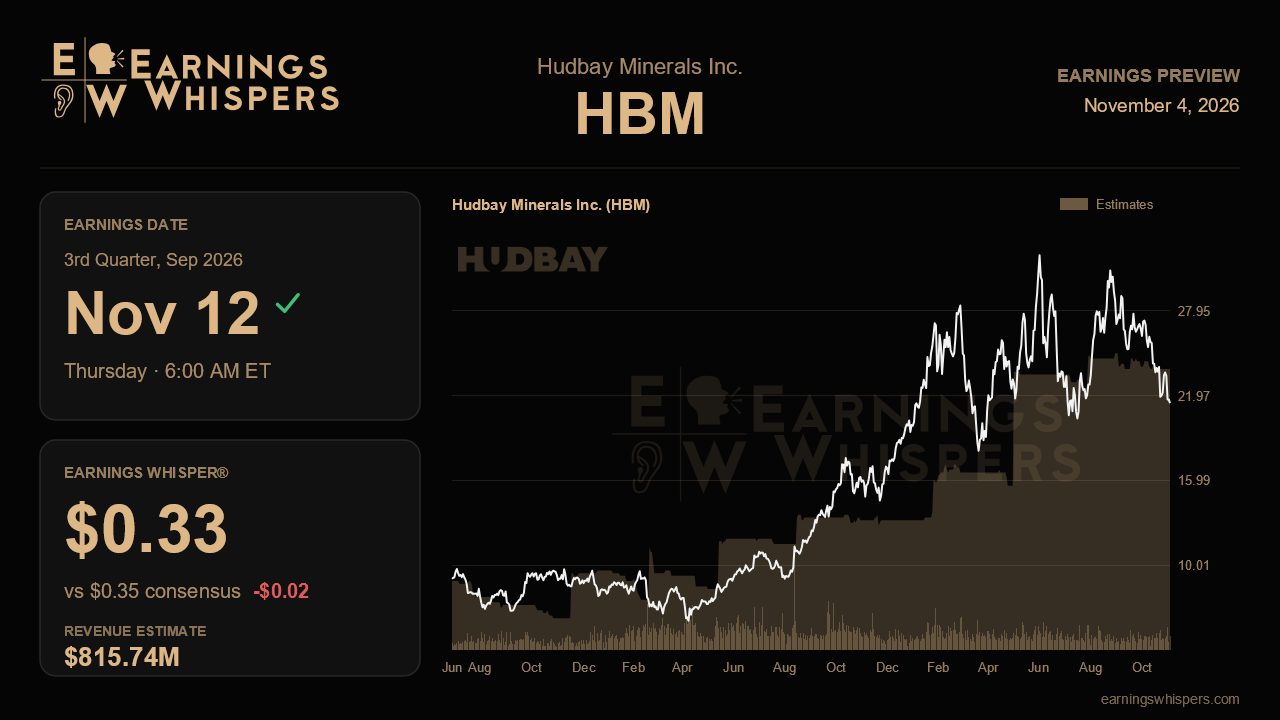
Hudbay Minerals heads into its third-quarter report with the Street expecting something close to a record quarter, even though the stock trades as if investors are bracing for disappointment. Analysts are looking for earnings of $0.35 a share on revenue of $815.7 million. That would top the company's prior high-water mark of $757 million in the first quarter and represent a sharp rebound from the $631.3 million posted last quarter, when grade sequencing and the depletion of high-grade Pampacancha ore pulled results lower. Against a weak year-ago quarter of $0.03 a share and $346.8 million in sales, the projected gains of more than 1,000% in earnings and 135% in revenue look spectacular. Much of that reflects an easy comparison, but the sequential step-up is the more demanding test.
Getting there likely depends on volumes that slipped out of the second quarter. Ocean swells at Peruvian ports forced roughly 10,000 tonnes of concentrate sales to be deferred last quarter, a recurring problem that also hit the year-ago period. If those tonnes shipped in the third quarter, revenue should benefit from a catch-up. If weather disrupted loadings again, the revenue estimate could prove too ambitious, and the deferral issue would start to look less like bad luck and more like a structural drag on Peru's cash conversion. The Earnings Whisper of $0.33, a touch below consensus, suggests some traders are hedging against exactly that kind of timing slippage, though the gap is small.
Costs are where management has built the most credibility. Consolidated cash costs were running near negative $1 per pound through midyear, far better than the original negative 10 to negative 30 cent range, helped by gold byproduct credits that made up 38% of gross revenue last quarter. A result that holds near that level would confirm that the improved cost guidance was durable rather than a one-quarter quirk of gold grades. Any meaningful reversal would raise questions, since margins have been the core of the bullish case and the reason the balance sheet swung to $80 million of net cash.
Operationally, the quarter should show whether last spring's hiccups were truly transient. Copper Mountain lost its primary SAG mill for about a month and saw recoveries suffer from ball-mill grinding constraints, while Lalor dealt with labor shortages and a hoist gearbox failure. Management said those issues were resolved, so clean throughput and recovery numbers from British Columbia and Manitoba would validate that claim. In Peru, the commissioning of Constancia's pebble crushers, scheduled for the third quarter under a newly expanded 34 million tonne per year milling permit, offers an early read on the next leg of throughput growth.
The growth pipeline may matter more to the stock than the quarter itself. The Copper World feasibility study was pushed to early in the fourth quarter, and management has already conceded that capital costs will exceed the 2023 estimate of $1.3 billion while insisting it is no blowout. With a final investment decision targeted for late 2026, any update on that number, plus early integration progress at the newly acquired Cactus project, will shape how investors value the path to roughly 150,000 tonnes of copper in 2027.
Sentiment has warmed considerably, with bullish readings jumping to 57.7% from 18.3% ahead of the last report. The share price tells a more cautious story. Hudbay is up only 2.2% since its last release, roughly in line with the S&P 500, and at $21.44 it sits well below its 200-day moving average of $24.82 and near the bottom of a post-earnings range that stretched from $20.66 to $30.82. That gap between upbeat sentiment and a sagging chart leaves room for a relief move if results deliver. The central question is whether Hudbay can turn deferred tonnes and low costs into the record revenue the Street expects while putting a credible, contained price tag on Copper World.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-01 | |
| Oct-01 | |
| Sep-28 | |
| Sep-17 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 | |
| Aug-28 |
