Hudbay Minerals Clears The Whisper As Copper World Moves To Construction, But A Revenue Miss And Cost Creep Keep The Stock Well Below Its Summer High
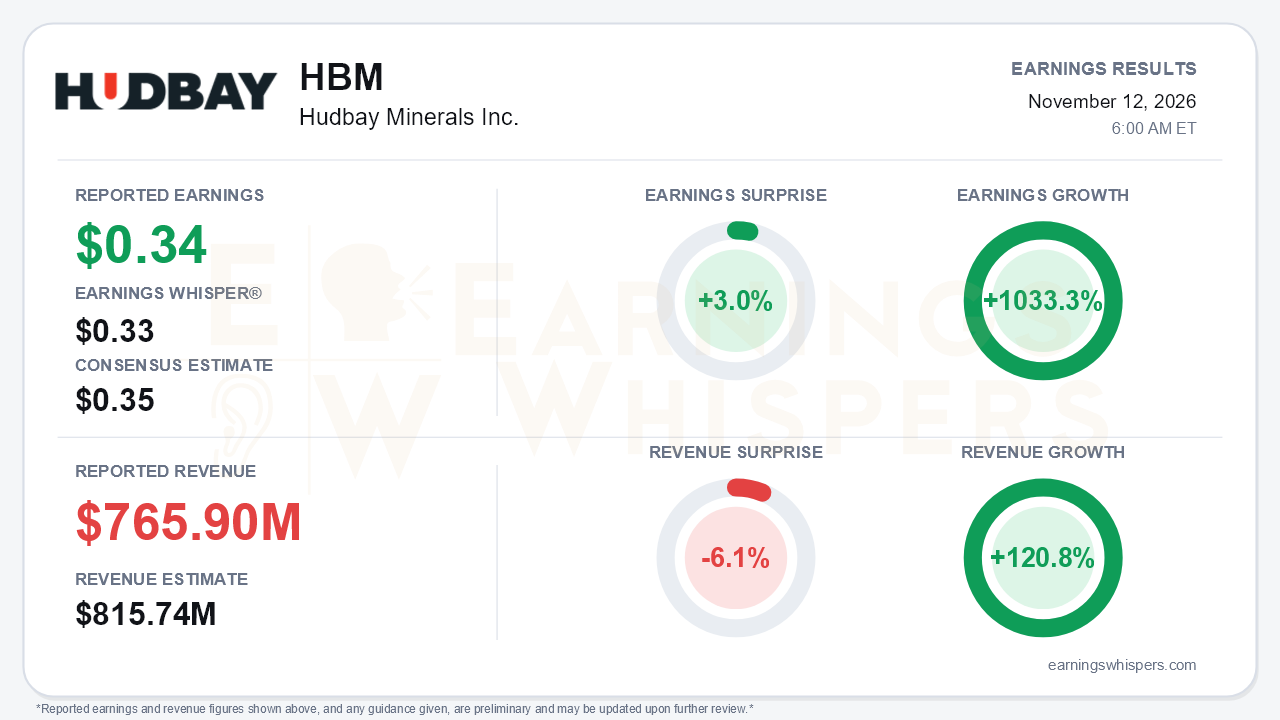
Hudbay Minerals delivered a third quarter that was record-setting in absolute terms and still left some investors wanting more. Adjusted earnings of $0.34 per share topped the $0.33 Earnings Whisper by 3.0% but came in a penny below the $0.35 consensus. Revenue reached a record $765.9 million, up 120.8% year over year, yet missed the $815.74 million consensus by 6.1%. Earnings grew 1033.3% from the depressed $0.03 adjusted result a year ago, when Manitoba and Peru were recovering from temporary suspensions. The central tension is that operations and the strategic story clearly improved, while the top line, some cost lines, and the cash balance were less clean than the headline records suggest.
The sequential picture shows a business re-accelerating after a soft second quarter. Revenue rose from $631.3 million in Q2, adjusted EBITDA climbed 29% to $413.4 million, and adjusted EPS improved from $0.28. Copper production rose 7% to 30,152 tonnes and gold jumped 36% to 69,513 ounces. Copper sales of 30,223 tonnes outpaced Q2's 23,780 as shipments caught up. The quality of the quarter still deserves scrutiny on three counts:
- **EBITDA was not a new high.** Adjusted EBITDA remained slightly below the $421.9 million posted in Q1.
- **GAAP EPS was flat.** It held at $0.34 versus Q2 even as net earnings rose, because the weighted share count increased to 444.1 million from 400.4 million.
- **Reported cash flow fell.** Cash from operations dropped to $214.9 million on a $99 million working-capital drag. The $201.9 million in free cash flow management highlighted is a non-GAAP figure that excludes working-capital changes.
The operating narrative was the strongest part of the release. Constancia set a throughput record of roughly 91,300 tonnes per day, and a third rougher line commissioned in September is expected to lift copper recoveries starting in Q4. Manitoba gold cash costs fell 48% sequentially to $403 per ounce, aided by record New Britannia throughput and record Stall recoveries. Copper Mountain posted its first free-cash-flow-positive quarter under Hudbay ownership.
Those gains supported a second improvement to full-year consolidated cash cost guidance, now -$0.55 to -$0.35 per pound, versus an original range of -$0.30 to -$0.10. Sustaining cash cost guidance moved to $1.40-$1.80 from $1.70-$2.10, and sustaining capex is tracking $35 million under plan. On the call, management framed 2027 copper growth at more than 25%. It also expects British Columbia copper output to roughly double next year.
Beneath that improvement, the cost picture is uneven. Peru cash costs jumped to $2.23 per pound from $1.66 in Q2 and $0.70 in Q1, above the $1.70-$2.10 annual range. The drivers were thinner gold and silver by-product credits after Pampacancha's depletion, plus higher fuel and profit sharing. British Columbia's $3.09 per pound remains above its range, and full-year costs there are expected near the high end. Copper Mountain hit 43,500 tonnes per day in September but is not yet sustaining the 50,000 target, which has drifted toward a year-end exit, and its higher grades are now a second-half 2027 event.
The defining catalyst is the Copper World final investment decision with Mitsubishi. First production is targeted for the second half of 2029, with about 102,000 tonnes of annual copper over the first decade. Base-case economics show a 17% IRR at $5 copper, rising to a 32% levered IRR to Hudbay. The funding structure is the real accomplishment:
- Mitsubishi's $600 million equity investment.
- A $230 million Wheaton stream deposit.
- Roughly $650 million in project debt.
Together these hold Hudbay's share near $500 million and defer it to 2028. A revolver upsized to $700 million lifts pro forma liquidity to about $1.2 billion.
Bears still have legitimate ammunition. Initial capital of about $2.07 billion compares with roughly $1.3 billion in the 2023 study, including about $200 million of scope changes, though management had flagged the increase earlier in the year. Net cash shrank to essentially zero from $80.5 million in Q2. Reported cash also includes $290.1 million held by Copper World LLC that is restricted to the project. Other open items include the New Ingerbelle judicial review, with a hearing expected in Q1 2027, delayed Peruvian satellite permits, and Arizona groundwater politics.
Investor sentiment improved meaningfully, rising from 0.18 to 0.51, consistent with a call that was more confident and carried more concrete milestones than recent quarters. The tape tells a more cautious story. Shares are up 4.6% since the open after the July report, but they sit 28.8% below the $30.82 inter-earnings high set in late August. They are also 11.3% under the 200-day moving average and less than 10% above the $19.99 low reached on November 5. Price and AVWAP trend readings remain negative even as sequential growth reads positive. The market has given back the summer enthusiasm while fundamentals kept building.
The bottom line is that Hudbay's quarter was stronger operationally and strategically than its revenue miss and penny-short consensus comparison imply. It brought record production-driven results, twice-improved cost guidance, and a well-financed Copper World sanction. The open questions now shift to execution: reining in Peru and British Columbia costs, getting Copper Mountain to sustained nameplate, and keeping Copper World's already-higher budget from creeping further. Rising sentiment suggests investors are warming to that story, but a stock still well below its 200-day average shows the market wants delivery, not just milestones.
Read our earnings preview for Hudbay Minerals Inc.: https://www.earningswhispers.com/article/HBM/22879
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-06 | |
| Nov-04 | |
| Nov-04 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-01 | |
| Oct-01 | |
| Sep-28 |
