Edgewell Needs A Strong Fiscal Fourth Quarter To Prove Its Organic Growth Turn Holds
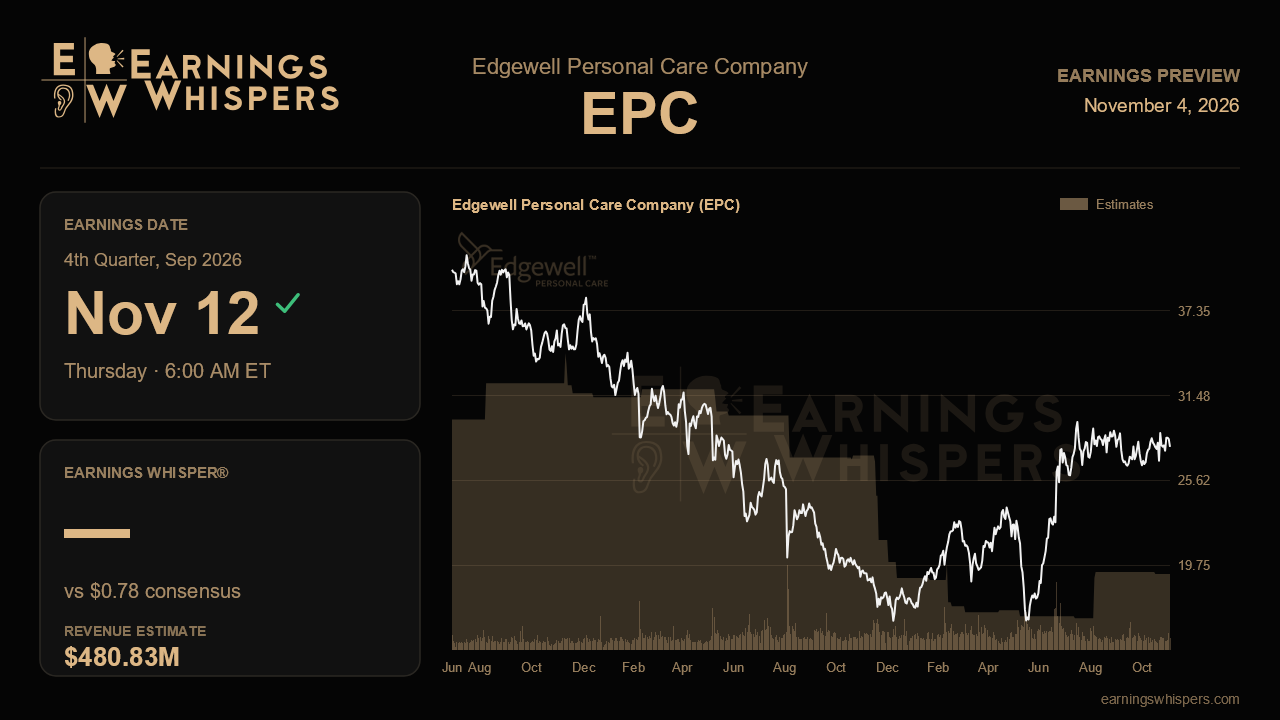
Edgewell Personal Care finally delivered the organic growth it had been promising for most of the year, then trimmed its full-year outlook in the same breath. That mix of better demand and thinner margins sets up the fiscal fourth-quarter report, due before the open on November 12. It is the first real test of whether the third-quarter inflection was a turning point or a single good quarter.
Wall Street expects adjusted earnings of $0.78 per share, up about 15% from $0.68 a year ago, on revenue of roughly $480.8 million. The revenue figure is about 10.5% below last year's $537.2 million and well under the $570.1 million posted last quarter. The headline decline looks alarming, but it sits awkwardly next to management's claim of returning organic growth. The gap points to portfolio reshaping, including the feminine care changes that reset the original guidance, rather than collapsing demand. The more meaningful number is earnings, where the Street expects real growth on a smaller sales base.
The guidance math matters here. Management narrowed fiscal 2026 adjusted EPS to $1.80 to $2.00, from $1.70 to $2.10. That range is already well below the $2.15 to $2.55 it floated before the feminine care move. Consensus for the year sits at $1.94, in the upper half of that range and above the midpoint. Analysts are effectively betting that the cost headwinds management flagged will not erode the fourth quarter. Full-year organic sales guidance of flat to up 0.5% carries its own implication. The first half was negative, with declines of 0.5% and 2.4%, and the third quarter was only modestly positive. So the closing quarter needs to show solid organic growth just to land inside the range.
The call laid out clear markers. Branded wet shave returned to roughly 1% growth after persistent declines. Another positive print would suggest the new Schick campaign and Billy's momentum are holding up in a promotional razor market. Sun and skincare grew 5%, helped by Hawaiian Tropic climbing to the number four brand, while Banana Boat lost share ahead of next year's packaging restage. International is the swing factor. Organic sales there fell 1.4%, with a private label supply disruption in Europe and Latin America costing roughly 350 to 400 basis points. Management called that transitory and said July had already recovered. A clean rebound would validate that view, while lingering weakness would raise doubts about how temporary the problem really was. Gross margin deserves equal scrutiny. Third-quarter adjusted operating margin slid to 9.3% from 11.3% a year earlier on oil-linked commodity inflation. Management also promised year-over-year gross margin expansion in fiscal 2027, so the starting point for that promise will be closely examined.
The market has not given much credit for the growth turn. Shares have slipped 4.5% since the last report, trailing the S&P 500 by about 1.7 percentage points. Sentiment has cooled to 9.1% bullish from 13.3% heading into the prior quarter. Still, the stock trades near $27.93, comfortably above its 200-day moving average of $23.98 and in the upper half of its post-earnings range of $25.90 to $29.95. The prior quarter's swing from below $16 to nearly $30 reflects a stock re-rated around a rejected takeover offer and an improving story. That re-rating also leaves less room for a stumble.
The central question is whether Edgewell can show that organic growth is durable while holding margins against inflation. A quarter with positive branded shave trends, a recovering international business and earnings near consensus would support management's message that it enters fiscal 2027 from strength. Initial fiscal 2027 guidance that backs up the margin-expansion promise would add to that case. Another round of cost-driven margin slippage would suggest the demand recovery is not yet translating into profit.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-15 | |
| Oct-05 | |
| Oct-02 | |
| Sep-14 | |
| Sep-09 | |
| Sep-02 | |
| Aug-20 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-09 | |
| Jun-30 |
