Edgewell Matches On EPS As Q4 Rebound Collides With A Back-Loaded, Cash-Light Fiscal 2027 Outlook
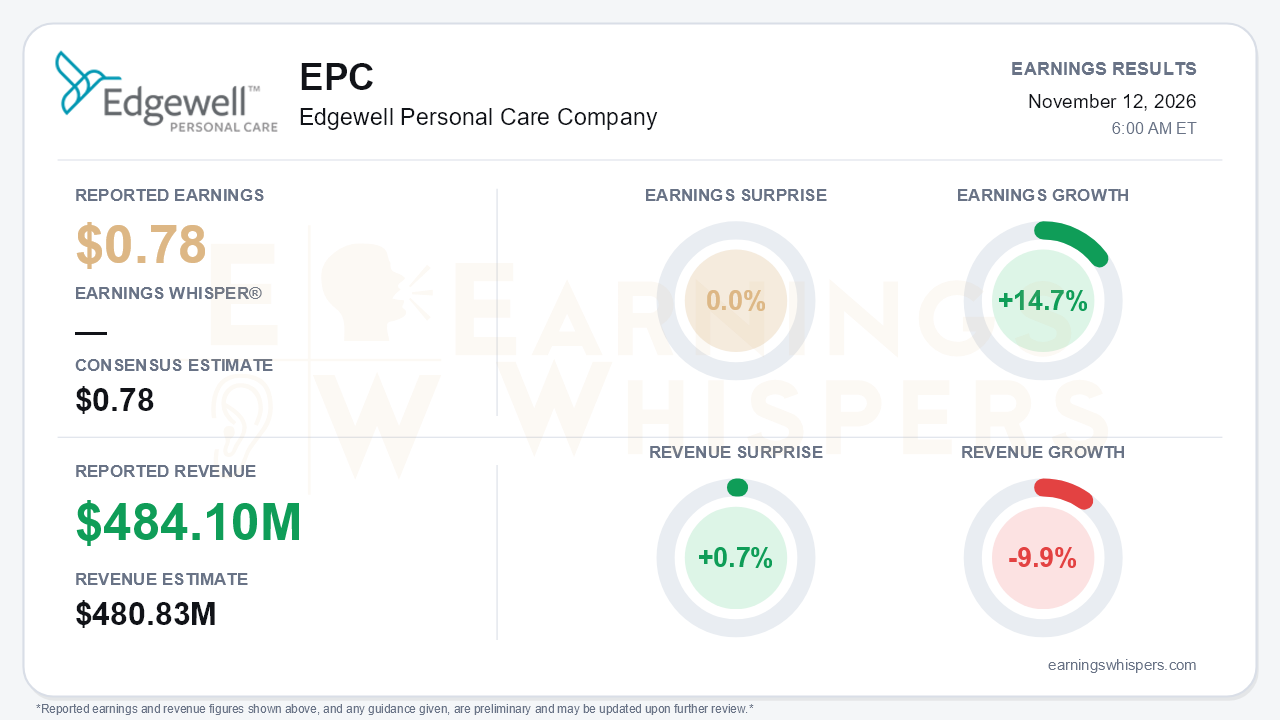
Edgewell Personal Care delivered fiscal fourth-quarter adjusted earnings of $0.78 per share, exactly matching the consensus estimate. Revenue of $484.1 million topped expectations by 0.7%. On Earnings Whispers' normalized basis, earnings grew 14.7% year over year while revenue fell 9.9%. The company's own presentation reads more favorably: adjusted EPS rose from $0.52, and net sales grew 3.0%, with organic sales up 3.1%. The gap reflects the comparison base. The release recasts the prior year as continuing operations, excluding the divested Feminine Care business, so the company's figures are like-for-like on the remaining portfolio. Either way, the central takeaway is the same. The quarter confirmed a genuine operational reacceleration, but management's fiscal 2027 outlook asks investors to wait until the back half of the year for that momentum to show up in earnings and cash.
The quality of the quarter was better than an in-line print suggests. Organic sales improved steadily through the year:
- Q1: down 0.5%
- Q2: down 2.4%
- Q3: a return to growth
- Q4: up 3.1%
Both North America (+3.3%) and International (+3.0%) contributed. Adjusted gross margin jumped 510 basis points to 45.7%, after year-over-year declines in each of the first three quarters. That gain drove adjusted operating margin to 10.6% from 5.9%, even as advertising and promotion spending climbed to 11.6% of sales. Sun and Skin Care segment profit nearly quadrupled on strong global Grooming. Branded Wet Shave growth more than offset private-label supply constraints.
The headline still flatters somewhat. About $0.11 of the quarter's EPS came from favorable currency; on a constant-currency basis, adjusted EPS was $0.67. Another $7.2 million of transition services income from the Feminine Care buyer ran through other income. On a GAAP basis, continuing-operations EPS slipped to $0.23 from $0.26, weighed down by $29.9 million of restructuring costs.
The full-year picture is weaker than the fourth quarter:
- Organic sales rose just 0.3%.
- Wet Shave organic segment profit fell 17.9%.
- Adjusted gross margin ended roughly flat, after management had guided to a 60-basis-point gain at the start of the year.
- Adjusted operating margin fell about 70 basis points, worse than the 50-basis-point decline originally guided.
- Operating cash flow dropped to $49.6 million from $118.4 million, which the company largely attributed to one-time costs tied to the divestiture.
On the conference call, management's tone was clearly more confident than earlier in the year. Executives cited:
- broad distribution gains;
- U.S. branded wet shave unit share gains in all 12 months of the fiscal year;
- Walmart returning to growth;
- Cremo up 50%, its eighth straight quarter above 20% growth.
The fiscal 2027 guide calls for organic growth of 1% to 3% across all segments and both regions. It also projects roughly 70 basis points of operating-margin expansion, built on 60 basis points of gross-margin improvement and 90 basis points of SG&A leverage, partly reinvested in A&P rising toward 13% of sales. Planned catalysts include:
- a Banana Boat relaunch aimed at stopping share losses;
- what management called the biggest Billie innovation since the acquisition, launching at spring resets;
- an expected return to growth in private-label shave in the second half.
Bears have legitimate ammunition. The consolidation of North American wet shave operations slipped about six months, pushing its savings out of fiscal 2027 and into fiscal 2028. Adjusted free cash flow guidance of $100 to $120 million falls well short of the $150 million-plus marker floated earlier in the year. Energy-driven inflation of roughly 300 basis points is expected, and Q4 gross margin already landed slightly below plan on diesel and freight. Below-the-line items also weigh on 2027:
- Expiring transition services income costs about $0.17 per share.
- A higher tax rate costs about $0.03.
As a result, the $1.85 to $2.15 adjusted EPS range implies only modest growth at the midpoint, despite roughly 10% operating-profit growth. Phasing adds risk. First-quarter organic sales are guided flat to down 1%, first-quarter EPS is expected below the prior year, and about 80% of the year's EPS is weighted to the second half.
The market setup is more complicated than the in-line print implies. Investor sentiment weakened into the report, sliding from mildly positive to essentially neutral, so expectations were already cooling. Yet shares held up. At $29.15 the stock was essentially unchanged since the open after the August report. It sat about 20% above its 200-day moving average and roughly 4% below the 52-week high of $30.36 set on November 5. With the stock near the top of its range on improving fundamentals, a guide that defers much of the payoff could test investors' patience, particularly through a soft first quarter.
The bottom line is that Edgewell's fourth quarter showed the turnaround is real at the operating level, with organic growth and gross margin both inflecting sharply. However, the fiscal 2027 outlook pairs that momentum with delayed savings, lighter cash generation, energy inflation and a back-loaded earnings calendar. That leaves execution in the second half as the swing factor for a stock that has already priced in much of the recovery.
Read our earnings preview for Edgewell Personal Care Company: https://www.earningswhispers.com/article/EPC/22872
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| Nov-09 | |
| Nov-04 | |
| Nov-03 | |
| Oct-15 | |
| Oct-05 | |
| Oct-02 | |
| Sep-14 | |
| Sep-09 | |
| Sep-02 | |
| Aug-20 | |
| Aug-06 |
