AdvanSix Grows Sales 15% On Pricing, But Profit Squeeze And Slipping 2026 Targets Define The Quarter
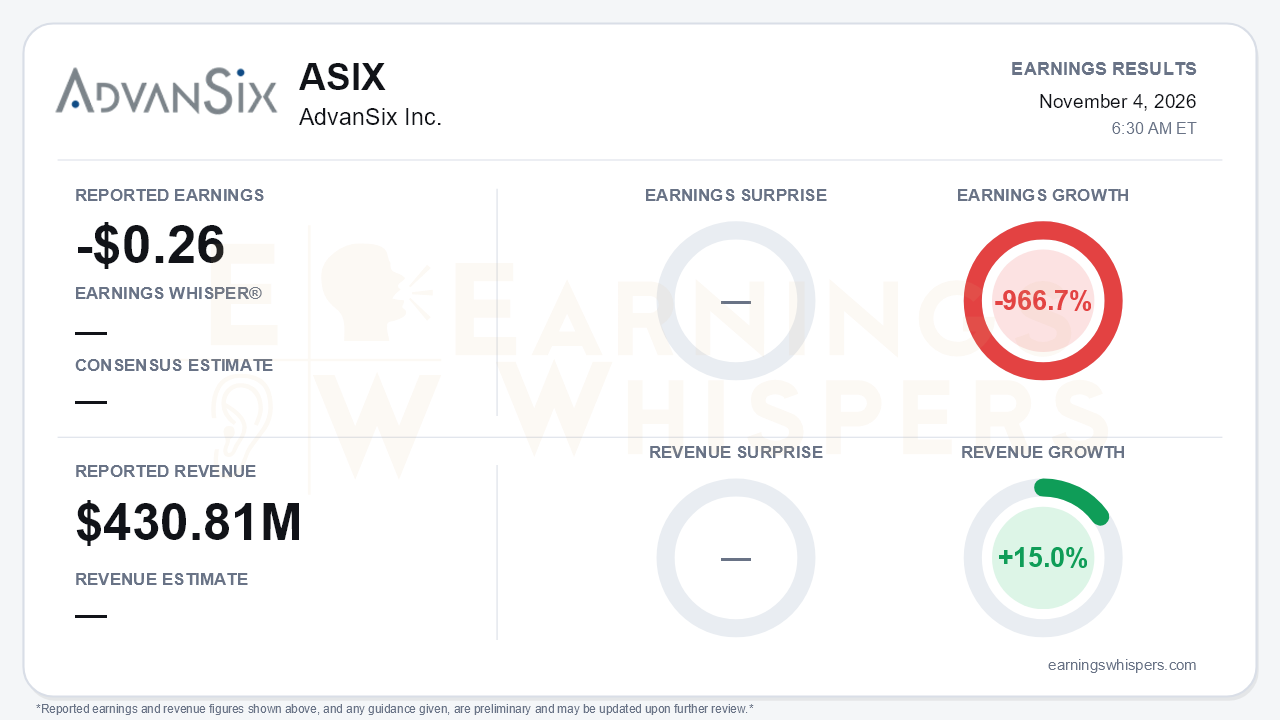
AdvanSix posted its strongest top-line growth in more than a year, and it did not translate into profit. Third-quarter revenue rose 15.0% year over year to $430.81 million, accelerating from 3% growth in the second quarter and 7% in the first. Earnings Whispers recorded a loss of $0.26 per share, an earnings decline of 966.7% from the year-ago quarter. The company's own figures differ: a GAAP loss of $0.28 per share and an adjusted loss of $0.24, compared with an adjusted profit of $0.08 a year earlier and $0.19 in the second quarter. Every version points the same way. A company that was profitable on an adjusted basis last year and last quarter swung back to a loss. That is the central tension: revenue is accelerating because prices are rising, not because the business is earning more.
The composition of sales growth explains why the beat on the top line deserves scrutiny. Pricing contributed 17 points, while volume fell 2%, mostly in caprolactam. Ten points of the pricing gain came from raw-material pass-through after benzene and propylene costs rose, so much of the revenue increase simply reflects higher input costs. Nylon sales jumped 33% and chemical intermediates 24%, but caprolactam was flat and plant nutrients grew only 8%. Cost of goods sold rose about $70 million, outpacing the $56 million gain in sales. Adjusted EBITDA fell to $14.6 million from $24.7 million a year ago and from roughly $32 million in the second quarter. Margin compressed to 3.4% from 6.6%. Year to date, adjusted EBITDA margin stands at 4.1% versus 11.4% in 2025. The deterioration would have been worse without lower SG&A, which fell to $19.2 million from $27.4 million, although the prior-year figure included $4 million of strategic advisory fees.
The call made clear that several assumptions from the second quarter did not hold:
- **EBITDA trajectory:** Management had expected sequential EBITDA improvement in the second half. Instead, price over raws turned negative again, with a roughly $65 million raw-material headwind.
- **Plant nutrients:** The fall fill reset was larger than the typical $10-15 million because of challenging competitive dynamics.
- **Operations:** Caprolactam is running 8-10% below healthy-market levels, and reduced output at Hopewell and Frankford hurt fixed-cost absorption.
- **Cash flow target:** Full-year free cash flow is now framed as breakeven, excluding the $18 million 45Q carbon capture refund, which is likely slipping from the second half of 2026 into 2027.
- **Other trims:** Ammonia sales growth was cut to 25% from 30%, and the expected tax rate rose to about 20% from 10-15%.
- **Fourth quarter:** Management expects a year-over-year price-over-raws headwind, with U.S. benzene costs disconnected from Asia and Europe.
Cash flow was the quarter's genuine bright spot, though its quality is mixed. Operating cash flow rose to $48.0 million from $26.6 million, and free cash flow reached $29.7 million versus essentially zero a year ago. However, a $44.3 million increase in accounts payable drove much of that inflow, which is a timing benefit rather than recurring earnings power. Year-to-date free cash flow remains negative $32.3 million. Borrowings under the new $425 million facility (line of credit plus term loan) total roughly $268 million, versus $215 million on the revolver at year-end, and quarterly interest expense nearly doubled to $4.0 million. Capex discipline is helping: 2026 spending is now expected at about $90 million versus $116 million in 2025, with preliminary 2027 base capex near $80 million.
The forward catalysts are real but mostly back-end loaded:
- **Project CENTURY:** The $98 million Hopewell ammonia expansion was selected for $47 million in proposed USDA FIELDS funding. It would add about 84,000 tons of annual capacity through 2031 and targets an IRR above 20%.
- **Ammonium sulfate:** Management expects tighter domestic supply into spring 2027 as competitors idle capacity, and anticipates a larger fourth-quarter pre-buy.
- **Sulfur costs:** The Tampa sulfur marker eased from $705 to $615 per long ton. Each $100 move equates to roughly $35 million of annualized sensitivity, which provides meaningful leverage if relief persists.
- **New capacity:** A synthetic ammonium sulfate project is commissioning in the fourth quarter.
On the bear side, export caprolactam markets remain fundamentally challenged and building and construction demand is soft. Bears have legitimate ammunition.
Investor sentiment improved notably heading into the report, rising from -0.19 to near neutral at -0.01. That suggests expectations had already been reset low. Price action has been less forgiving. Shares were at $15.58 before the release, down 5.1% from the open after the August report and about 20% below the $19.49 200-day moving average. They sat just 5.5% above the inter-earnings low of $14.77 and nearly 13% below the September high. Earnings Whispers price and AVWAP trends remain negative, consistent with a stock that has been sold on rallies.
The bottom line is that AdvanSix's accelerating revenue is largely an inflation pass-through, while margins, earnings, and several 2026 targets moved the wrong way. Project CENTURY, a tighter ammonium sulfate market, easing sulfur, and lower capex give the story credible longer-term support. Still, near-term proof depends on price over raws recovering and caprolactam utilization improving, and neither showed up this quarter.
Read our earnings preview for AdvanSix Inc.: https://www.earningswhispers.com/article/ASIX/21670
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-06 | |
| Aug-07 | |
| Aug-07 | |
| Jul-07 | |
| May-08 | |
| May-08 | |
| May-07 | |
| Apr-17 | |
| Apr-13 | |
| Feb-20 |
