YETI's Margin Rebound Meets Its Inflation Test As Street Looks For A Big Earnings Jump
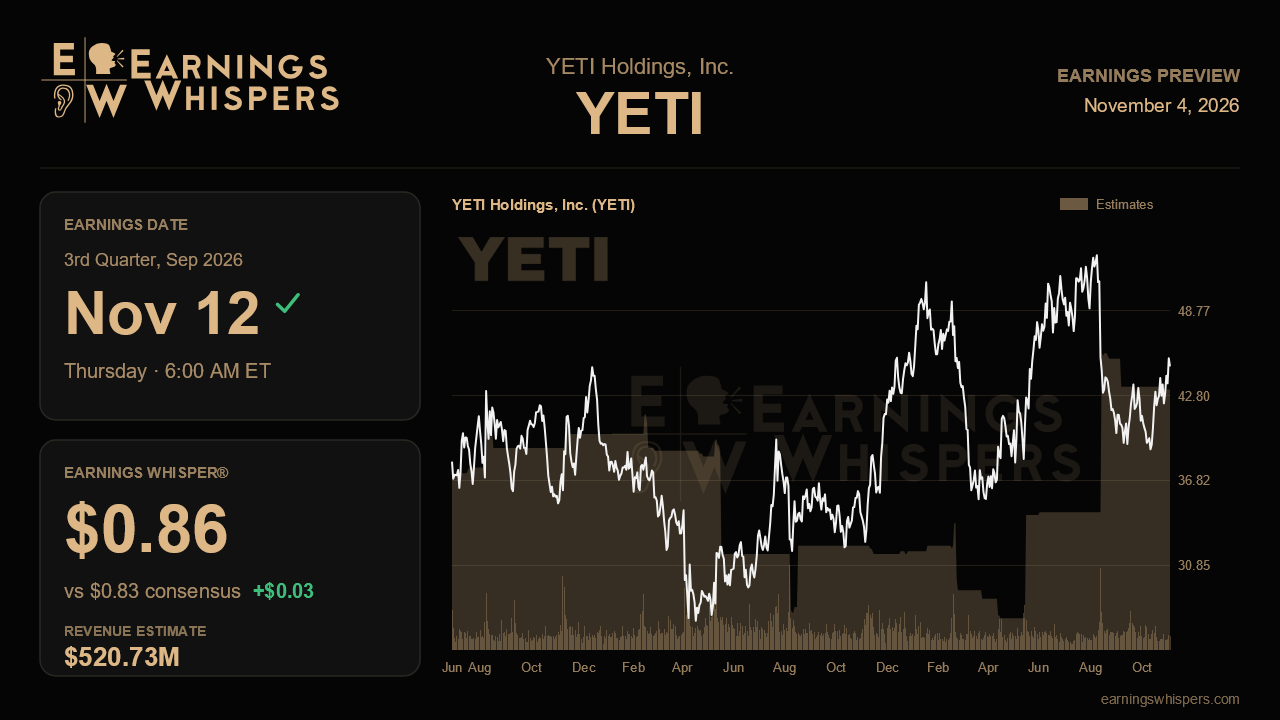
YETI enters its third-quarter report with a story that changed character in a single quarter. Through late 2025 the outdoor brand was a tariff-squeezed, slow-growth name. By the summer it had swung to accelerating sales, a gross margin that expanded instead of contracting, and a raised profit outlook. The question for the November 12 release, due before the opening bell, is whether that margin recovery can hold up against the rising input and freight costs management flagged last time, or whether the second quarter's improvement owed more to timing and one-off help than to a durable reset.
Wall Street is looking for adjusted earnings of $0.83 a share on revenue of $520.7 million. That revenue figure implies growth of about 6.8% from a year ago. The rate is solid but a step down from the 9% pace of the second quarter. Earnings carry far more of the load. The $0.83 target compares with $0.51 in the year-ago period, a jump that depends on gross margin rebuilding from last year's tariff-depressed 55.9% and on a share count shrunk by aggressive buybacks. The Earnings Whisper of $0.86 sits a few cents above consensus. That is a modest gap, but it suggests the informal bar is a beat rather than a merely in-line print.
Management reaffirmed full-year guidance of $2.94 to $3.00 in adjusted EPS on revenue of $2.00 billion to $2.02 billion. Consensus at $2.98 and $2.01 billion sits in the upper half of the earnings range and squarely at the revenue midpoint. That positioning matters. The last raise came entirely from margins and buybacks, while the 7% to 8% sales outlook was simply held. Another EPS lift is plausible if gross margin tracks toward the top of the raised 57.5% to 58% target. Investors should be wary, though, of earnings outperformance that rests on tariff refunds, which added $0.08 in the second quarter, rather than on underlying gross profit. The guide also assumed tariffs settle near 20% from September, so commentary on the actual rate will shape how believable the fourth-quarter math looks.
The operating details will decide whether the narrative strengthens. Coolers and equipment grew 16% last quarter and remain the clearest engine. International sales rose 19% as the footprint broadened toward 11 markets, and holding growth in the high-teens to 20% range would confirm that expansion is scaling rather than stalling. The softer spots are in the U.S. There, growth slowed to 6%, drinkware was flat, and management attached a drag of roughly 600 basis points to three trend-driven SKUs that will weigh through year-end. A U.S. drinkware figure no worse than flat would read as encouraging. Renewed declines, more cautious wholesale ordering beyond Canada, or operating expenses running above the raised 6% to 8% growth range would challenge the idea that margins can absorb rising costs.
Sentiment has warmed noticeably, with bullish readings climbing to about 54% from roughly 39% ahead of the prior report. The stock has not followed. Shares are down 2.5% since the last results, essentially matching the S&P 500, and at $44.85 they sit just above the 200-day moving average. They are also about 6% below the post-earnings high of $47.49 and well beneath the previous quarter's peak near $54. That gap between friendlier sentiment and a range-bound stock suggests the market still wants proof that the margin turn is real.
Ultimately, this report hinges on gross margin quality. If YETI shows expansion driven by pricing, mix and coolers strength while holding international momentum and keeping cost inflation contained, the upgraded earnings story stays intact. If the improvement leans on refunds and buybacks while U.S. demand softens, the summer's newfound confidence will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-04 | |
| Oct-22 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 |
Yeti Sees Long-Term Growth Driven by New Product Lines, International Expansion
YETI
The Wall Street Journal
|
| Sep-17 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-06 |
