YETI's Margin-Driven Beat Comes With Its First Guidance Cut Of The Year As U.S. Demand Softens
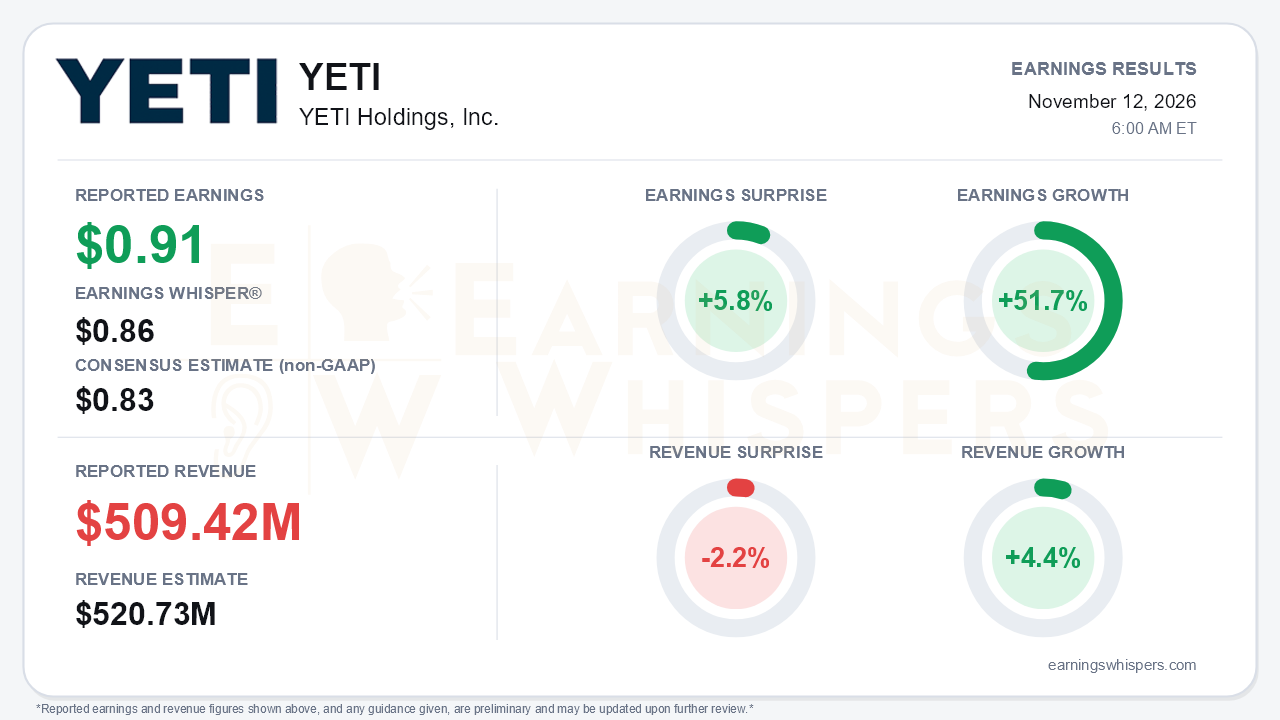
YETI Holdings delivered a profit beat and a revenue miss in the same quarter, and the guidance cut matters more than either. Third-quarter adjusted EPS of $0.91 topped the $0.83 consensus by 5.8% and cleared the $0.86 Earnings Whisper number, with earnings up 51.7% year over year. Revenue of $509.42 million, however, missed the $520.73 million consensus by 2.2% and grew only 4.4%. Management then lowered its full-year sales and EPS outlook. This is the first reduction of the year, after the company raised guidance in both Q1 and Q2. That is the central tension: YETI is getting more profitable faster than expected while its top line is losing altitude.
The quality of the beat deserves scrutiny. Adjusted gross margin rose 310 basis points to 59.0%, and 200 basis points of that came from lower net tariff costs. Only 110 basis points came from operational drivers such as pricing discipline and cheaper inbound freight, and those gains were partly offset by commodity inflation.
Two accounting details also matter:
- **Recall reserves.** Beginning this quarter, YETI again excludes adjustments to its 2023 product recall reserves from non-GAAP results, reversing the approach it adopted with Q4 2025. That change removed $18.2 million of recall charges from adjusted operating income. The reserve was increased because redemption rates exceeded forecasts.
- **Tariff refund.** A $4.7 million IEEPA tariff refund benefit recognized in Q3 cost of goods sold was not excluded from adjusted results.
On a GAAP basis, the picture is less dramatic: EPS rose 25% to $0.60 and operating margin reached 12.0%, versus 17.4% on an adjusted basis. A sharply lower share count also inflated per-share growth, with diluted shares falling from 81.4 million to 74.2 million on aggressive buybacks.
Beneath the headline, the mix shifted in ways that both encourage and concern.
The encouraging side:
- Drinkware accelerated to 8% growth, up from 2% in Q2 and 5% in Q1, despite a roughly 500-basis-point drag from trend-SKU comparisons.
- Wholesale jumped 19%, versus 10% in Q2.
- International rose 19% to $119 million, now about 23% of sales.
- Corporate and B2B sales returned to strong growth.
The concerning side:
- Adjusted U.S. growth slowed to 3%, from 6% in Q2 and 8% in Q1.
- Coolers & Equipment decelerated to 4% adjusted growth from 16% in Q2.
- Adjusted DTC fell 3% on weak U.S. e-commerce traffic and reduced Amazon Prime Day participation. Management said DTC was roughly flat excluding the Prime Day shift.
The tone shift is notable. Earlier this year, management described demand as resilient and strong. Now it describes uneven demand, deal-motivated consumers and moderation in early Q4, with higher-priced products under the most pressure. Wholesale strength alongside DTC weakness and a 22% inventory build to $394 million also raises a fair question: how much of the quarter reflects sell-in rather than end demand? Management attributes the build to an easy prior-year comparison and preparation for Q4 and 2027.
The revised outlook makes the deceleration explicit:
| FY26 metric | Prior outlook | New outlook |
|---|---|---|
| Adjusted sales growth | 7%–8% | About 6% |
| Adjusted operating income growth | 10%–12% | 7%–9% |
| Adjusted EPS | $2.94–$3.00 | $2.90–$2.95 |
| International growth | High teens to 20% | Mid-teens (Canada cited) |
| DTC growth | Mid single digits | Low single digits |
The roughly 14.9% adjusted operating margin and the $200–$225 million free cash flow targets were held. The implied Q4 gross margin of about 57.5%, however, sits below Q3's level. The cash flow target also requires a heavy fourth quarter, since free cash flow through nine months was $71.7 million. Meanwhile, cash has dropped to $73.8 million from $164.5 million a year ago after $150 million of repurchases this year.
The call did preserve a credible 2027 story:
- The drinkware trend-SKU headwind, roughly 600 basis points for fiscal 2026, rolls off to about zero starting in Q1.
- Project Upcycle, a $100 million productivity program with more than 50 active projects, is expected to produce wins that benefit 2027.
- Asia expansion is under way, with first brand stores in Japan and Korea and an initial China marketplace launch.
- Management expects fiscal 2027 to land within its mid-to-high single-digit long-term growth algorithm.
Bears have legitimate ammunition, though. Management flagged commodity inflation in resin, stainless steel and magnets, higher fuel and transport costs, and incremental 2027 tariff exposure. Those pressures could offset the productivity gains.
Investors were not leaning heavily into the report. Earnings Whispers sentiment remained positive but edged down from 0.394 to 0.367, a modest cooling rather than a reversal. The stock entered the release at $42.79, down 7.0% from the $46.00 open after the August report and 2.4% below its 200-day moving average. Shares had rallied from an October 14 low of $38.69 to $49.05 on November 5, then gave back 12.8% in the days just before the report. Most Earnings Whispers trend readings were positive, but the price trend was negative, consistent with a market already discounting some of the demand softness.
The bottom line is that YETI's quarter showed real margin discipline, a reaccelerating Drinkware business and powerful international momentum. The headline beat, however, leaned on tariff relief, a favorable non-GAAP methodology change and a shrinking share count, while U.S. demand, DTC and coolers lost steam and full-year guidance moved lower for the first time this year. Until U.S. consumer demand stabilizes and the inventory build clears, the 2027 setup carries as much execution risk as opportunity.
Read our earnings preview for YETI Holdings, Inc.: https://www.earningswhispers.com/article/YETI/22904
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 min | |
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 10 hours | |
| Nov-05 | |
| Nov-04 | |
| Oct-22 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 |
Yeti Sees Long-Term Growth Driven by New Product Lines, International Expansion
YETI
The Wall Street Journal
|
| Sep-17 | |
| Aug-14 |
