Knightscope's Promise Of Ever-Better Quarters Meets A Flat Revenue Forecast And Thinning Cash
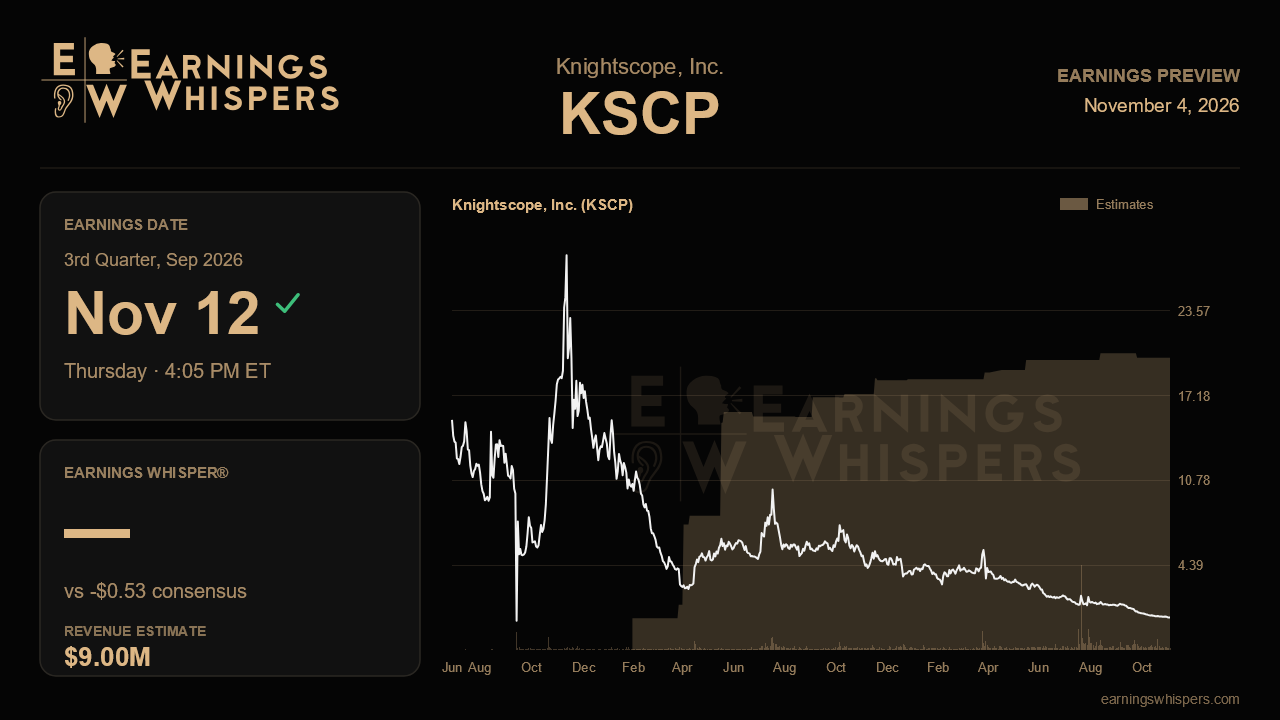
Knightscope heads into its September-quarter report with a striking contradiction. Its operations have just posted two straight record quarters, yet the stock has lost more than two-thirds of its value since the last report. Management has repeatedly said each quarter will beat the one before it. Wall Street's numbers, however, call for no sequential revenue growth at all, and the company's cash balance gives it little room to miss.
Consensus expects a loss of $0.53 per share on revenue of about $9.0 million. That revenue figure would be up roughly 188% from the $3.1 million reported a year ago, and the per-share loss would be a big improvement on last year's $0.98 deficit. But nearly all of that year-over-year jump comes from the Event Risk and Security Force acquisition, which closed in late February. The more useful comparison is with the prior quarter, which also brought in $9.0 million. A flat result would technically meet the Street's forecast. It would also break the pattern management has been promoting since its May roadshow. With no formal guidance on the table, that promise is the bar that matters, and only a figure above $9 million clearly clears it.
The expected narrowing of the loss from last quarter's $0.79 per share also needs scrutiny. Last quarter, operating expenses climbed to $13.8 million from $10.8 million, and the net loss widened to $14.1 million. A smaller per-share loss could come from real cost discipline. It could also come from a larger share count if the company has kept selling stock through its at-the-market facility. Investors should look at the dollar loss and the operating expense line before giving credit for improvement.
The balance sheet is the main swing factor. Cash fell to $8.2 million at the end of the last quarter, less than one quarter's net loss, and the filings already carried going-concern language. Any update on how the company is funding operations will matter as much as the income statement. That includes the pace of equity issuance, the size of the cash balance and any new financing. Management also said it is pursuing remote-monitoring acquisitions it believes could add to earnings. That ambition looks hard to square with the current cash position unless the funding is clearly explained.
The operating story still has real substance. Gross margin turned positive in each of the last two quarters, at roughly 7%. Management argues that combining robots, software and human guards is structurally more profitable than the old hardware-only model. Holding that margin, or nudging it higher, would support the claim. Slipping back toward a gross loss would undercut it, especially since human guarding only earns margins of 10% to 20% and the long-term blended target of 50% to 60% remains distant. Several product milestones also deserve an update. The Autonomous Security Force launched at GSX in mid-September, the Signals orchestration platform is due in the second half, and the K7 robot is supposed to reach its first customers in the fourth quarter. Evidence of early orders, keeping the 434-client base and holding near-zero churn among legacy Security Force clients would show the catalysts are progressing. Delays on any of these would hurt credibility quickly.
Sentiment has softened from deeply bearish to modestly bearish heading into the print, but the price action tells a harsher story. At $0.45, the shares sit at the very bottom of their post-earnings range, well below the $1.35 floor of the prior quarter and far beneath the 200-day average near $2.41. The market is clearly pricing in dilution and financing risk rather than growth.
In the end, the report has to show that Knightscope's acquisition-driven growth can keep compounding without draining its cash. Sequential revenue gains, steady gross margin and a believable funding plan would keep the turnaround story intact. A flat top line combined with mounting losses would suggest the market's skepticism has been justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-29 | |
| Oct-20 | |
| Oct-19 | |
| Oct-01 | |
| Sep-22 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-03 | |
| Sep-01 | |
| Aug-28 |
