Knightscope Beats On EPS, But A Sequential Revenue Slip And A Cash Balance Below One Quarter's Loss Overshadow Record Bookings
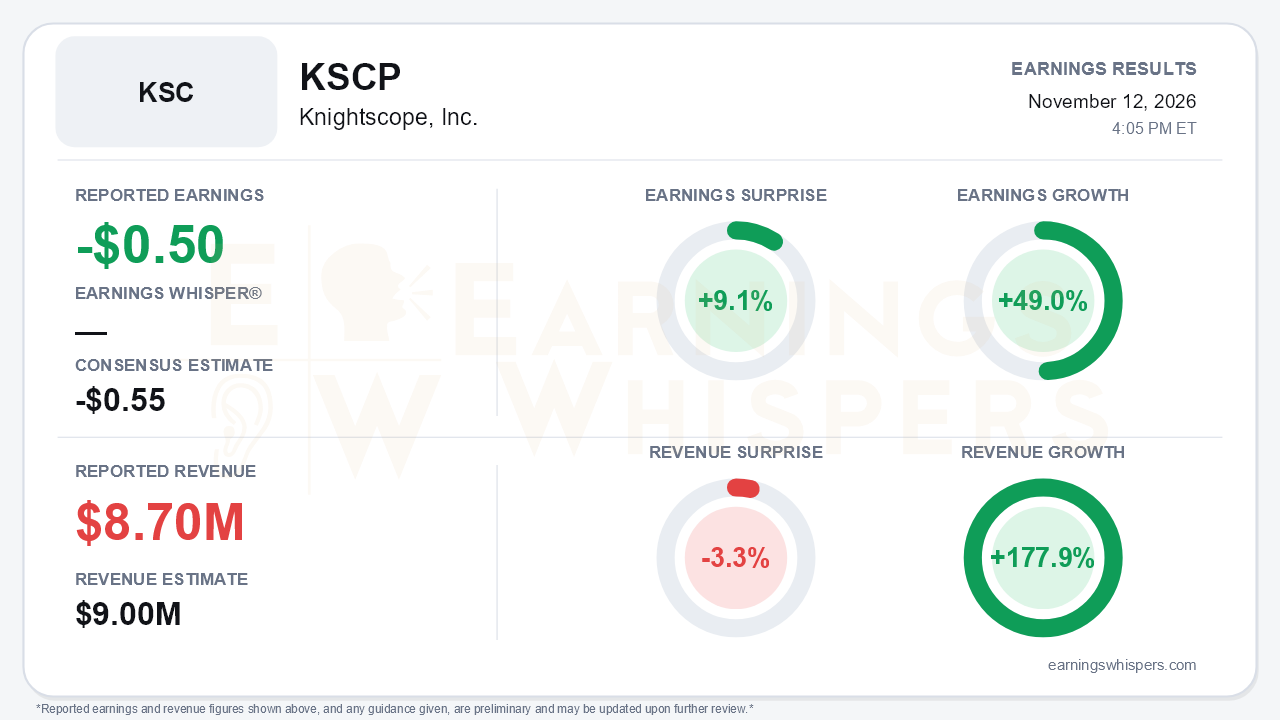
Knightscope reported a third-quarter loss of $0.50 per share, 9.1% better than the consensus estimate of a $0.55 loss and a 49.0% improvement from a year ago. Revenue of $8.7 million grew 177.9% year over year but missed the $9.0 million consensus by 3.3%. The quarter extended the company's run of triple-digit growth to three consecutive periods. The central tension is not the beat. It is that revenue and gross margin both slipped sequentially while cash fell to $6.8 million against a quarterly net loss of $11.8 million. A growth story built on record bookings now runs into a balance sheet with almost no margin for error.
The quality of the earnings beat deserves scrutiny. The per-share improvement came largely from dilution, not from a smaller loss. Weighted average shares rose to 23.6 million from 9.8 million a year earlier. The absolute net loss actually widened to $11.8 million from $9.5 million.
The sequential comparison is more favorable:
- **Net loss:** narrowed from $14.1 million ($0.79 per share) in the second quarter.
- **Operating expenses:** fell to $12.0 million from $13.8 million.
- **R&D:** declined 5% year over year to $3.6 million as engineering moved in-house.
The headline growth rate also needs context. Service revenue jumped 349% to $8.6 million, but $6.6 million of that came from the acquired Knightscope Security Force (KSF) business. Organic growth was not disclosed. Product revenue nearly disappeared, falling to $0.1 million from $1.2 million a year ago and $1.8 million in the first quarter, as hardware sales were deprioritized.
Beneath the triple-digit comparison, the trajectory has flattened. Revenue declined from the second-quarter record of $9.0 million. That contradicts management's pledge last quarter that each quarter would beat the last. Consolidated gross margin eased to 5% ($0.4 million), down from roughly 7% in the second quarter and 7.7% in the first. Services gross margin of 8% is a genuine improvement over a $1.6 million service gross loss a year ago. Even so, these margins are far too thin to absorb $12 million of quarterly operating expense. Management offered no formal guidance and no profitability timeline. The call tone stayed promotional but read as more defensive, with a shorter prepared script and extended commentary on the share price.
The bull case rests on demand. Knightscope disclosed a record of roughly $27 million in renewals, bookings and client awards since May. Management said a large portion represents expansion or new customers. Several milestones flagged on earlier calls were delivered:
- The Autonomous Security Force was unveiled at GSX.
- K7 manufacturing began at headquarters.
- The Signals orchestration software went live in its initial release.
But conversion is the open question. Management named turning that $27 million into revenue as a top priority, while the release cautions that awards may not become definitive agreements. K7 language also softened, from 'initial deployments in Q4' to 'lower production volumes this coming year.' Management described deployment, not manufacturing, as the constraint.
Bears have legitimate ammunition on liquidity:
- **Cash decline:** cash has fallen from about $20.6 million at year-end 2025 to $11.4 million, then $8.2 million, then $6.8 million.
- **Funding need:** the cash balance is now below a single quarter's net loss.
- **Listing risk:** the company received a Nasdaq minimum bid-price deficiency notice and has a 180-day cure period, with options still under evaluation.
- **Risk disclosures:** the release's risk language references the at-the-market offering program and the company's ability to raise capital and continue as a going concern.
The market has already priced much of this stress. Shares closed at $0.40 on the eve of the report, down 71.7% from the $1.41 open following the August release. The stock sat 82.6% below its 200-day moving average of $2.30 and just 2.5% above the $0.39 low set on November 10, which was also a 52-week low. It had surrendered virtually the entire range from the $1.69 post-report high in mid-August. Investor sentiment remained deeply negative, though it improved modestly to -0.67 from -0.72. That suggests expectations were already low, not that confidence has returned. The internal trend readings are mixed, with momentum positive while AVWAP remains negative. That fits a stock trading at its lows with heavy overhead supply.
The bottom line is that Knightscope delivered the narrative pieces it promised, including record bookings, the Autonomous Security Force launch, K7 production and live software. However, the financial core of the quarter weakened sequentially. Revenue dipped, gross margin compressed, product sales vanished, and the EPS beat owed more to a larger share count than to a smaller loss. With $6.8 million in cash, a Nasdaq compliance clock running, and no profitability timeline, the investment setup now hinges less on demand than on financing. The key questions are how quickly the $27 million pipeline converts to revenue and how much further dilution shareholders absorb along the way.
Read our earnings preview for Knightscope, Inc.: https://www.earningswhispers.com/article/KSCP/22927
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-29 | |
| Oct-20 | |
| Oct-19 | |
| Oct-01 | |
| Sep-22 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-03 |
