Liftoff Mobile Must Prove A Profit Swing Is Real After A 39% Slide
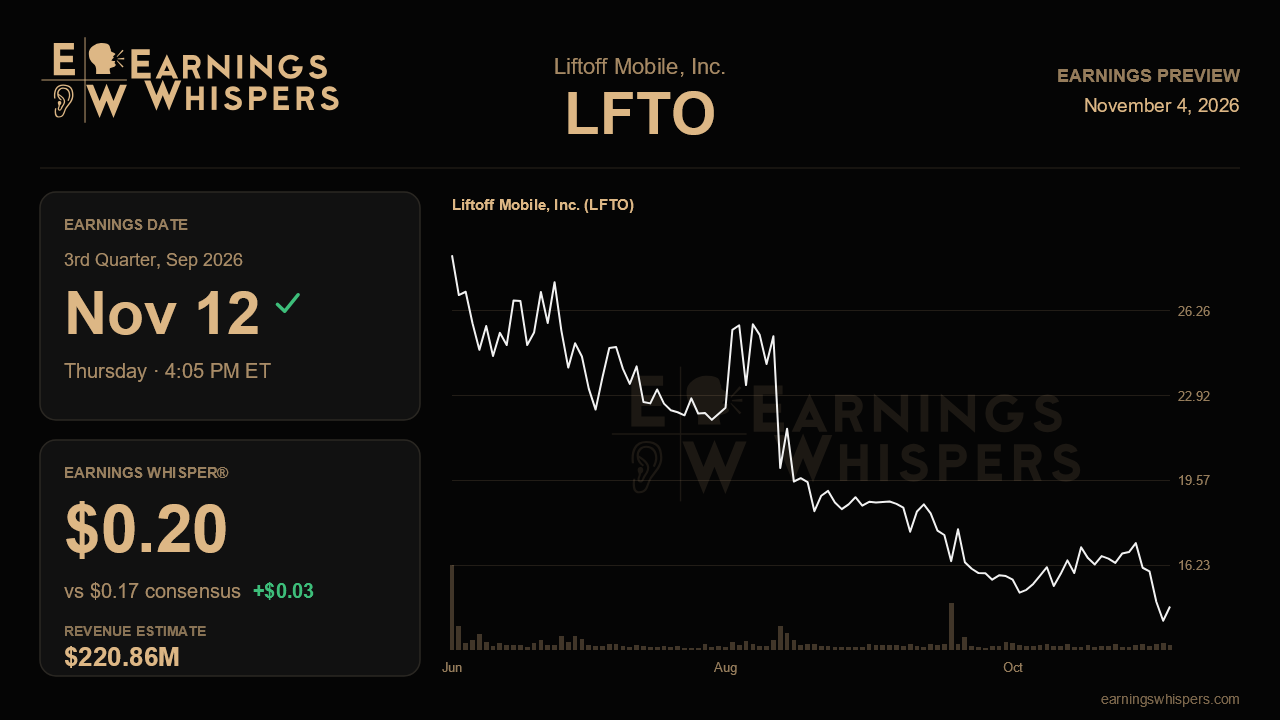
Liftoff Mobile heads into its September-quarter report with an awkward combination: a stock that has lost nearly 40% of its value since the last release, and a Street forecast that calls for a meaningful improvement in profitability. That tension makes the November 12 report, due after the close, less about whether revenue grows and more about whether the company can show that its earnings power is improving even without much help from the top line.
The numbers frame the setup clearly. Analysts expect earnings of $0.17 per share on revenue of about $220.9 million. Last quarter, Liftoff posted a loss of $0.03 per share on revenue of $219.5 million. In other words, consensus assumes revenue barely changes from one quarter to the next while the bottom line swings by roughly 20 cents per share. That kind of move cannot come from volume alone. It implies better gross margins, tighter operating expenses, lower one-time charges, or some mix of all three. The Earnings Whisper of $0.20 sits three cents above consensus, which is not trivial on a base this small. It suggests that the more optimistic corners of the market expect the profit improvement to be even sharper than the published estimates.
With no formal guidance on the table to anchor those forecasts, the report itself carries more weight than usual. The first question is whether revenue at least holds near the $220 million level. A flat quarter would be acceptable if it comes with clear evidence of cost discipline, but a sequential decline would make the earnings forecast look fragile, because it would mean the profit swing depends entirely on spending cuts. The second question is the quality of the earnings. If the gain from last quarter's loss is driven by fewer unusual expenses rather than a durable improvement in margins, the market may discount it. Investors should look for signs that operating leverage is structural, such as expense growth running below revenue growth and margins expanding on a comparable basis.
The market's verdict since the last report has been harsh. Shares have fallen 38.8%, compared with a 2.7% dip for the S&P 500, leaving the stock about 36 percentage points behind the broader market. At $14.60, it trades well below its 200-day moving average of $20.48 and only about 5% above its post-earnings low of $13.96, far from the $23.86 high reached after the last release. That is a chart of persistent selling, not consolidation. Curiously, sentiment toward the stock has turned markedly more bullish than it was heading into the prior report. That divergence suggests some investors see the selloff as overdone and are positioning for a rebound, while the price action shows that conviction has not yet been rewarded.
That combination cuts both ways. A depressed share price and a low starting point mean that a clean quarter showing genuine profitability could force a reassessment. But the whisper number and improved sentiment raise the bar, and a result that merely meets consensus may not be enough to reverse months of weakness. The central issue is straightforward: Liftoff needs to demonstrate that it can turn roughly flat revenue into real, repeatable profit. If it does, the recent slide may look like an overreaction. If the earnings improvement appears thin or one-off, the stock's position near its lows could become a floor that fails to hold.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-27 | |
| Aug-25 | |
| Aug-19 | |
| Aug-12 | |
| Aug-12 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-14 | |
| Jun-29 | |
| Jun-05 | |
| Jun-04 | |
| Jun-04 |
