Liftoff Mobile Crushes Q3 And Raises The Year, But Decelerating Growth Keeps The Debate Alive
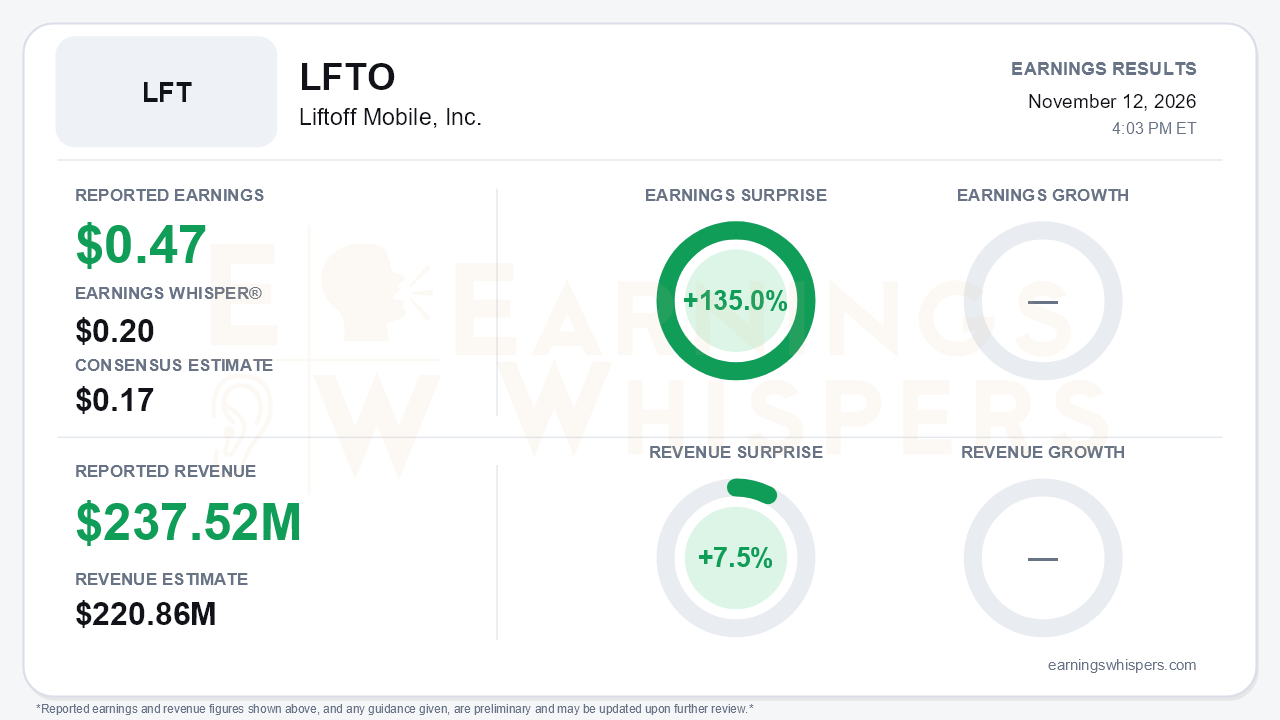
Liftoff Mobile delivered the kind of quarter a recent IPO needs. It reported third-quarter earnings of $0.47 per share against a $0.17 consensus and a $0.20 Earnings Whisper, a 135.0% surprise. Revenue of $237.52 million topped the $220.86 million consensus by 7.5% and beat the high end of management's own $217-222 million guide by roughly $16 million. The company also swung to GAAP net income of $87 million from a $5.7 million loss a year earlier and a $4 million loss in Q2, then raised full-year targets across the board. The central tension is that the revenue growth rate is slowing even as profitability and cash generation step up sharply. The stock has been priced as if the slowdown matters more.
The quality of the EPS beat deserves some scrutiny, even though the operating improvement is real. Income from operations more than doubled to $103.8 million from $47.8 million a year ago, and adjusted EBITDA rose 45% to $145 million at a 61% margin, well ahead of the 57-58% guide.
Several items below the operating line flattered the GAAP figure:
- a $14.4 million gain on contingent consideration revaluation, versus a $17.5 million charge in Q2;
- a $1.4 million earnout-liability gain;
- a much lighter tax charge, at $7.3 million versus $23.5 million in Q2.
Post-IPO deleveraging also helped. Long-term debt fell to $1.39 billion from $1.80 billion at year-end, the preferred stock is gone, and interest expense dropped to $25 million from $33 million sequentially. Net leverage improved to 2.1x from 2.4x. Quarterly free cash flow of $93 million, up from $50 million in Q2, is arguably the cleaner signal of earnings power than the headline EPS.
The call preserved a credible growth story, but the trajectory is unmistakably bending lower. Year-over-year revenue growth went from 35% in Q2 to 32% in Q3, and the Q4 guide of $244-249 million implies 26-28%. Sequential growth actually improved to 8% from 7%, which supports management's case that demand is healthy rather than fading. Still, other details point to a maturing expansion cycle:
- Customers spending over $100,000 grew by only 34 year over year, versus 50 in Q2.
- The share of growth coming from existing customers slipped to 55% from 58%.
- The SDK footprint was described as "over 160,000" apps, against "close to 170,000" last quarter.
The guidance raise was substantial nonetheless. Full-year revenue moved to $907-912 million from $870-880 million, adjusted EBITDA to $547-551 million from $510-518 million, and the margin target to about 60%.
Management leaned into product and secular catalysts. On product, a Cortex upgrade now predicts the value of users who monetize through in-app ads, extending optimization to hybrid and ad-supported apps. A new data-training architecture also showed what management called encouraging initial results. On the demand side, management cited an AI-driven surge in app creation, with roughly 560,000 new App Store releases in the first half, about double a year ago. It also pointed to the migration of discovery away from web search toward owned apps. The CEO said he has "never been more confident" and expressed conviction about 2027 margin expansion.
Bears have legitimate ammunition, though:
- No 2027 guidance was given, despite tough comparisons against World Cup-boosted 2026 periods.
- Comparisons with peers' step-change model releases remain an overhang, and the Q4 outlook again excludes any future model breakthroughs.
- Core Advertising Revenue reporting will end in Q1 2027. Management argues this is reasonable because non-core revenue is now de minimis.
- Roughly $1.4 billion of debt remains.
The market setup is more complicated than the surprise implies. Shares entered the report at $18.55, down 22.2% from the $23.84 open after the August release, which was effectively the inter-earnings high. They also sat 8.8% below the 200-day moving average of $20.33. The stock set a 52-week low of $13.96 on November 2 before rebounding about 33% into the print, so some recovery was already under way.
Earnings Whispers investor sentiment moved sharply more positive from a prior reading of 0.31. However, the supplied current reading of 5.08 falls outside the stated -1 to +1 scale, so the direction is clearer than the magnitude. The AVWAP trend signal is positive, consistent with that recent rebound.
The bottom line is that Liftoff answered the profitability and cash-flow questions decisively, with a large beat, a meaningful raise, rapid deleveraging and a first real GAAP profit. The unresolved question is growth durability. With year-over-year growth guided down to the high-20s, large-customer additions slowing, disclosure narrowing and no 2027 framework, investors are being asked to trust Cortex execution and the AI-app thesis to carry the business through tougher comparisons. For a stock still well below its post-IPO-quarter levels, that is the debate the next few quarters must settle.
Read our earnings preview for Liftoff Mobile, Inc.: https://www.earningswhispers.com/article/LFTO/22928
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Nov-04 | |
| Oct-27 | |
| Aug-25 | |
| Aug-19 | |
| Aug-12 | |
| Aug-12 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-14 | |
| Jun-29 | |
| Jun-05 |
