Nektar Reports With Shares Halved, Phase 3 Spending Rising And A Jury Trial To Explain
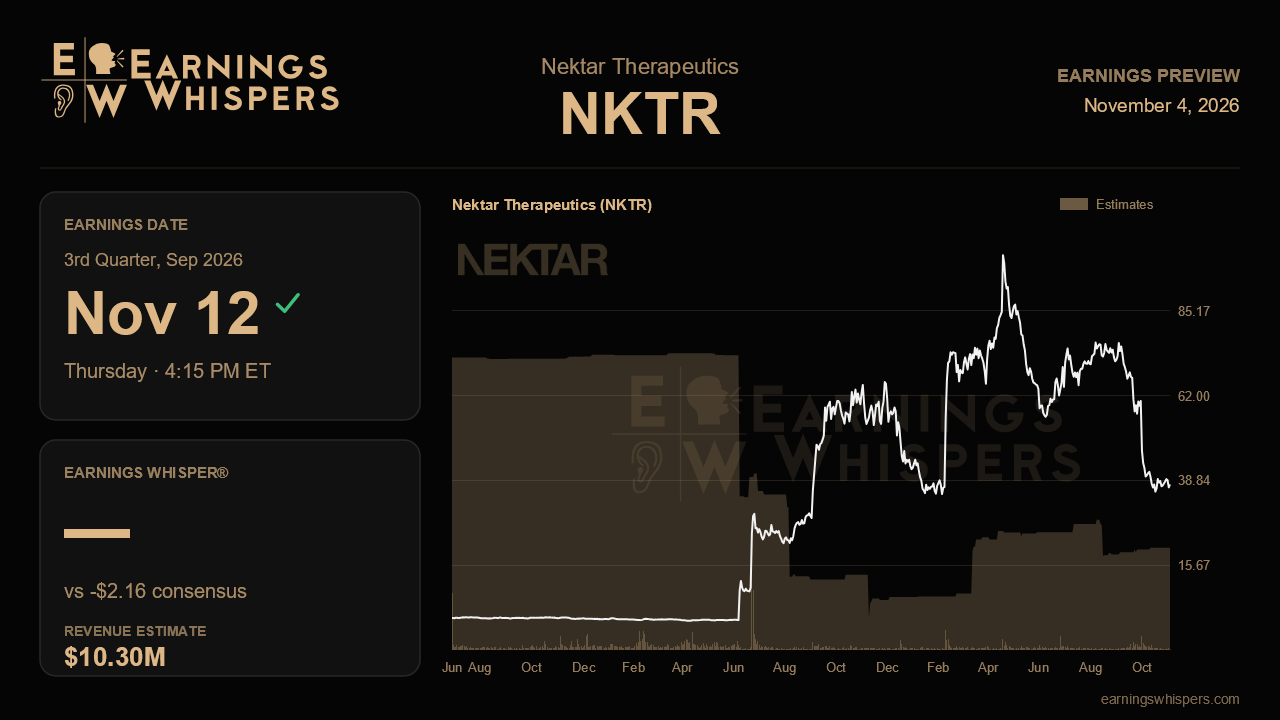
Three months ago Nektar Therapeutics sounded like a company that had finally put its house in order: roughly $1.02 billion in the bank, a raised year-end cash forecast, FDA alignment on a single registrational alopecia study and an atopic dermatitis Phase 3 program already randomizing patients. The market has since cut the stock roughly in half, a 46-point gap versus the S&P 500. When Nektar reports third-quarter results after the close on November 12, the question is less about the income statement. It is whether management can show that the confident, execution-focused story from the summer still holds.
The numbers themselves are expected to reflect a company spending heavily into its late-stage programs. Consensus calls for a loss of $2.16 per share, wider than the $1.23 loss last quarter and the $1.85 loss a year ago. Revenue is pegged at $10.3 million, roughly flat with the prior quarter but down about 13% from last year. That revenue is largely non-cash royalty income, which management has guided to $40 million to $45 million for 2026, down from $55.2 million last year. A quarter near $10 million keeps the company tracking toward the low-to-middle part of that range. Royalties are a slowly shrinking cushion, not a growth driver, so a modest miss here matters little.
Spending and cash are the real financial tests. Management raised and tightened its 2026 R&D outlook to $210 million to $230 million, against $117.3 million last year, and second-quarter R&D was $39.1 million. That run rate is well below the guided pace, which implies a sharp step up in the back half as three atopic dermatitis studies and manufacturing work ramp. A big R&D jump would be consistent with the plan rather than alarming. The more telling figure is cash. Moving from about $1.02 billion at midyear to the guided $815 million to $840 million by year-end implies burn of roughly $90 million to $100 million per quarter. A September balance comfortably on that path, plus a reaffirmed runway into the third quarter of 2028, would support the claim that the company is funded through its first atopic dermatitis readouts.
Operational updates should carry more weight than earnings. Management promised the third, treatment-experienced Zenith AD study would start by the end of September. Confirming that it did, along with steady enrollment, would validate the pivot to Phase 3 execution. Investors will also want reassurance that Zenith AA remains on track for an early 2027 start. Nearer term, the company flagged two oral presentations at EADV in October, 24-week off-treatment alopecia data from Resolve AA due in the fourth quarter, and a new clinical study for its TNFR2 bispecific before year-end. Any slippage in these dates would undercut the credibility management rebuilt last quarter.
The largest unknown is the federal jury trial scheduled to begin September 8 in San Francisco, on which management said little in August. This report is the first formal chance to explain where that case stands and what, if any, financial exposure exists. The stock's slide and the drop in sentiment, from 37% bullish to under 19%, suggest the market has been pricing in more uncertainty, whether from litigation, competing alopecia and atopic dermatitis programs, or both. At $37.76, shares sit near the $35.61 low of their post-earnings range and far below the 200-day average of $64.88. That leaves little technical support if the update disappoints.
In the end, Nektar needs to show that the summer pivot was substance, not mood. Evidence that the Phase 3 studies are on schedule, cash is burning as planned and the legal overhang is defined and manageable would keep the de-risking narrative intact. Ambiguity on any of these, especially the trial, would leave the recent selloff looking justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-27 | |
| Oct-23 | |
| Oct-05 | |
| Oct-01 |
Nektar Posted Promising Alopecia Results. Here's Why It Took A 22% Beating.
NKTR -22.39% NKTR -7.26%
Investor's Business Daily
|
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-26 | |
| Sep-25 | |
| Sep-25 |
