Nektar's Per-Share Beat Owes Much To Dilution As Its Rezpeg Phase 3 Program Moves Into Execution, With Shares Down 48% Since The Last Report
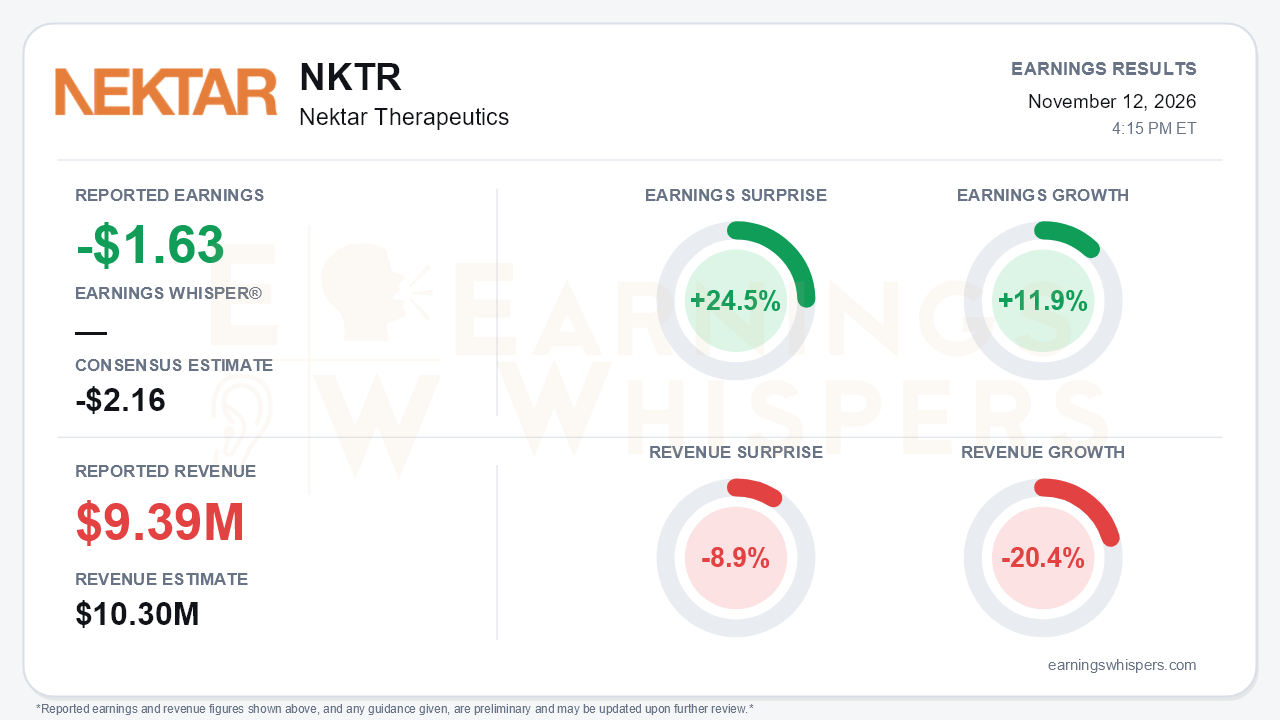
Nektar Therapeutics reported a third-quarter loss of $1.63 per share. That was well ahead of the -$2.16 consensus, a 24.5% earnings surprise, and represents 11.9% year-over-year earnings growth. Revenue of $9.39 million missed the $10.3 million consensus by 8.9% and fell 20.4% from a year ago. The quality of the beat deserves scrutiny. The narrower per-share loss reflects a nearly doubled share count, with weighted average shares rising to 34.2 million from 18.9 million, rather than improving economics. In absolute terms, the net loss widened to $55.7 million from $35.5 million a year ago and from $40.6 million in the second quarter. For a clinical-stage company, though, the income statement is not the story. The story is that rezpegaldesleukin has moved from Phase 3 planning to Phase 3 execution, funded by a balance sheet that has been transformed this year.
The spending profile reflects that shift. R&D rose to $44.1 million from $27.3 million a year ago, driven by the ZENITH AD and ZENITH AA programs and by rezpeg manufacturing. G&A was the less welcome line. It jumped to $24.6 million from $16.1 million a year ago and from roughly $12.8 million in the second quarter, which the company attributed to higher legal expenses. Full-year G&A is now tracking toward about $65 million, the top of the $60-65 million range. The litigation trial that had been scheduled for September 8 went unaddressed on the call, which leaves an open question. Revenue is entirely non-cash royalty income, so the shortfall has little bearing on liquidity. Even so, management cut its 2026 royalty outlook to about $38 million from $40-45 million. One data inconsistency should be noted. The call analysis cites third-quarter royalties of $8.5 million versus $10.1 million in Q2, while the income statement shows $9.4 million in non-cash royalty revenue. Either way, the direction is lower.
The balance sheet offsets those negatives. Cash and investments stood at $952.9 million, compared with $245.8 million at the end of 2025, following roughly $476 million in raises and a $350 million April offering. That figure was down from about $1.02 billion last quarter. Management nonetheless raised year-end cash guidance to more than $840 million, up from $815-840 million. It also cut full-year R&D guidance to $185-200 million from $210-230 million, and trimmed expected non-cash interest expense to about $28 million. Even the lowered R&D range implies a sizable fourth-quarter step-up as enrollment builds. The call carried a markedly more confident tone, with the CEO describing the quarter as 'transformative.'
The operating catalysts lean positive.
- **Atopic dermatitis.** All three ZENITH AD registrational trials, totaling about 1,500 patients, are now underway. Enrollment is expected to be complete around January 2028, with topline data in summer 2028 and a BLA targeted for 2029.
- **Alopecia areata.** The roughly 850-patient ZENITH AA trial was pulled forward to a December start from early 2027.
- **AD-2 redesign.** Following FDA, EMA and PMDA feedback, ZENITH AD-2 was converted to a topical corticosteroid combination study in both naive and experienced patients, aimed at a broader label that includes Japan.
- **Pipeline expansion.** Management added a roughly 30-patient vitiligo proof-of-concept study and a Mount Sinai investigator-sponsored trial in moderate alopecia areata.
- **New data.** At EADV, the share of alopecia patients reaching SALT 10 rose from 7% at the end of treatment to 19% six months off drug. A biomarker sub-study linked early Treg activity to week-16 EASI response.
The next near-term readout is the 52-week AD off-treatment data in 1Q27, which management benchmarked against roughly 50% EASI-75 maintenance for Dupixent.
Bears still have legitimate ammunition. The AD-2 redesign adds execution and regulatory complexity at a point when two positive Phase 3 trials are needed for registration. Type 1 diabetes cohort data slipped to late 2027 or early 2028. Competitive atopic dermatitis readouts, including STAT6 programs and bi- and trispecifics, will arrive well before ZENITH data.
The market has treated the stock harshly regardless of the improved clinical cadence. Shares entered the report at $38.44, down 48.1% from the $74.00 open after the August release. The stock sits 40.8% below its 200-day moving average and just 7.9% above its October 16 inter-earnings low of $35.61. It peaked at $77.76 on September 8 and has since lost half its value. The release itself offers no clear explanation for that collapse. Investor sentiment remained positive but weakened noticeably, falling to 0.24 from 0.37. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Nektar delivered the clinical execution investors were promised, plus a cash cushion that should carry the company to its 2028 readouts. The EPS beat, however, is largely a function of dilution rather than improving economics. Rising legal costs, shrinking royalties and an unaddressed litigation overhang complicate the picture. Above all, a stock that has halved in a quarter shows the market is not yet giving credit for the faster timelines.
Read our earnings preview for Nektar Therapeutics: https://www.earningswhispers.com/article/NKTR/22933
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Nov-11 | |
| Nov-04 | |
| Oct-27 | |
| Oct-23 | |
| Oct-05 | |
| Oct-01 |
Nektar Posted Promising Alopecia Results. Here's Why It Took A 22% Beating.
NKTR -22.39% NKTR -7.26%
Investor's Business Daily
|
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 |
