Proficient Auto Logistics Faces Proof Test On Hanson & Adkins Deal After Stock Halves
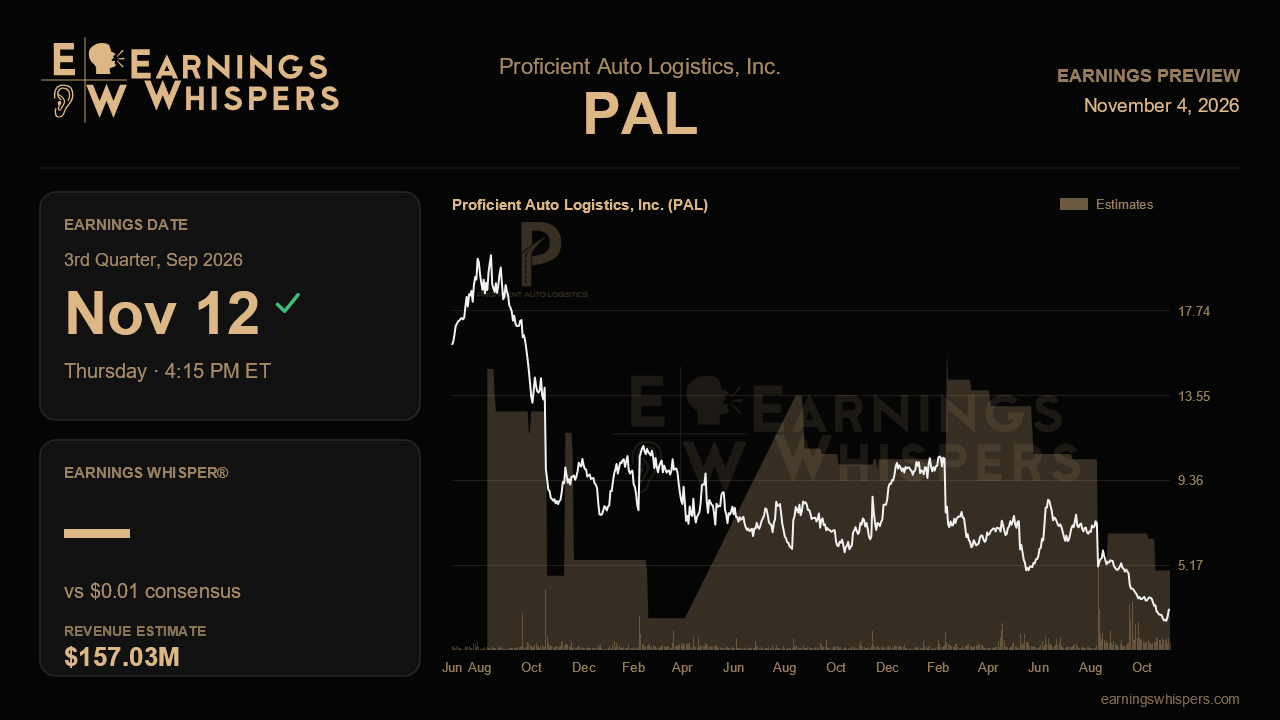
Few trucking stocks head into earnings with as wide a gap between management's story and the market's verdict as Proficient Auto Logistics. Last quarter the auto hauler announced the acquisition of Hanson & Adkins, a deal it said would create the largest car carrier in North America, and it argued that the industry had finally bottomed. Since then the shares have lost nearly half their value while the broader market barely moved. The third-quarter report, due after the close on November 12, is the first real chance to see whether the bigger platform and the improving freight backdrop can show up in the numbers.
The Street is looking for a profit of about a penny a share on revenue of roughly $157 million. That revenue figure would be up more than 37% from the year-ago quarter and well above the $109.4 million reported last quarter, which tells you consensus is leaning heavily on acquired revenue rather than organic recovery. The EPS comparison looks dramatic on a percentage basis, but it is really a move from a two-cent loss a year ago to roughly breakeven. Management guided to $350 million to $370 million of combined revenue for the back half of the year. If the third quarter lands near $157 million, the fourth quarter would need to deliver somewhere around $193 million to $213 million, so the composition and run rate of this quarter's sales will matter as much as the headline total.
Margins are the more delicate issue. Management already lowered the near-term bar, guiding to an operating ratio of about 97% and an EBITDA margin of 8% to 9% for the second half, and effectively shelving the earlier promise of 150 basis points of full-year operating ratio improvement. The sub-95% goal has been pushed into 2027 and beyond. That makes this guide the line in the sand. Hitting it would suggest that June's 95.7% operating ratio, the best month of the year, was a genuine turning point rather than a blip. Missing it after a reset would be far more damaging than the original miss, because it would raise doubts about whether management understands its own cost structure.
The operating details deserve close attention. Revenue per unit rose about 3% last quarter while units fell 8%, so the key question is whether volumes have stabilized enough for pricing to carry the business. Management pointed to tightening capacity from driver shortages, stricter enforcement on non-domiciled licenses and the Montgomery ruling as tailwinds that favor larger, safety-focused carriers. Evidence of that would include firmer rates, more spot and incentive participation, and a better handle on fuel surcharge lag. The flip side is that the same tight capacity raises driver and sub-haul pay, and sub-haul volumes already slipped as outside carriers chased better-paying freight. Early integration progress on maintenance insourcing, procurement and network density, plus any update on the new Canadian business, will also shape how much credit the market gives the 2027 synergy story.
The balance sheet is the other overhang. The deal brought a new equipment facility, a $75 million convertible and an expanded revolver on top of leverage that was already about 2.1 times before closing. With the stock around $2.95, well below its 200-day average near $6.27 and closer to its post-earnings low of $2.35 than its $6.06 high, the market appears to be pricing in dilution and integration risk. Sentiment has also turned noticeably more bearish than it was heading into the last report.
That skepticism sets a low bar in some ways and a high one in others. The quarter does not need to be pretty, but it does need to show that the lowered margin guide is achievable and that the combined company is producing the cash flow needed to carry its heavier debt load. If Proficient can pair acquired scale with steady unit pricing and a margin trajectory toward 97%, the narrative of an inflecting auto-haul market remains intact. If costs once again outrun pricing, the deal will look less like a transformation and more like a bigger version of the same problem.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-30 | |
| Oct-05 | |
| Aug-14 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jun-01 | |
| May-11 | |
| May-07 | |
| May-06 | |
| Apr-10 | |
| Mar-02 |
