Proficient Auto Logistics Misses Badly As Legacy Business Shrinks; Bigger Synergy Targets Push The Recovery Story Out To 2027-28
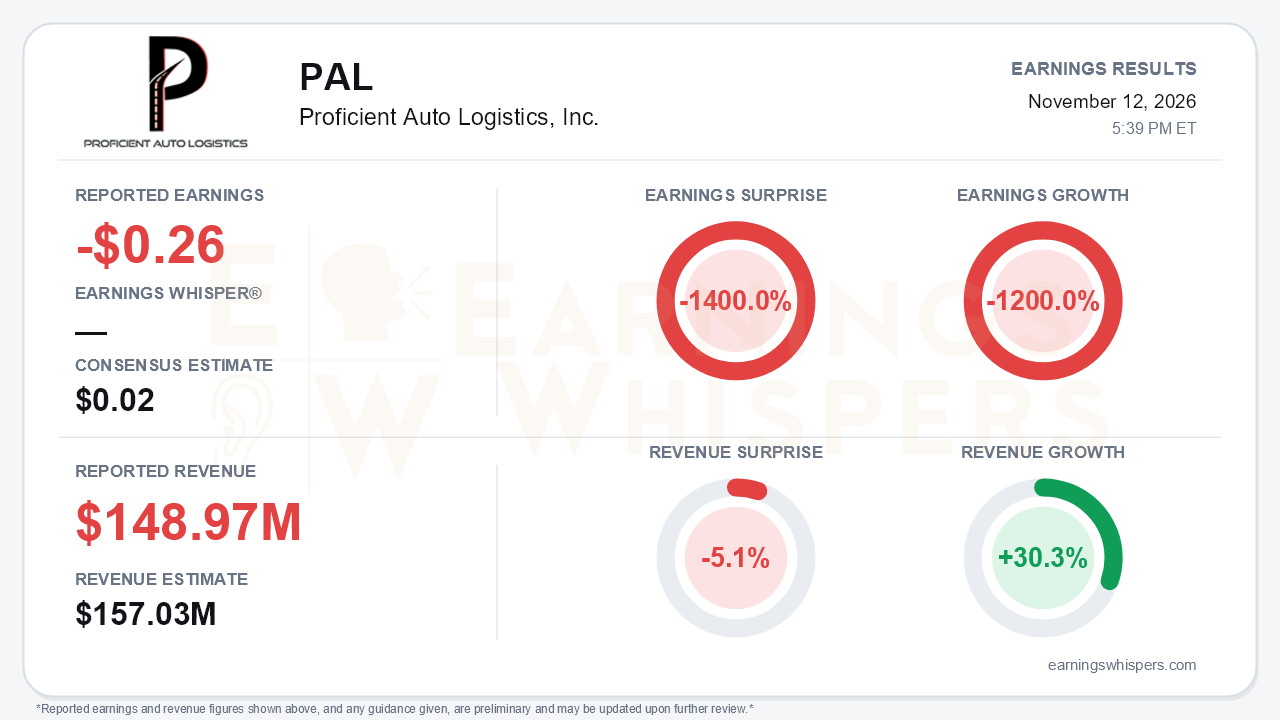
Proficient Auto Logistics delivered a quarter that fell well short of expectations. The company reported a loss of $0.26 per share against a consensus estimate for a $0.02 profit, a 1400.0% negative surprise. Earnings fell 1200.0% from a year ago. On a GAAP basis the loss was wider, at $0.35 per share, or $9.9 million, compared with $0.11 a year earlier. Revenue rose 30.3% to $148.97 million but missed the $157.03 million consensus by 5.1%. The growth is almost entirely acquired. Hansen & Adkins contributed only from August 13, while the legacy business is shrinking. Management answered with much larger synergy targets and multi-year margin goals. The central tension is that the near-term framework laid out just one quarter ago broke down, and investors are being asked to trust a recovery mostly scheduled for 2027 and 2028.
The quality of the quarter is poor beneath the top line. Adjusted operating income fell to $0.3 million from $4.2 million. The adjusted operating ratio deteriorated to 99.8% from 96.3%, meaning the core operation roughly broke even before amortization and stock compensation. Adjusted EBITDA dropped to $7.9 million, a 5.3% margin versus 10.5% a year ago. The company cited several pressures:
- **Cost inflation:** insurance, driver wages, recruiting and maintenance.
- **Fuel surcharge under-recovery:** OEM-administered programs did not keep pace with fuel costs, adding an estimated 200 to 250 basis points to the operating ratio.
- **Mix:** revenue per unit fell 10.3%, largely because the Hansen & Adkins business has a shorter length of haul.
Below the operating line, $6.4 million of acquisition costs and nearly doubled interest expense widened the pretax loss to $13.2 million.
The call made the miss look more structural than a single bad quarter. Legacy Proficient revenue fell 15.7% and units fell 14.3%. That legacy revenue came in around $98 million, against Q2 guidance for revenue roughly flat at $109 million with a better operating ratio. Driver attrition and subhauler exits now constrain volume, and management indicated capacity caps growth into 2027. Several prior commitments were effectively cut:
- **Revenue:** the Q4 guide of $180-195 million implies second-half revenue of roughly $329-344 million, below the $350-370 million framed in Q2.
- **Margins:** the Q3 EBITDA margin sits far below the 8-9% second-half target.
- **Fuel:** in Q1, management described fuel as roughly a $1 million timing lag. It now has no line of sight to normalization.
- **Tone:** management moved from calling Q2 an 'inflection point' to saying results 'clearly did not meet our expectations.' It labeled Q4 a transition quarter with only 50-100 basis points of sequential operating-ratio improvement.
The call did preserve a credible self-help story, however. Identified run-rate synergies rose to $20-30 million from the $6-10 million cited at the deal announcement. Management expects to reach the high end of the original range by year-end and enter 2027 at a $10 million run rate. The early operating evidence is tangible:
- **Sister hauling:** up to about 900 units per day, adding more than $0.5 million of monthly revenue.
- **Contract pricing:** about $25 million of contracts renewed since September 1 at weighted increases just over 10%, with mid-contract increases running at two to three times normal.
- **Spot mix:** spot and above-contract volume rose to 7-12% from under 5% in Q1.
- **Fuel terms:** six OEM customers adjusted fuel surcharge terms.
Management set operating-ratio targets of 95-97 for 2027 and 92-94 for 2028, and framed 2027 EBITDA at $60-70 million. Those are management aspirations, not results. Repricing the weakest 20% of contracts also carries explicit customer-loss risk.
The balance sheet raises the stakes. The release shows $140.6 million of senior secured debt and $11.8 million of cash, or about $128.8 million of net debt. That figure excludes $72.2 million of new convertible notes. Including those, net debt on the call was just over $200 million, and net leverage jumped to roughly 4x from 2.1x at Q2. The goal of getting below 3x by the end of Q3 2027 depends on that EBITDA ramp materializing.
The market had largely anticipated trouble. Shares opened at $5.72 after the August report and stood at $3.17 on the eve of this release, down 44.5%. They peaked at $6.06 on August 17 and slid to a 52-week low of $2.35 on October 29, though they had rebounded about 35% from that trough. The stock sits 47.7% below its $6.06 200-day moving average, and Earnings Whispers price and AVWAP trends remain negative. Investor sentiment, already negative, weakened modestly from -0.16 to -0.24.
The bottom line is that Proficient's quarter undercut management's credibility on near-term execution just as leverage climbed. Rising synergy targets, double-digit renewal pricing and explicit 2027-28 margin goals give bulls something concrete to track. Bears, however, have legitimate ammunition in a shrinking legacy business, capacity constraints and unresolved fuel recovery. Until operating-ratio improvement shows up in reported results rather than targets, the burden of proof rests with management.
Read our earnings preview for Proficient Auto Logistics, Inc.: https://www.earningswhispers.com/article/PAL/22939
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-30 | |
| Oct-05 | |
| Aug-14 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jun-01 | |
| May-11 | |
| May-07 |
