Talphera's Q3 Report Is Really About Finishing Enrollment Before The Cash Runs Thin
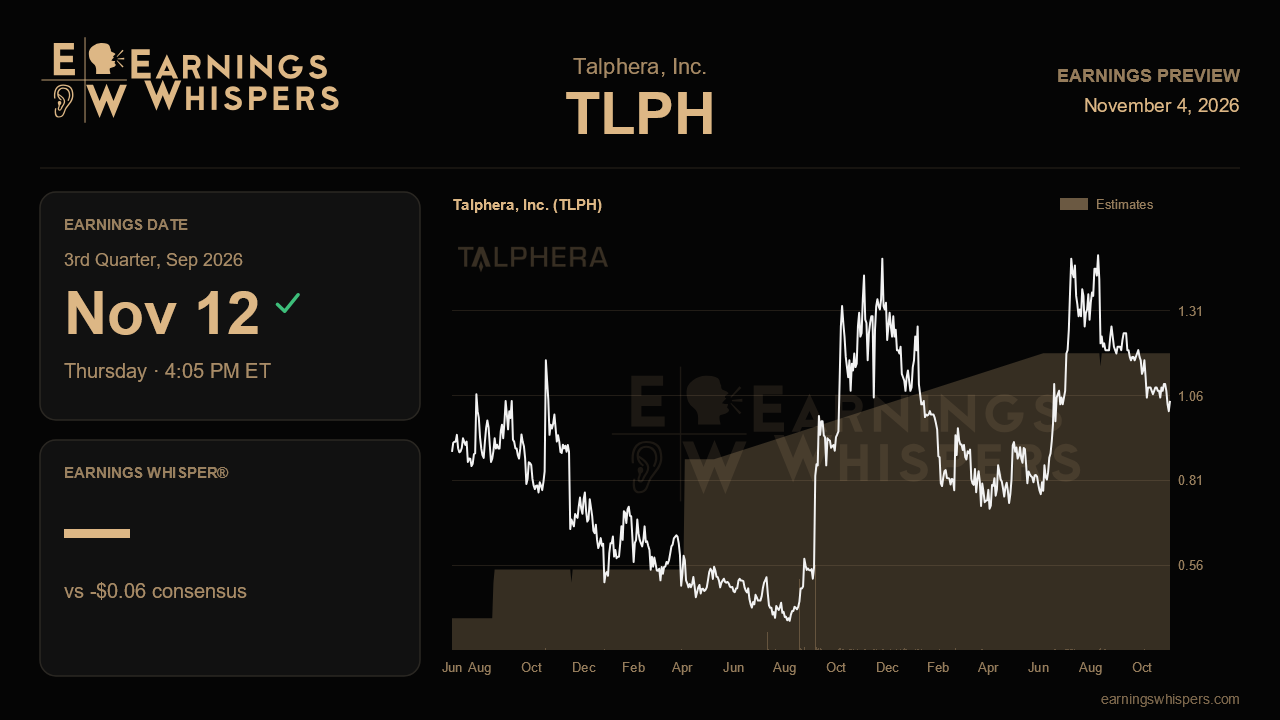
For a company with no product revenue, Talphera's quarterly loss is the least interesting number it will publish on November 12. What matters is whether the Nephro CRRT study of Niyad is finished, or nearly so, because that single milestone unlocks top-line data, roughly $16 million in conditional financing, and the path to a marketing application in the first half of 2027. Last quarter management described enrollment at 75% and promised completion later this year. This report is where that promise either holds or starts to slip.
The Street expects a loss of $0.06 per share, matching the prior quarter and narrowing from $0.11 a year ago. That works out to roughly 45% improvement on paper, though for a clinical-stage company the figure mostly reflects spending discipline and share count rather than any commercial traction. Management offers no financial guidance, so the real outlook is operational: enrollment done this year, top-line results about four to five weeks after the last patient finishes, and a PMA filing about three months later. A loss near consensus is unremarkable. A loss that widens sharply would matter only if it signals that spending is outrunning a shrinking cash cushion.
That cushion is the second test. Cash slipped from $21.3 million at the end of September 2025 to $17.1 million at the end of June, and cash operating expenses edged up to $3.9 million in the second quarter on NIAID development work and early market research. If third-quarter burn stayed near that pace, the balance would sit in the low teens, which keeps the conditional tranches central to the story. Those tranches only close around top-line data, so any delay in enrollment does double damage: it pushes out the clinical readout and postpones the money needed to reach approval. Investors should look for a firm statement that enrollment is complete or a specific window for the final patient, not another general reaffirmation.
The call also introduced catalysts that this report can advance. The draft 2026 KDIGO guideline cited the company's regional anticoagulant as acceptable for the first time, with public comment closing in May and final publication expected roughly three months later. Confirmation that the language survived into the final guideline would strengthen the launch case considerably. Management also raised its estimate of 2027 U.S. CRRT procedures to about 200,000 from roughly 165,000 and outlined a lean rollout targeting around 70 institutions that account for more than half of volume. Further detail on that plan, plus clarity on how the CoreMedix right of first negotiation, which runs for 60 days after data, might shape a partnered versus independent launch, would show the commercial thinking is maturing alongside the trial. Encouraging blinded titration observations and an unchanged DSMB recommendation were helpful last time; any change there would be a red flag.
The market has not rewarded the improving tone. Shares have fallen about 22% since the last report, roughly 20 points worse than the S&P 500, and at $1.04 the stock sits near the bottom of its $1.00 to $1.36 post-earnings range and barely above its 200-day average of $1.01. Sentiment remains bearish but has eased from uniformly negative a quarter ago, suggesting skeptics are less entrenched even as the price drifts lower. That combination leaves room for a relief move on clean milestone news and little support if timelines wobble.
The narrative from last quarter remains intact only if enrollment is finished or clearly within weeks of finishing, with cash burn contained enough to bridge to the data-linked financing. Hit that, and the stock's discount looks like an opportunity tied to a near-term binary readout. Miss it, and the familiar pattern of slipping timelines returns at precisely the moment the balance sheet can least afford it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Sep-03 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| May-14 | |
| May-13 | |
| May-13 | |
| May-07 | |
| Mar-25 | |
| Mar-23 | |
| Mar-23 | |
| Mar-18 |
