Talphera Narrows Loss And Beats Estimates, But NEPHRO Enrollment Stall Turns The Story Into An FDA Bet
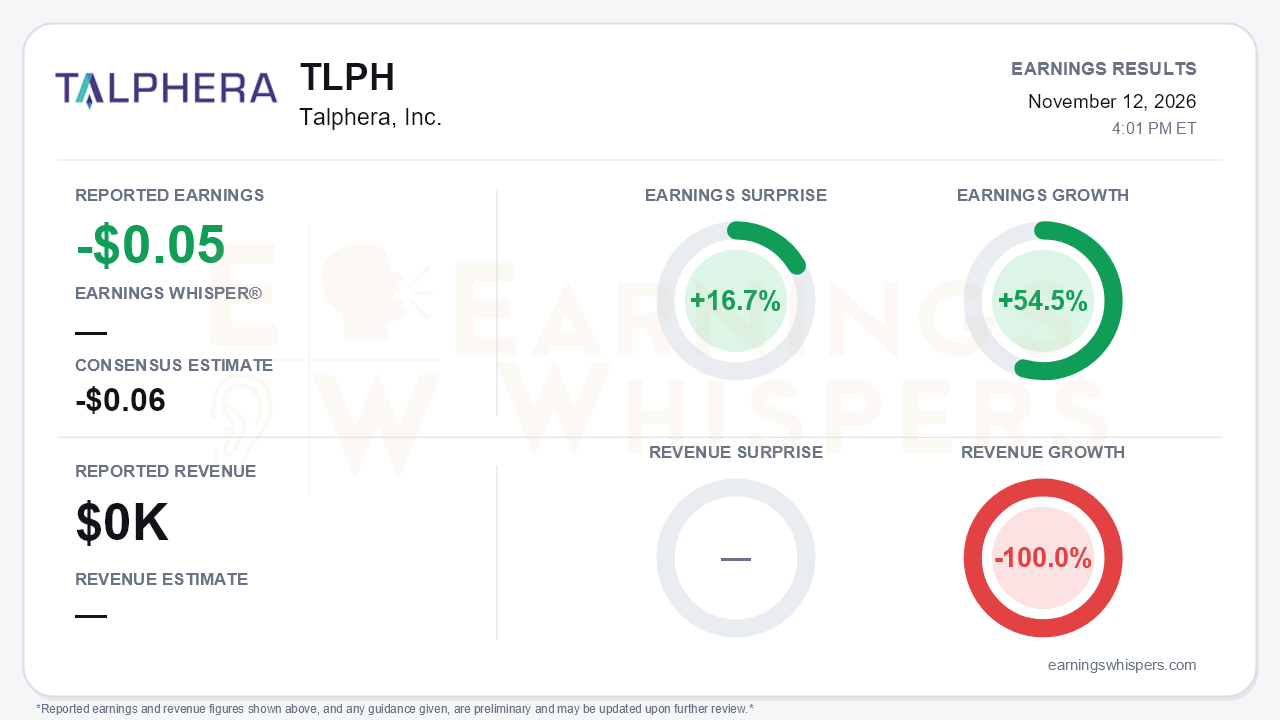
Talphera (NASDAQ: TLPH) reported a third-quarter loss of $0.05 per share, beating the consensus estimate of -$0.06 by 16.7%. That marks 54.5% earnings growth from the $0.11 loss a year earlier. Revenue was zero, a 100.0% decline from a negligible $1,000 in the prior-year quarter, which is irrelevant for a pre-commercial company. The beat is not the story. The quarter's defining development is that enrollment in the pivotal NEPHRO CRRT study has stalled. Talphera is now asking the FDA, through a Sprint meeting under the Breakthrough Devices program, to let it close enrollment on December 31 with fewer than the 70 patients it planned. A raised commercial forecast softened the news, but it does not replace a clean path to a PMA filing.
The quality of the EPS improvement deserves scrutiny. Net loss narrowed only modestly, to $4.0 million from $4.4 million. Most of the per-share gain came from a share count that rose to 75.5 million from 41.5 million. The other driver was a swing in warrant accounting: a $20,000 fair-value loss this quarter versus a $1.1 million loss a year ago. Operations moved the other way. The operating loss widened to $4.1 million from $3.4 million as R&D rose to $2.2 million and SG&A to $1.9 million. Excluding stock compensation, operating expenses were $3.8 million versus $3.3 million. Management attributed the increase to nafamostat (Niyad) development work and pre-launch commercial preparation. In other words, the per-share line improved through dilution and non-operating items while underlying spending climbed.
The call made clear how far the timeline has slipped:
- **Last March:** enrollment completion moved from the first half to the second half of 2026.
- **Q1:** the study was 50% enrolled.
- **Q2:** it was 75% enrolled, and management said it was "on track" to finish this year and file a PMA in the first half of 2027.
- **Now:** the study is only "over 75%" enrolled, implying little progress during the quarter.
Consented and enrolled patients over the past two to three months were down 85-90% from the same period in 2025, and management could not identify a clear cause. Statistical power at current enrollment is now described as above 80%, down from the over-90% the study was designed to deliver at 70 patients. If the FDA declines early closure, management's internal forecast pushes completion into the first quarter of 2027, which puts the first-half 2027 PMA at risk. The tone shifted from confident to defensive. Analysts pressed hard on the slowdown, and management leaned on precedent and power calculations in response.
The bull case has real support, and the call laid it out:
- **Regulatory precedent:** Fresenius won approval for its citrate system around October 19 on a 31-patient CRRT study that closed early.
- **Endpoint design:** NEPHRO's primary endpoint, post-filter activated clotting time, is an objective lab measure.
- **Market tailwinds:** draft KDIGO guidelines elevated nafamostat, and an NEJM study found higher mortality with intermittent hemodialysis than with CRRT, which could expand the addressable market.
- **Commercial forecasts:** the Q2 market research raised the 2027 U.S. CRRT procedure estimate to roughly 200,000 from 165,000, and the new peak U.S. sales estimate for nafamostat tops $200 million.
FDA feedback is expected by year-end, and an investor event is planned for the first quarter of 2027.
The balance sheet raises the stakes of that FDA answer. Cash and investments fell to $14.2 million from $17.1 million at the end of Q2 and $21.1 million at the end of Q1. The remaining roughly $16 million in financing tranches depends on completing the study. Talphera also plans a new S-3 shelf because the current one expires November 30. If the FDA approves the early close, the study completes and that funding likely opens up. If it does not, Talphera faces more burn, a delayed data readout, and a heightened risk of dilutive financing. The funding question and the regulatory question are effectively the same question.
Investor sentiment improved from an extreme -1.0 to -0.68 heading into the report. That is a meaningful thaw, but sentiment remains clearly negative. Price action has been harsher. At $1.05, shares were down 21.6% from the $1.34 open after the August report and about 23% below the inter-earnings high of $1.36 set that same day. They sat just 5% above the quarter's $1.00 low from November 6 and only 3.6% above the 200-day moving average of $1.01. The Earnings Whispers trend signals lean negative, with sequential growth and AVWAP readings weak. The market had evidently been discounting enrollment trouble before management quantified it.
The bottom line is that Talphera's EPS beat is a byproduct of dilution and warrant accounting, not operating progress. The investment case now rests almost entirely on whether the FDA accepts an underpowered-but-adequate NEPHRO dataset. Precedent, an objective endpoint, and a larger market estimate give management a credible argument. But a stalled study, repeated timeline slips, shrinking cash, and funding tied to study completion give bears legitimate ammunition until the FDA responds.
Read our earnings preview for Talphera, Inc.: https://www.earningswhispers.com/article/TLPH/22949
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Nov-04 | |
| Sep-03 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| May-14 | |
| May-13 | |
| May-13 | |
| May-07 | |
| Mar-25 |
