PACS Beats And Raises Again, But Florida-Scale M&A And A Wider GAAP Gap Complicate The Upgrade
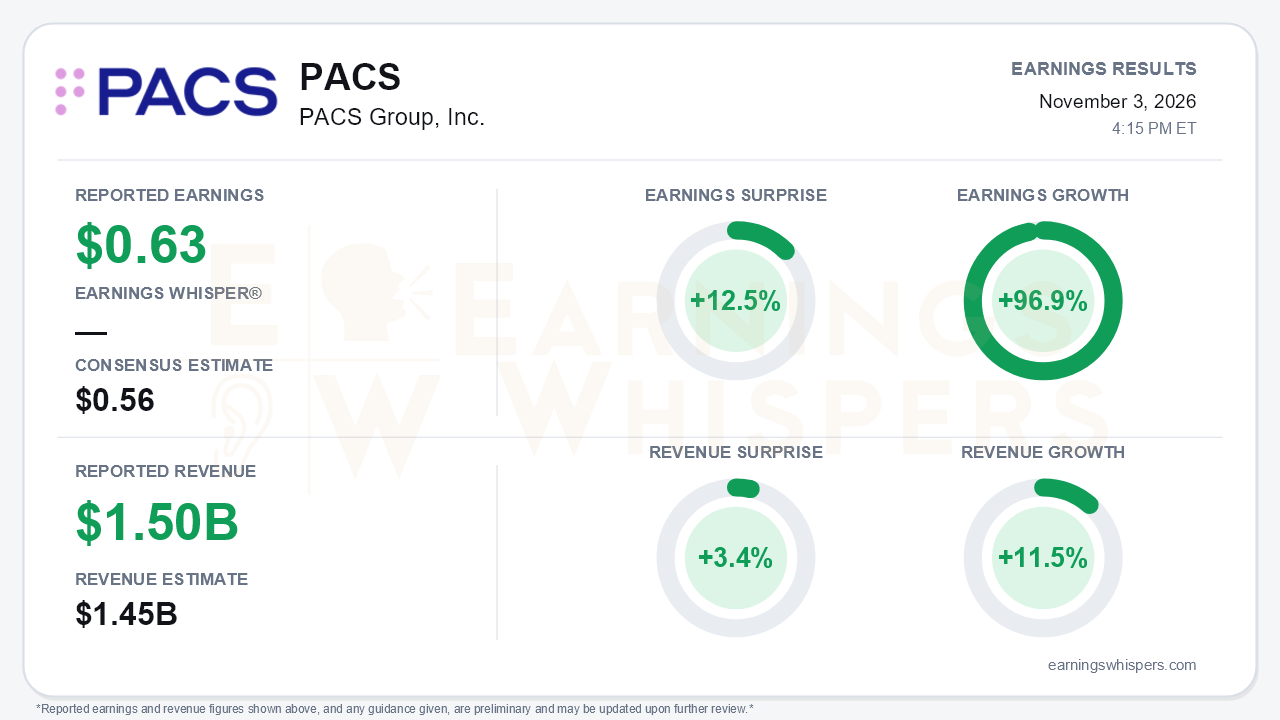
PACS Group delivered the kind of quarter that keeps a guidance-raise story going. Adjusted earnings of $0.63 per share beat the $0.56 consensus by 12.5%, and revenue of $1.499 billion topped the $1.45 billion estimate by 3.4%. Revenue growth accelerated to 11.5% from 9.1% in the second quarter. Earnings Whispers' normalized figures show earnings up 96.9% year over year. The company's own adjusted EPS comparison is a more modest 37% gain from $0.46, so investors will see different growth rates depending on the base used. Either way, the main takeaway is the third consecutive increase to full-year guidance. Adjusted EBITDA guidance now stands at $685 million to $695 million, compared with $555 million to $575 million at the start of the year. Revenue guidance rose $200 million to $5.95 billion to $6.05 billion. The central tension is that PACS is now changing the business faster than its mature operating base is improving.
The quality of the beat deserves some scrutiny. Adjusted EBITDA rose 33.6% to $175.7 million, and margin expanded to 11.7% from 9.8%. That is real operating leverage, and much of it came from cost of services growing more slowly than revenue. The GAAP picture is less striking. Diluted EPS was $0.37, up 15.6%, and net income rose 16.2% to $60.8 million. The gap between GAAP and adjusted results widened mainly because stock-based compensation jumped to $45.3 million from $12.5 million, pushing G&A to $138.4 million. The adjusted figures also exclude $9.5 million of legal and investigation-related costs. Those costs are falling but have not ended, and management offered no timeline for resolving the government investigations. California WQIP payments, which contributed $21 million year to date, have been discontinued and will not recur in 2027.
The call preserved a credible organic growth story beneath the acquisitions:
- **Same-store revenue:** growth accelerated to 6.4% from 5.8% in the second quarter.
- **Same-store occupancy:** 91.3%, up 200 basis points year over year, compared with a 150-basis-point gain last quarter.
- **Same-store skilled mix:** improved 120 basis points to 29.5%.
- **Labor:** agency labor costs continued to decline.
- **Cash conversion:** a two- to three-day improvement in DSO helped lift nine-month operating cash flow to $583.1 million.
The mature cohort, however, is softening. Occupancy slipped to 93.1% from 93.8% in the second quarter and 94.8% in the first, and skilled mix eased to 31.3%. Management attributed part of this to cohort reshuffling. Consolidated metrics are also being diluted by acquisitions. Reported skilled mix fell to 29.1% from 30.5% in the first quarter, and the share of facilities rated 4 or 5 stars dropped to 78.9% from 83.6%.
That dilution is the cost of an aggressive expansion. PACS closed 31 Aduro facilities during the quarter and entered Florida on October 1 with 32 skilled nursing operations totaling 4,049 beds. It added 11 Texas operations on November 1, and management described the acquisition pipeline as its largest ever. The financial strain is starting to show. Investing outflows reached $538 million over nine months, cash fell to $115.3 million, and net leverage edged up to 0.2x, which is still very conservative. The guidance also signals near-term costs. At the midpoint, it implies fourth-quarter adjusted EBITDA of roughly $177 million, essentially flat with the third quarter. That would come despite a sizable revenue step-up and a $5 million retroactive Ohio quality payment, because integration spending for Florida, Texas and Aduro is built into the outlook. Regulatory risk is also rising, including a Democratic-controlled Congress that could revisit minimum staffing rules.
Investor expectations shifted sharply. Earnings Whispers sentiment moved from roughly neutral before the prior report to strongly positive, a gain of about 0.97 that reached the very top of the scale. Price action has been more restrained. Shares at $46.68 are only 3.7% above the opening price after the August report, but they trade about 17% above the 200-day moving average of $39.78. Most of the Earnings Whispers trend signals are positive, with sequential growth, momentum and AVWAP all favorable, while the price trend is neutral. That leaves the stock with an enthusiastic audience but limited room for integration missteps.
The bottom line is that PACS beat estimates, accelerated growth and raised guidance for a third time, and same-store trends show its operating model is still working. Bears have legitimate ammunition, though:
- swelling stock compensation;
- non-recurring incentive payments;
- a slipping mature cohort;
- an implied flat fourth quarter as PACS absorbs its largest acquisition wave yet.
The next few quarters will test whether Florida and Aduro can follow the same ramp as earlier acquisitions.
Read our earnings preview for PACS Group, Inc.: https://www.earningswhispers.com/article/PACS/21985
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-27 | |
| Oct-05 | |
| Sep-30 | |
| Sep-25 | |
| Sep-21 | |
| Sep-14 | |
| Sep-02 | |
| Sep-01 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
