VIAVI Beats And Pulls Its $2 Billion Run-Rate Target Forward A Year, But Shares Enter The Report Down Nearly 38% From October's High
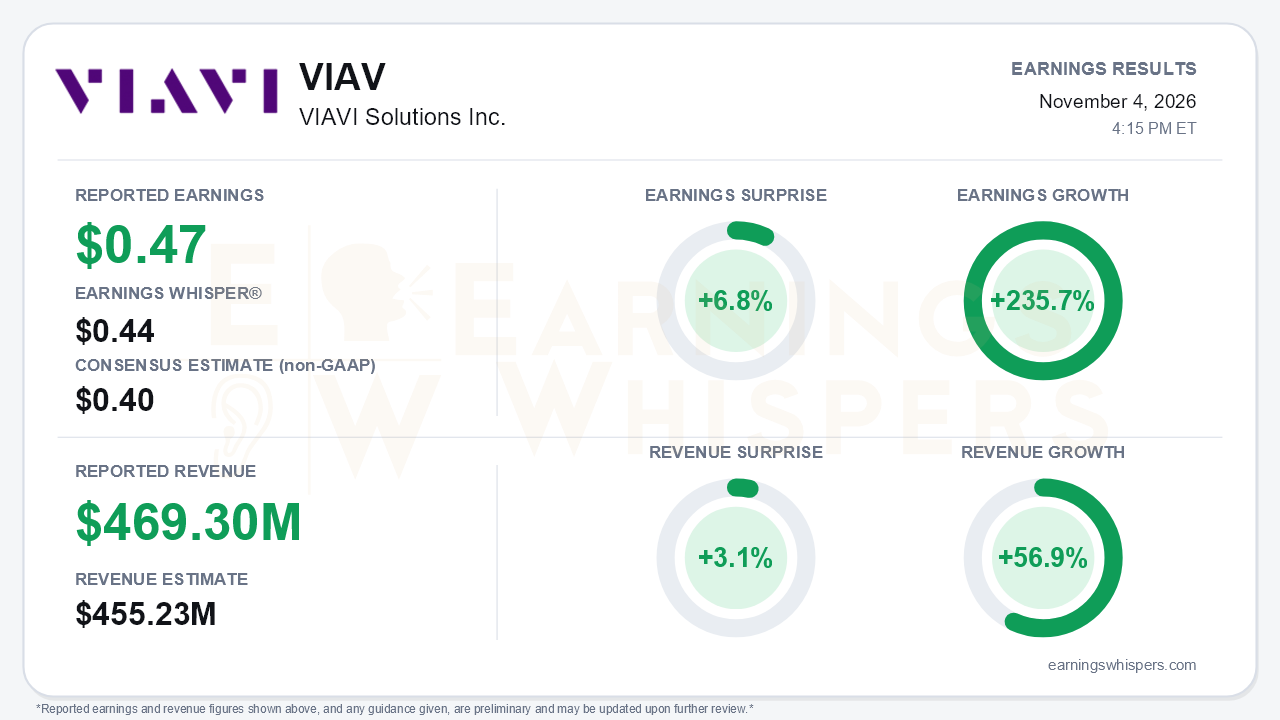
VIAVI Solutions delivered the kind of quarter that usually ends debates. Non-GAAP earnings of $0.47 per share topped the $0.40 consensus by 6.8% and cleared the $0.44 Earnings Whisper number. Revenue of $469.3 million beat the $455.23 million estimate by 3.1%. Earnings grew 235.7% year over year on 56.9% revenue growth, and results landed above the high end of management's own $450-460 million revenue and $0.40-0.42 EPS guidance. The more important development was the outlook. Management guided the December quarter to $505-515 million and $0.50-0.52, and said it now expects to reach a $500 million quarterly revenue run rate that quarter. That milestone was framed as 'calendar 2027' only last quarter and as an exit-fiscal-2028 target originally. The central tension is that the stock has been moving in the opposite direction of the fundamentals.
The earnings trajectory is genuinely accelerating rather than simply beating a low bar. Non-GAAP EPS has stepped up from $0.22 to $0.27 to $0.34 and now $0.47 over four quarters. Non-GAAP operating margin has climbed from 19.3% to 21.0% to 24.0% and now 29.0%. On a GAAP basis, VIAVI earned $0.29 per diluted share versus a $0.10 loss a year ago. The quality of the beat deserves some scrutiny, however. Roughly 110 basis points of the quarter's operating margin came from an approximately $11 million one-time tariff refund. Even without it, margin would have landed near the top of the 26.7%-27.5% guided range. GAAP results also included a $5.0 million insurance gain, which was excluded from non-GAAP figures. Cash generation was strong: operating cash flow rose to $104.7 million from $66.7 million in the June quarter.
The engine is Network and Service Enablement. Revenue there rose 74.1% year over year to $376.1 million, partly helped by the acquired Spirent business. Management put organic growth at roughly 50%, with data center revenue nearly doubling. Segment GAAP operating margin expanded to 25.5% from 8.2% a year earlier. Guidance calls for NSE revenue of $426-434 million, about 14% sequential growth, with a 28.1% operating margin. Management now frames incremental fall-through in the low-to-mid 50s percent, up from 40-45% as recently as the March quarter. It also expects sequential growth in every fiscal 2027 quarter, including the normally soft March period. That is an unusually assertive posture for a company whose release still cautions about limited visibility and heavy in-quarter book-and-ship business.
The call also widened the growth story beyond hyperscale test demand. VIAVI made its first production test shipments for co-packaged and near-packaged optics into the semiconductor packaging market. These were only about $1 million, but management sized the opportunity at more than $100 million within a couple of years. Other new drivers included:
- a U.S. Army Threat Systems Management Office selection of its T-Rex system for drone and counter-drone test ranges;
- early signs of a multi-year service provider refresh cycle;
- entry into fiber and multi-core connector manufacturing test;
- integrated Spirent/VIAVI launches planned for next year.
Bears still have ammunition, even if it is not in the core numbers. Optical Security and Performance Products is guided seasonally lower to $79-81 million, with operating margin falling to 35.7% from 43.2%. Wireless remains weak, and operating expenses step up in the March quarter. Capital allocation is also tilting aggressive. VIAVI repurchased $150 million of stock in the quarter and authorized a new $500 million program. Cash fell to $535.3 million from $656.7 million, while roughly $245 million of convertible notes now sit in short-term debt.
The market setup is more complicated than the surprise implies. Shares ran to an inter-earnings high of $48.42 on October 2. They then collapsed to a quarterly low of $27.79 on November 2, the day before the snapshot. At $30.05, the stock is down 20.9% from the open after the August report, 37.9% below that peak, and 22.4% below its $38.75 200-day moving average. Analysts on the call pointed to worries over AI and data center spending sustainability, credit conditions, and politics. Management dismissed any sign of a demand slowdown. Investor sentiment remained positive but weakened meaningfully, falling from 0.498 to 0.337 ahead of the report. Earnings Whispers trend readings reflect the same split: sequential growth and momentum remain positive, while price and AVWAP trends are negative.
The bottom line is that VIAVI's fundamentals improved on nearly every axis that matters. Earnings are accelerating, margins are expanding even after adjusting for the tariff refund, guidance moved up, and a major revenue milestone arrived a year early. The stock's sharp drawdown reflects macro skepticism about AI infrastructure spending rather than anything visible in this quarter. Whether that skepticism fades depends on VIAVI delivering the sequential growth it has now promised through the seasonally weak March quarter.
Read our earnings preview for VIAVI Solutions Inc.: https://www.earningswhispers.com/article/VIAV/21966
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-07 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Sep-24 | |
| Sep-09 |
