Navient's Record Originations Undercut By $211 Million Credit True-Up As Core EPS Collapses And Full-Year Guide Goes Unreaffirmed
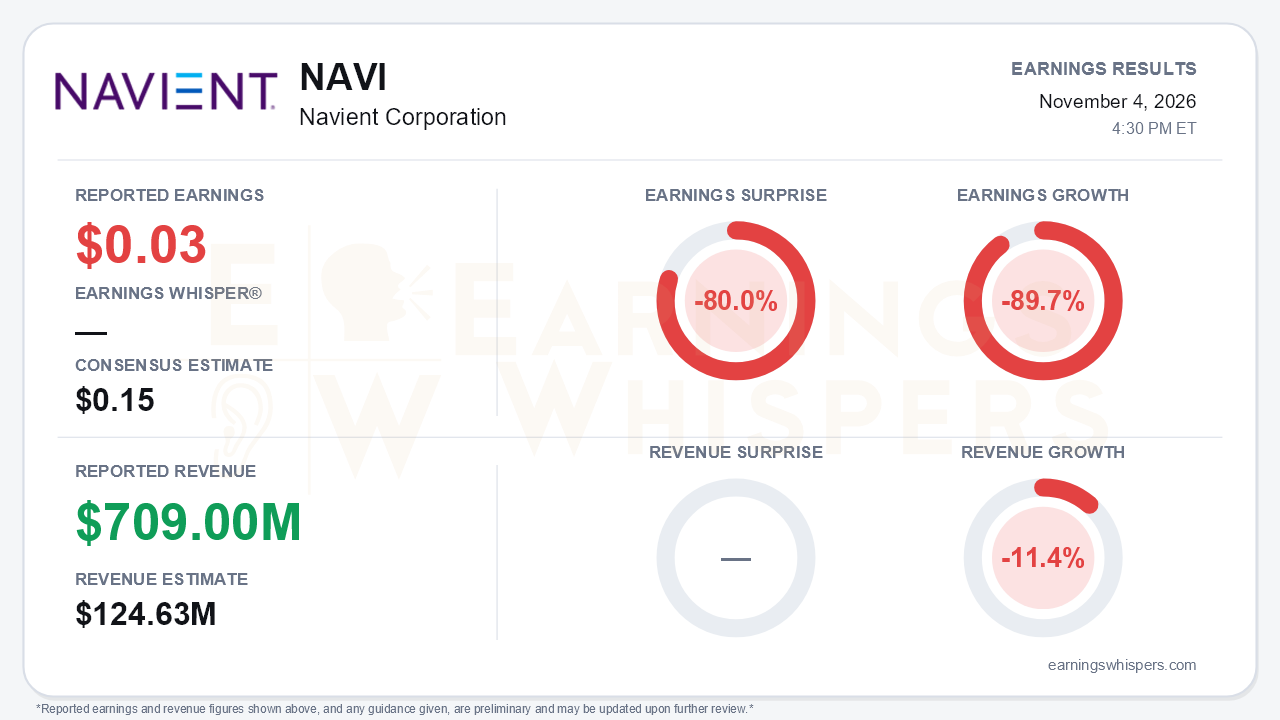
Navient delivered its strongest origination quarter in years and one of its weakest earnings prints. Core earnings came in at $0.03 per share, missing the $0.15 consensus by 80.0% and falling 89.7% from a year ago. That is a sharp reversal from $0.20 in the first quarter and $0.29 in the second. Revenue of $709.0 million fell 11.4% year over year.
The reported revenue figure beat the $124.63 million consensus by 468.9%. A gap that large suggests the estimate and the reported figure are measured on different bases, so the beat says little about operating strength. Net interest income actually declined sequentially. The central tension is that demand is clearly improving while the earnings power of the existing book is being marked down.
The quality of the quarter deserves scrutiny. The miss was driven almost entirely by a $227 million provision, up from $26 million in the second quarter and $18 million in the first. Of that total, $211 million related to previously originated private loans:
- **$178 million on legacy private loans.** Management acknowledged that credit improvement there is taking longer than forecast. The modest $23 million build in the second quarter had already hinted at this.
- **$33 million on pre-2025 refinance vintages.** This is a newer and arguably more troubling concern, because refi has been the growth engine.
GAAP EPS of $0.16 ran well ahead of core, helped by meaningful capital-markets activity. A roughly $750 million legacy private loan sale at an effective 103-104 price generated a $162 million gain. Another $1.4 billion of legacy loans and about $1 billion of in-school loans moved to held-for-sale. Navient also took its first fair-value mark on in-school loans, a $23 million gain at roughly 105% of par. Those gains show the assets have real market value, but they also shrink the interest-earning base, which is part of why net interest income fell.
The operating story beneath the provision is genuinely strong:
- **Total originations:** $1.4 billion, up from $815 million in the second quarter, with management citing nearly 80% growth.
- **In-school:** $479 million, up 84% year over year after +40% in the prior quarter.
- **Graduate lending:** up 170% as the elimination of Grad PLUS opens the market, with strength continuing into October.
- **Refi:** up 65% at a 775 average FICO.
- **Personal loans:** a new test produced $46 million, with more than 60% cross-sold from the refi base.
Management plans to turn in-school into a manufactured-for-sale product, citing private-credit demand, and to scale personal lending toward ratings and securitization. AAA refi securitization spreads are about 20% tighter than a year ago. The adjusted tangible equity ratio climbed to 9.5% from 9.0%. Private delinquencies and charge-offs improved, although management attributed the delinquency gains to mix.
Bears have legitimate ammunition, however:
- **Rates:** benchmark rates jumped roughly 120 basis points in September, outpacing coupon increases. That is compressing refi returns that had been above 20% and could dampen originations.
- **Origination outlook:** management now expects about $3.8 billion of full-year originations versus the $4 billion set in January.
- **EPS guidance:** with year-to-date core EPS around $0.52, the $0.65-$0.80 range was not reaffirmed and looks difficult to reach.
- **Other pressures:** FFELP 31+ delinquency rose to 15.5% from 14.7%, and federal segment net income slipped to $22 million from $26 million. Analysts also flagged bond-market concern following a corporate announcement about ten days before the call.
The market had been leaning cautious heading into the print. Investor sentiment improved notably over the quarter, from -0.23 to -0.03, but remained slightly negative. The shares told a less forgiving story. At $8.26, the stock is down 6.0% since opening after the August report and 7.3% below its 200-day moving average. It sits 18.6% below its September 16 high of $10.15 and just 3.2% above the October 28 low of $8.01. Shares surrendered nearly the entire rally from September into the report, suggesting credit and rate worries were partly anticipated. Shorter-term momentum and AVWAP readings have turned positive even as sequential growth trends remain negative.
The bottom line is that Navient's franchise-building is working. Record in-school and graduate volume, a new personal loan product and strong securitization execution all point to a real growth platform. But the quarter's earnings were swamped by a credit true-up on loans the company already owns. Rising rates are squeezing the refi economics that were supposed to fund that growth. Until the legacy and older refi books stop requiring reserve builds and guidance is reset credibly, the origination story will struggle to translate into the earnings investors were promised in January.
Read our earnings preview for Navient Corporation: https://www.earningswhispers.com/article/NAVI/21885
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-07 | |
| Sep-25 | |
| Sep-18 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Jul-17 | |
| Jul-02 | |
| May-21 |
