Silvaco Misses On Q3 Milestone Slippage, But Record Q4 Guide And Higher 2027 Outlook Shift The Story To Execution
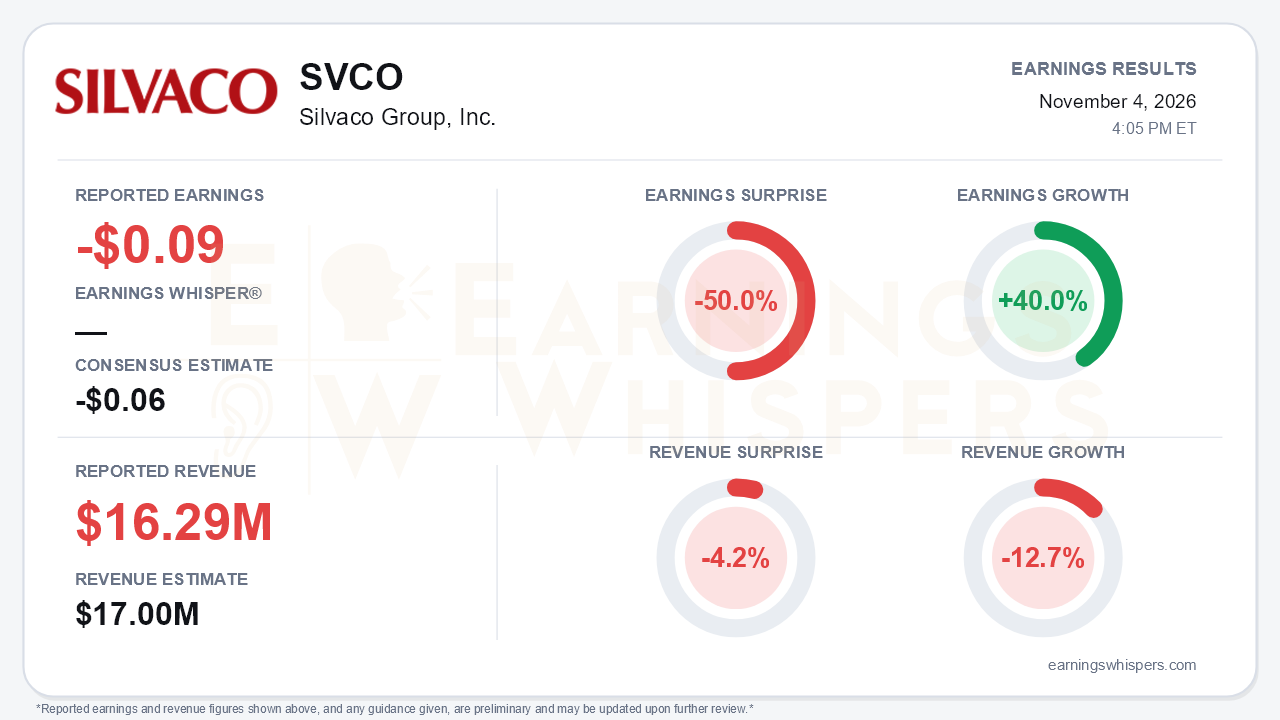
Silvaco missed on both lines in the third quarter. It reported a loss of $0.09 per share against the $0.06 consensus, a 50.0% shortfall, on revenue of $16.29 million, 4.2% below the $17.0 million consensus. Revenue fell 12.7% year over year, while earnings improved 40.0% because the loss narrowed. That normalized per-share figure sits between the company's GAAP loss of $0.14 (versus $0.18 a year ago) and its non-GAAP loss of $0.04 (versus $0.07). Either way, losses shrank but did not disappear. The quarter itself was not the story. Management used the call to argue that Q3 was a timing problem inside an accelerating business. It backed that argument with a record $22 million Q4 revenue guide and a higher 2027 outlook. That is the central tension: a soft print paired with the most aggressive forward framing the company has offered.
The quality of the quarter deserves scrutiny in both directions. Revenue slipped below the $17 million guidance midpoint because IP milestones pushed into Q4. Revenue also fell sequentially from $17.8 million in both Q1 and Q2. Non-GAAP gross margin eased to 85.3% from 86.8% in Q2 and well short of the roughly 88% guide. The company swung to a $1.0 million non-GAAP operating loss after posting a small profit in Q2. The year-over-year revenue decline also hides a sharp mix shift:
- TCAD revenue rose 16%.
- SIP revenue jumped 141%.
- EDA revenue fell 56% against a lumpy comparison, since EDA made up 56% of revenue a year ago.
On a GAAP basis, the cost restructuring is plainly working. GAAP gross margin rose 613 basis points to 84%. GAAP operating expenses fell about 25%, and the GAAP operating loss shrank to $4.3 million from $9.3 million.
The operating trends discussed on the call were stronger than the revenue line. Gross bookings of $19.3 million were down 15% year over year but beat the $18 million guide. They were the best of 2026, up from $16.2 million in Q2 and $17.2 million in Q1. A new tier-1 FTCO customer drove record Q3 TCAD bookings of $10.3 million, up 89%. Management described that customer as among the ten largest companies and said it could become as large as, or larger than, Micron. Jivaro Pro posted record bookings on four tier-1 wins, and management upgraded EDA from flat to improving. IP bookings rose 193%, and IP revenue is tracking toward about $20 million this year. Remaining performance obligations climbed to roughly $53 million.
The forward guidance is where the setup changed. Q4 calls for revenue of $22 million plus or minus 10%, up 35% sequentially. It also calls for bookings of $21 million and roughly 88% non-GAAP gross margin. That implies 17% revenue growth for 2026. Management lifted its 2027 framing from "double-digit, at least 10%" to mid-to-high teens, with operating expenses growing at one-third to one-half the pace of revenue. Bulls can point to Q4 revenue already booked at a multi-year high for this point in a quarter. Bears have legitimate ammunition, however:
- Q4 non-GAAP operating expenses step up to $16 million from $14.9 million on incentive, commission and milestone-related accruals.
- The year now hinges on one heavily back-end-loaded quarter, after Q3 showed how easily milestones can slip.
- Liquidity has relied on outside capital. Cash rose to $22 million partly because of the $10 million Micron convertible note and roughly $12 million in equity proceeds.
- The share count has climbed to 34.1 million from 30.9 million at year-end.
Operating cash burn, at least, improved dramatically to $0.8 million from $5.5 million in Q2 and $11 million in Q1.
The market was not positioned for optimism. Shares entered the report at $6.11, down 20.3% from the open after the August report and about 21% below the 200-day moving average of $7.73. The stock traded just 5.8% above its inter-earnings low of $5.77, set two days before the release, and 37% below its October 1 high of $9.72. Investor sentiment improved modestly, from slightly negative to roughly neutral. That is a thaw, not a vote of confidence. The Earnings Whispers trend readings lean negative, with price, AVWAP and sequential growth all weak, which matches a stock that gave back its entire autumn rally.
The bottom line is that Silvaco delivered a disappointing quarter and a materially better outlook. Bookings, customer wins and cash burn support management's claim of an inflection. Still, the thesis now rests on a $22 million fourth quarter that leaves little room for another milestone slip. With shares near their lows and sentiment only just turning neutral, the burden of proof sits squarely on Q4 execution.
Read our earnings preview for Silvaco Group, Inc.: https://www.earningswhispers.com/article/SVCO/21946
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Aug-18 | |
| Aug-06 | |
| Jul-27 | |
| Jul-26 | |
| Jul-23 | |
| May-19 | |
| May-07 | |
| May-06 | |
| May-04 | |
| Apr-23 |
