EPAM Beats, Signs Its First Big AI Deals And Launches A Buyback Push, But A Q4 Slowdown And Flat 2027 Margins Test The Rally
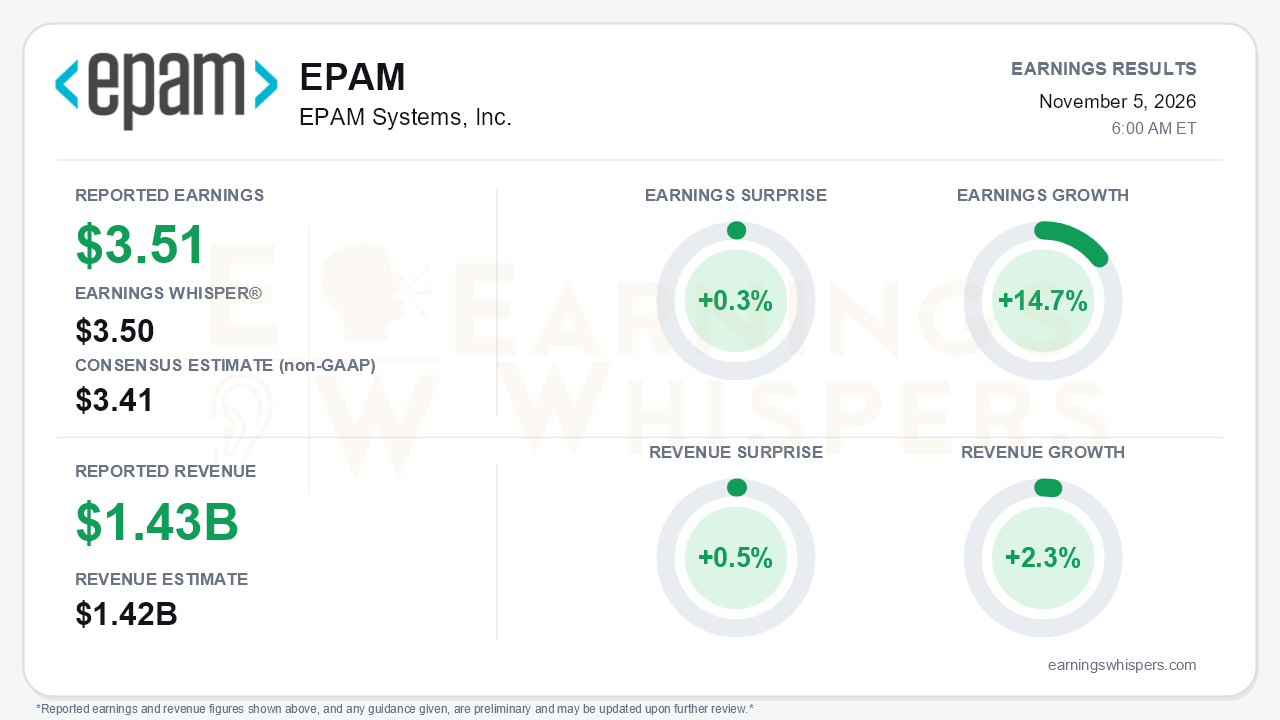
EPAM Systems delivered the quarter turnaround bulls wanted, but not the growth reacceleration that would fully justify the rally. Third-quarter non-GAAP EPS of $3.51 topped the $3.41 consensus and edged past the $3.50 Earnings Whisper number by 0.3%. Revenue of $1.426 billion beat the $1.42 billion consensus by 0.5%. Earnings grew 14.7% year over year, while revenue rose just 2.3%, and that gap is the central tension. EPAM is getting more profitable and returning more capital, but its top line keeps slowing, and fourth-quarter guidance points to near-zero growth.
The quality of the beat deserves scrutiny. Non-GAAP operating income rose 7.0% to $238.4 million, and operating margin widened to 16.7% from 16.0%. That is real operating progress, but it accounts for only about half of the EPS growth. The rest came from a shrinking share count. Diluted shares fell to roughly 51.5 million from 55.8 million a year ago after about $489 million of buybacks in the first nine months. GAAP EPS jumped 32.5% to $2.53, helped by the absence of last year's $11 million cost-optimization charge and a small foreign-exchange gain. Cash generation recovered sharply. Free cash flow was $274 million in the quarter after a negative $18 million in Q2, and DSO improved to 78 days from 82. Even so, nine-month operating cash flow of $250.1 million still trails last year's $372.0 million.
The call changed the narrative more than the numbers did. After two consecutive guidance cuts and a contrite Q2 tone, management shifted to talking about accelerating momentum, and it had evidence to point to:
- **Large deals:** The large AI-led deals that slipped in Q1 and Q2 finally closed. EPAM signed three multi-year contracts in financial services and energy, each valued at high tens of millions to more than $100 million in total contract value, ramping in the first half of 2027.
- **AI-native revenue:** It reached about $185 million, or 13% of revenue, up from more than $160 million in Q2. The full-year target was lifted to at least $650 million from $600 million.
- **Verticals:** Financial services accelerated to 13.7% growth, and life sciences and healthcare reached 9.9%.
- **Hiring:** Delivery headcount grew by 700 sequentially after a flat first half, with faster hiring planned for Q4.
Bears still have legitimate ammunition. Organic constant-currency growth is guided to just 0.5% to 1.6% in Q4, down from 2.5% in Q3, and reported growth could be slightly negative. Non-AI revenue is shrinking about 6% year over year, so AI gains are largely backfilling erosion in the legacy business rather than driving net expansion. Weakness is spreading across regions and verticals:
- Americas growth was essentially flat at 0.2%.
- EMEA slowed to 5.8% from 10.9% in Q2.
- Software and high-tech fell 6.1%, and business information and media fell 5.5%.
- Consumer goods, retail and travel turned negative at -2.5% on inflation and fuel-price pressure.
Utilization also slipped to 76.5% from 78.3%. Looking ahead, management framed 2027 non-GAAP operating margin at 15% to 16%, implying no expansion. Gross margin is expected to be flat to modestly lower as the Poland R&D benefit roughly halves and variable compensation normalizes. The CEO explicitly ruled out double-digit growth next year.
Capital return is now a core part of the story. The board added $1.5 billion of authorization, bringing the total to $1.8 billion through 2029. EPAM plans a $500 million accelerated repurchase next week, funded with cash and credit-facility borrowings. It also committed to return at least 50% of free cash flow annually from 2027 through 2029. That supports per-share earnings even if revenue growth stays muted, which is why full-year non-GAAP EPS guidance rose to $13.23-$13.31 even as the top end of reported revenue growth was trimmed for currency. It also draws down a cash balance that has already fallen to $970 million from $1.3 billion at year-end.
The market setup is more complicated than the modest surprise implies. Shares have climbed 57.3% since opening at $87.35 after the August report. The stock entered earnings at $137.36, about 13% above its 200-day moving average and only 5.8% below the inter-earnings high set days earlier. Investor sentiment improved substantially, from -0.47 to -0.05, but remains slightly negative. Investors have largely priced in the turn without fully embracing it. Most Earnings Whispers trend readings are positive, though momentum has turned negative, consistent with a rally that has run hard into the print.
The bottom line is that EPAM gave turnaround skeptics something they were not positioned for: signed large AI deals, a higher AI-native target, raised margin and EPS guidance, and an aggressive capital-return framework. However, the underlying growth engine is still decelerating into Q4. The shrinking non-AI book and stalled 2027 margins mean buybacks and AI mix shift must carry the story. With the stock already near its highs, the next leg depends on those new deals ramping visibly in early 2027.
Read our earnings preview for EPAM Systems, Inc.: https://www.earningswhispers.com/article/EPAM/22090
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 6 hours | |
| 6 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-05 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-24 | |
| Aug-25 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 |
