Planet Fitness Raises Its Outlook But Misses The Whisper As Buybacks, Not Membership Growth, Lift EPS
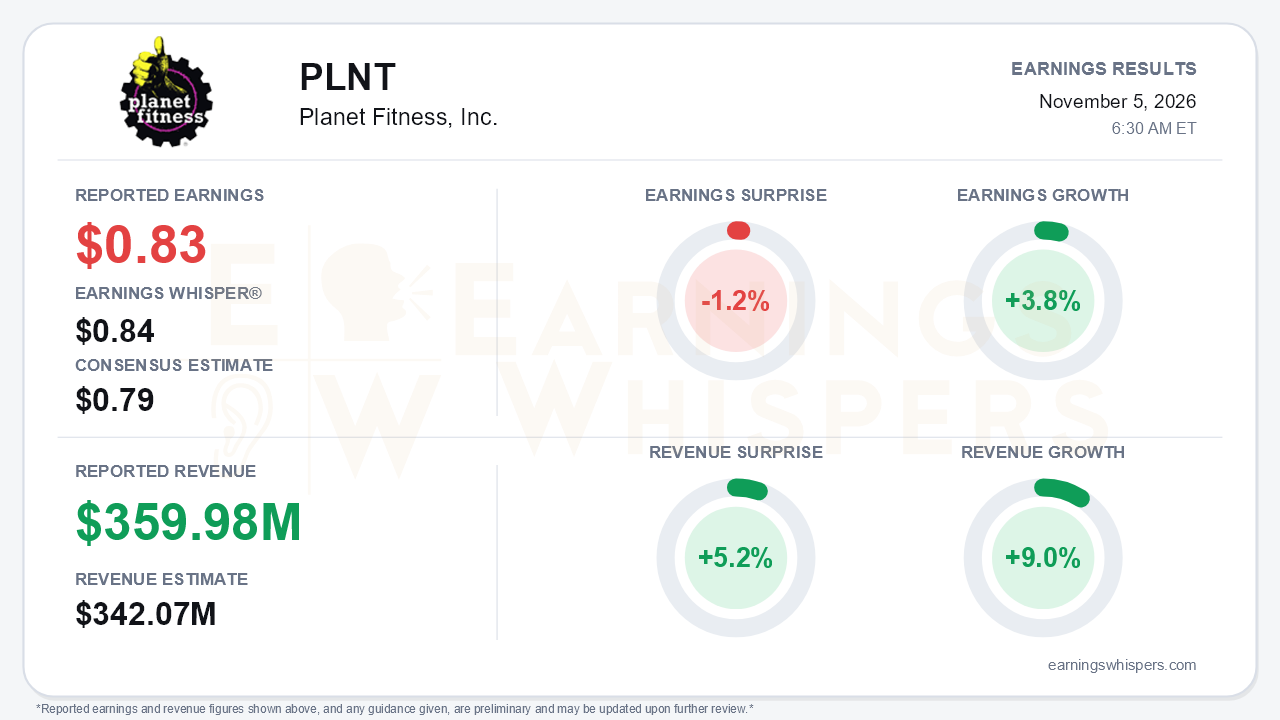
Planet Fitness delivered its first guidance raise of the year in the third quarter, but the earnings beat behind it is thinner than the headline suggests. Adjusted earnings of $0.83 per share topped the $0.79 consensus but fell 1.2% short of the $0.84 Earnings Whisper number. Revenue of $359.98 million beat consensus by 5.2% and grew 9.0% from a year earlier. Adjusted EPS grew 3.8%, slower than the year-to-date pace: nine-month adjusted EPS was $2.45 versus $2.25 a year ago, which implies the second half is decelerating. That is the central tension. The company raised its full-year targets for same club sales, revenue and adjusted EBITDA, yet membership was flat, comps are still slowing, and per-share growth now depends heavily on share count reduction.
The quality of the beat deserves scrutiny. Adjusted net income fell $5.1 million to $61.9 million. Adjusted EPS rose only because diluted adjusted shares dropped to about 75.0 million from 84.0 million, a result of $650 million in buybacks over the trailing twelve months. GAAP diluted EPS was flat at $0.70. GAAP net income fell to $52.2 million as interest expense climbed to $34.1 million from $26.3 million. The revenue beat also needs context. Roughly $10.4 million of the $29.6 million increase came from raising the National Advertising Fund contribution rate from 2% to 3%. That revenue is pass-through, with matching expense, so it inflates the top line while diluting margins. Adjusted EBITDA rose a more modest 3.9% to $146.2 million, and the adjusted EBITDA margin slipped to about 40.6% from 42.6%. Corporate-club segment EBITDA was essentially flat. Equipment revenue grew 11.1% on replacement sales, but new-club equipment sales fell, with 21 placements versus 27 a year ago.
The call made clear that the underlying engine is still sputtering. System-wide same club sales rose 1.5%. That beat a prior outlook that had only assumed comps would stay positive, but it continued a slide from 3.5% in the first quarter and 1.7% in the second. The comp remains entirely rate-driven, supported by Black Card penetration rising 160 basis points to roughly 68%. Membership held at about 21.5 million, unchanged from the second quarter. The raised full-year comp range of 1.5% to 2% implies a fourth-quarter comp near flat. The $10 Classic promotion lifted joins but did not prove net accretive system-wide. Churn did hold steady at 3.6%, and management's tone was noticeably more confident than its defensive first-quarter posture.
The forward story now rests on capital deployment and pricing rather than organic acceleration. Management outlined several levers:
- the Be-Fit acquisition in Portugal, about €102.5 million for 25 profitable clubs, expected to be accretive in 2027, with plans to double the Iberian footprint over three to five years;
- a strategic review of refranchising the roughly 280 domestic corporate clubs;
- a new $500 million buyback authorization;
- regional Black Card price increases planned for the second quarter of 2027;
- a refreshed brand campaign and a lower-cost club prototype.
Bears have legitimate ammunition, however. The higher openings target of 190 to 195 exists only because of the Portugal clubs. Underlying domestic openings were cut by roughly 10 to 15 because of tight real estate, and 2027 is guided to a similar level. Equipment placements were lowered to 135 to 140 from 150 to 160. Net leverage stands at 3.6x, cash fell to $515 million, adjusted net income is still guided down about 3%, and the NAF rate reverts to 2% in 2027. Even after the raise, full-year targets remain well below the original plan of a 4% to 5% comp and roughly 10% EBITDA growth.
The market setup is more complicated than the revenue surprise implies. Investor sentiment, already negative, deteriorated further from -0.31 to -0.42 heading into the report. Price action moved the other way. Shares rebounded about 44% from a September 24 low of $39.90 and entered the report near the top of the inter-earnings range, about 1% below a high of $57.97 set the day before. The stock is up 3.3% since the prior report's open but still sits roughly 7% below its 200-day moving average of $61.56. A rally into a narrow miss against the whisper leaves little cushion, even as the AVWAP trend reading has turned positive.
The bottom line is that Planet Fitness bought itself credibility with a guidance raise and new capital-return levers, but not evidence of renewed growth. Revenue strength was partly mechanical, EPS growth leaned on buybacks, and membership, comps and domestic development are all flat to slowing. Until the 2027 pricing actions and marketing reboot translate into member growth, this remains a financial-engineering story wrapped around a stalled core.
Read our earnings preview for Planet Fitness, Inc.: https://www.earningswhispers.com/article/PLNT/22167
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-12 | |
| Oct-09 | |
| Sep-25 | |
| Sep-23 | |
| Sep-23 | |
| Sep-14 | |
| Sep-14 |
