Ur-Energy's Halved Stock Puts Its Production Ramp And Cash Burn On Trial
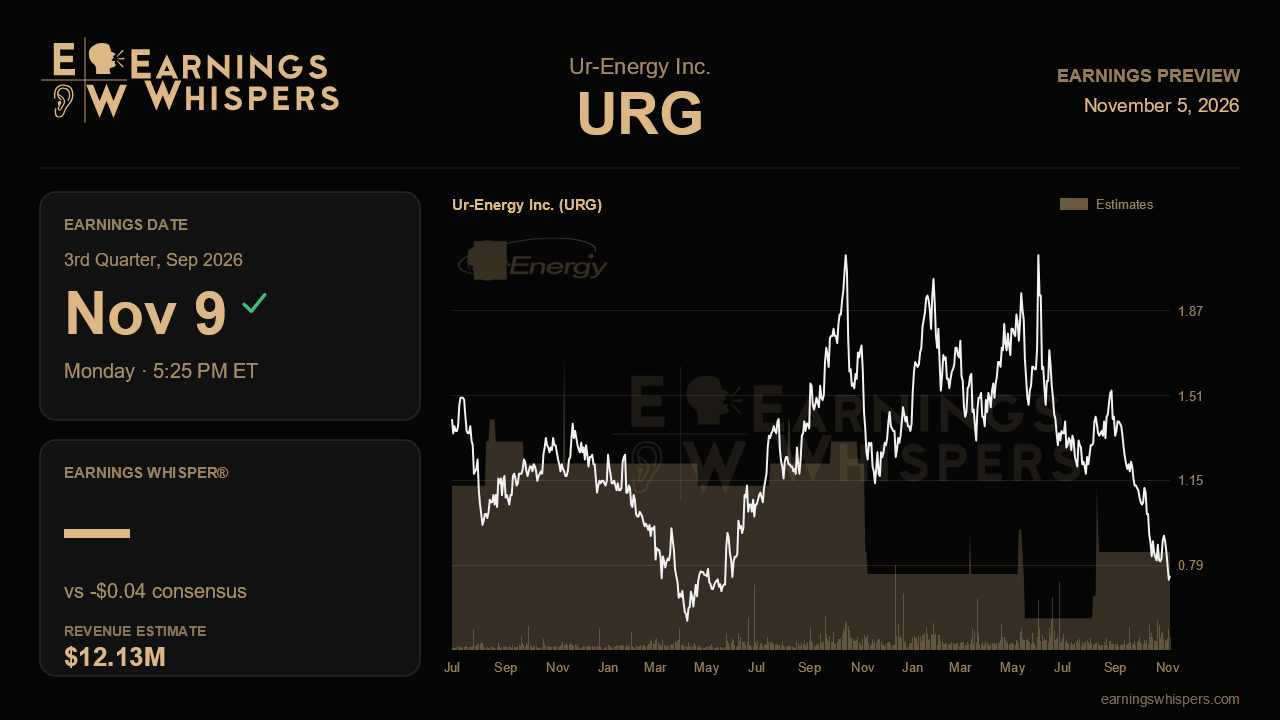
Ur-Energy enters its third-quarter report with a striking disconnect. Last quarter, management described a company finally hitting its operational stride, with record drumming at Lost Creek, Shirley Basin running as a full commercial operation and a new sand filter lifting plant flow rates by roughly 30%. The market has responded by cutting the stock nearly in half. The November 9 release, due after the close, is the first real chance to show whether the operating momentum is durable or whether the stock is correctly pricing a ramp that keeps slipping.
The Street is looking for a loss of $0.04 per share on revenue of about $12.1 million. That revenue figure would nearly double the $6.3 million booked a year ago, and the loss would narrow from $0.07. Sequentially, though, consensus implies a step back from the $14.4 million generated last quarter on 215,000 contracted pounds. At similar realized pricing, that suggests fewer pounds delivered in the quarter. That is not necessarily alarming for a company that sells against a contract schedule, but it puts more weight on the production and cost data than on the headline sales number.
The most important context is management's decision last quarter to defer 300,000 pounds of 2026 deliveries into 2027 and 2029, trimming contracted volumes from the 1.3 million pounds it had reiterated on two prior calls to about 1.0 million. Management framed the move as reducing ramp-up risk, which reads as prudent, but it also lowered the bar the company has to clear. This report should show whether production is now comfortably ahead of that reduced commitment. Drummed output of 141,000 pounds in the second quarter was the best since the ramp began in 2022. A further increase, helped by full-quarter benefit from the July sand filter commissioning and resin arriving from Shirley Basin, would validate the claim that the binding constraint has shifted from fines to simply drilling more wells. A flat or lower figure would raise uncomfortable questions about whether the deferral was a one-time cushion or an early warning.
Costs are the second test. Cash cost was $40.20 per pound last quarter, and management leans heavily on a model in which roughly 80% of costs are fixed, so rising volume should push unit costs down toward a long-term target in the $20 to $25 range. Any movement below Q1's $37.50 would be tangible evidence of operating leverage. Shirley Basin deserves scrutiny as well, since its recovery curves are still early and high flow rates bring hydrology challenges.
Then there is the balance sheet, which may explain much of the stock's slide. Unrestricted cash fell to $95.3 million from $123 million in a single quarter, with development spending running at $12 million to $15 million per quarter. Finished inventory at the conversion facility also dropped to about 348,000 pounds. That matters because a 250,000-pound uranium loan to Aringen comes due in the fourth quarter and must be repaid in physical pounds on top of contracted deliveries. Investors will want evidence that inventory is being rebuilt and that cash burn is moderating, not accelerating.
Sentiment has soured noticeably, flipping from mildly bullish before the last report to clearly bearish now, and the shares at $0.75 sit barely above their post-earnings low of $0.72 and far beneath the 200-day average near $1.43. That pessimism lowers the hurdle for a relief move, though it guarantees nothing. Updates on the Lost Creek South drilling program and the Lost Soldier technical report due by year-end offer longer-term upside, but they will not carry the quarter. The central question is simple: can Ur-Energy show rising pounds, falling unit costs and a stabilizing cash and inventory position at the same time? If it can, the delivery cut looks like conservatism. If not, the market's verdict will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Aug-24 | |
| Aug-20 | |
| Aug-11 | |
| Aug-10 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-14 | |
| Jul-09 | |
| Jun-29 |
