Ur-Energy Matches On EPS, But Purchased Pounds And Delivery Deferrals Expose A Stalled Production Ramp
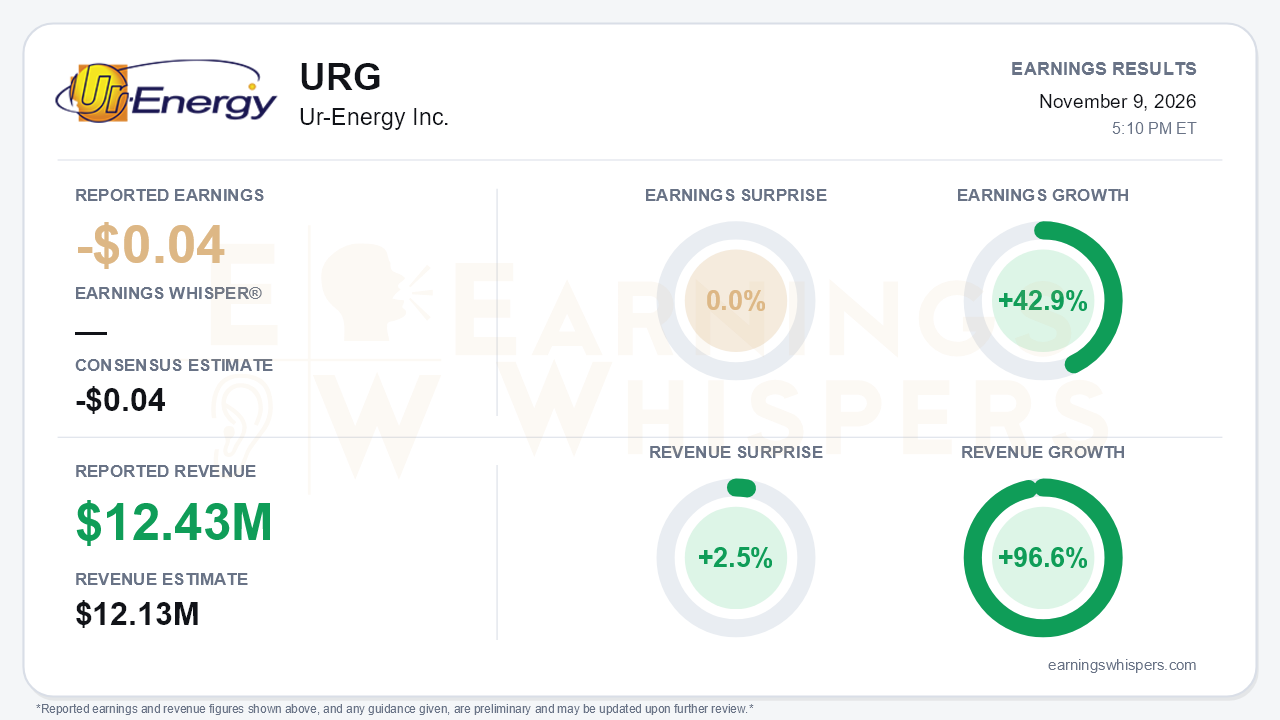
Ur-Energy (NYSE American: URG) reported a third-quarter loss of $0.04 per share, exactly in line with consensus. Revenue of $12.43 million beat the $12.13 million estimate by 2.5% and grew 96.6% year over year. Earnings improved 42.9% from a year ago, so the loss narrowed meaningfully. On the surface, that looks like a company growing into its production base. Underneath, the quarter tells a different story. Ur-Energy met its contracts largely by selling uranium it bought rather than uranium it mined, while its flagship operation lost ground sequentially. That is the central tension. The year-over-year comparisons flatter a ramp that stalled in the third quarter.
The quality of the quarter deserves scrutiny. Ur-Energy sold 190,000 pounds of U3O8 for $12.3 million in product sales, at an average price of $64.95 per pound. Revenue was down from $14.4 million on 215,000 pounds in the second quarter. Only 10,000 of those pounds were produced. The other 180,000 came from purchased inventory carried at about $70.87 per pound, above the realized price. As a result, non-produced sales lost $1.0 million, and total U3O8 product profit swung to a $969,000 loss. The total product margin was -7.9%, compared with +14.3% in Q2 and +31.2% in Q1. Production costs were not the problem. Cash cost per produced pound sold was essentially flat at $40.40 versus $40.20. Non-cash costs per pound, however, climbed to $15.10 from $12.76.
The operating data explain why so few produced pounds were sold. Pounds captured rose 47% sequentially to 154,667, an encouraging upstream signal. Pounds drummed at Lost Creek, though, fell 25.8% to 104,586. Management attributed the drop to ion exchange and elution maintenance and to lower grades from late-life header houses. On the call, management indicated grades should stay at these lower levels until the move into Mine Unit 5. Production there is targeted for the first quarter of 2027, pending regulatory approval. Captured pounds piled up as in-process and plant inventory, which jumped from 19,496 to 85,708 pounds. Finished inventory at the conversion facility fell to 233,378 pounds, down from 348,292 in Q2 and roughly 417,000 in Q1. Shirley Basin made its first shipments in August, and management described them as routine. Still, the mine captured just 14,697 pounds in the quarter and 25,330 year to date, and only 9,379 pounds were shipped to Lost Creek.
The forward picture hinges on balance-sheet and delivery management as much as geology. During the quarter, Ur-Energy deferred 150,000 pounds of deliveries to 2027 and 150,000 to 2029. It also extended its 250,000-pound inventory loan to November 2027. In October, it pushed another 300,000 pounds from the fourth quarter into 2029. The company still expects to sell 700,000 pounds in 2026 at about $67 per pound, or roughly $46.9 million. With 460,000 pounds sold through September, that implies about 240,000 pounds in Q4. The bigger test is 2027, when the call cited about 1.4 million pounds of deliveries against a thin finished inventory. Spending is also front-loaded. The company plans $26 million for the Lost Creek wastewater facility, which is not expected to operate until Q2 2027, plus $8 million at Shirley Basin. Management did not update cash, which had fallen from $123 million in Q1 to $95.3 million in Q2. It sidestepped Q4 production questions, noting that ramp-up is not always a straight line. Analysts framed an EBITDA inflection as a late-2027 or 2028 event.
There is a credible growth narrative alongside those risks. Management said term uranium prices sit about $10 above spot and that utilities are prioritizing security of supply. Ur-Energy is pursuing premium-to-spot contract structures. The Lost Soldier technical report remains on track for year-end, with a construction decision expected in 2027. A 120-hole program is underway at Lost Creek South, and follow-up drilling at North Hadsell is planned. Management also cited positive post-quarter results from the plant maintenance and from lixiviant optimization at Shirley Basin. These are real catalysts, but they are largely 2027 and later events.
Investors had already begun pricing in the execution gap. Earnings Whispers sentiment fell from a slightly positive 0.04 to -0.20, a meaningful deterioration. Shares stood at $0.81, down 43.9% from the $1.44 open after the August report and about 43% below the 200-day moving average of $1.42. Price and AVWAP trend readings remain negative, with only momentum registering positive. Bears have legitimate ammunition here: purchased-pound losses, shrinking inventory, repeated deferrals and an undisclosed cash balance.
The bottom line is that Ur-Energy's in-line loss and near-doubling of revenue mask a quarter in which Lost Creek output slipped, Shirley Basin ramped slowly, and contract obligations were met with money-losing purchased pounds and pushed-out deliveries. Improving captured pounds, Mine Unit 5 timing and a firm term-price environment keep the story alive. The investment case now rests on whether drummed production recovers before inventory and cash run thin, and the burden of proof sits squarely with execution in the next two quarters.
Read our earnings preview for Ur-Energy Inc.: https://www.earningswhispers.com/article/URG/22953
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Aug-24 | |
| Aug-20 | |
| Aug-11 | |
| Aug-10 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-14 |
