Pixelworks Must Show Its New Device Licensing Deal Can Lift Tiny, Lumpy Revenue
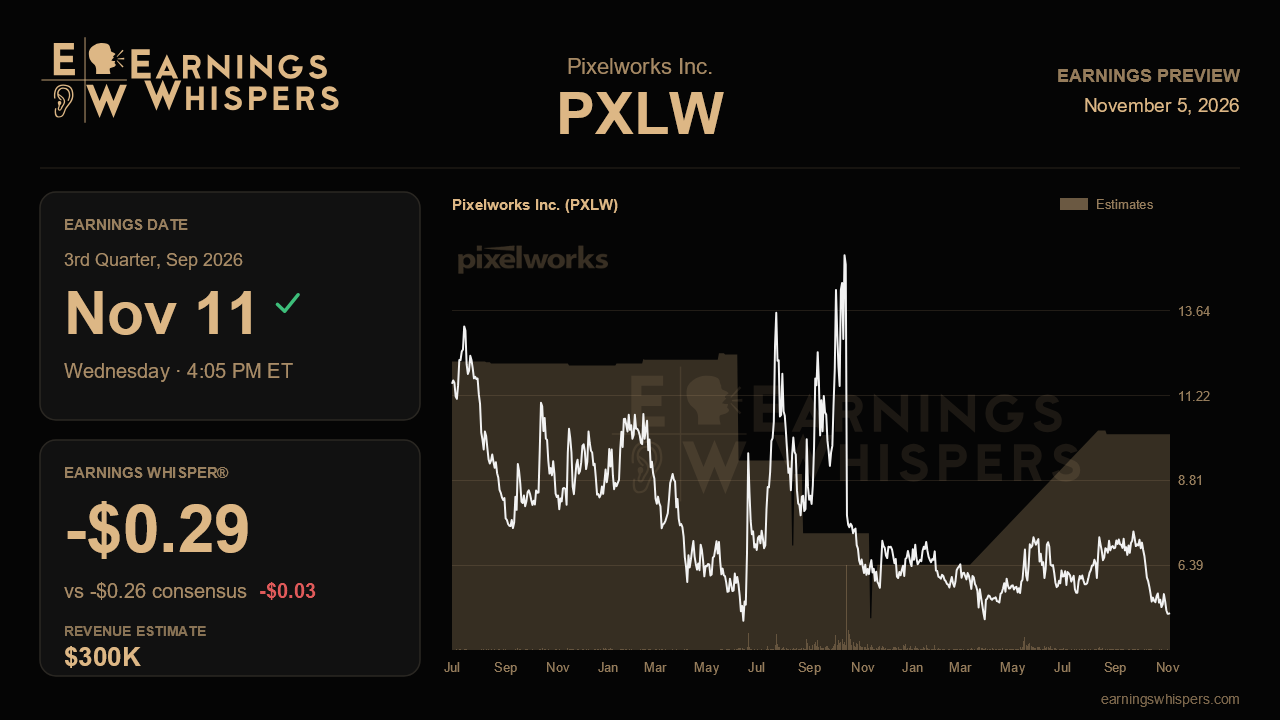
Pixelworks heads into its third-quarter report with a better story than it had three months ago, and a stock price that refuses to believe it. Last quarter management unveiled its first major device certification agreement, signed ahead of its own 2026 timeline, and sounded more confident than at any point since the company remade itself as a pure-play licensing business. Shares have nonetheless fallen 16.6% since that report, trailing the S&P 500 by more than 15 percentage points. When the company reports after the close on November 11, the question is simple: is the licensing model starting to produce revenue, or just press releases?
The Street is not asking for much. Consensus calls for a loss of $0.26 per share on revenue of roughly $300,000, a 96.6% drop from the $8.8 million booked in the year-ago quarter. That comparison is mostly an artifact of the company's transformation and says little about current momentum. The more relevant benchmark is the roughly $64,000 reported last quarter. Management pointed to sequential revenue growth in the third quarter based on business already booked, so the consensus figure implies something close to a fivefold jump. Even so, $300,000 would still trail the approximately $450,000 posted in the first quarter, a reminder of how lumpy this revenue stream remains. The whisper number sits at a loss of $0.29, a few cents worse than consensus, suggesting the informal bar is set slightly lower rather than higher. The loss should narrow meaningfully from last quarter's $0.43 and the year-ago $0.79, reflecting completed restructuring more than any surge in sales.
The device agreement is the catalyst that matters most. The unnamed global manufacturer spent about six months evaluating TrueCut before committing to certify a family of devices, and management described the resulting certification fees as royalty-like. Validation this quarter would look like concrete detail: a timeline for when certified products ship, any early fee recognition, or signs that the partner is willing to be identified. Because monetization depends on the partner's later-2026 product plans, silence or vague language would not break the thesis, but it would push the payoff further out for a company whose revenue is still measured in thousands of dollars. On the cinema side, the additions of Kinepolis and CineD expanded the roster of premium exhibition partners to about six. Evidence that those relationships are generating more TrueCut releases, rather than simply endorsements, would support the argument that the ecosystem is compounding.
Cost discipline and cash deserve equal attention. Cash slid to about $53 million from roughly $58 million, driven by $3.2 million in buybacks and $1.7 million of operating burn, and management nudged its quarterly cash operating expense framework up to below $2.5 million from about $2 million. Holding spending inside that ceiling while gross margin stays near last quarter's 60.9% would show the lean model works. Any further creep in expenses, with revenue still negligible, would draw sharper scrutiny of runway, especially with only $1.8 million left on the repurchase authorization.
Sentiment has thawed from uniformly bearish heading into the last report to modestly negative now, yet the stock tells a gloomier story. At $5.02, shares sit below their 200-day moving average of $6.16, beneath the prior quarter's low of $5.52, and just above the post-earnings low of $4.91. That positioning leaves little cushion if the report disappoints, but it also means a credible revenue step-up could catch skeptics off guard.
Ultimately, this report hinges on whether the sequential growth management promised actually arrives and whether the device licensing deal gains enough definition to look like a revenue engine rather than a promise. Deliver both, and the improving narrative holds. Miss on either, and the market's doubts will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-28 | |
| Oct-15 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-23 | |
| Sep-22 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 | |
| Sep-03 | |
| Aug-28 |
