Lincoln International Beats On A Record Quarter, But A Pulled-Forward Deal Tempers The Fourth-Quarter Setup
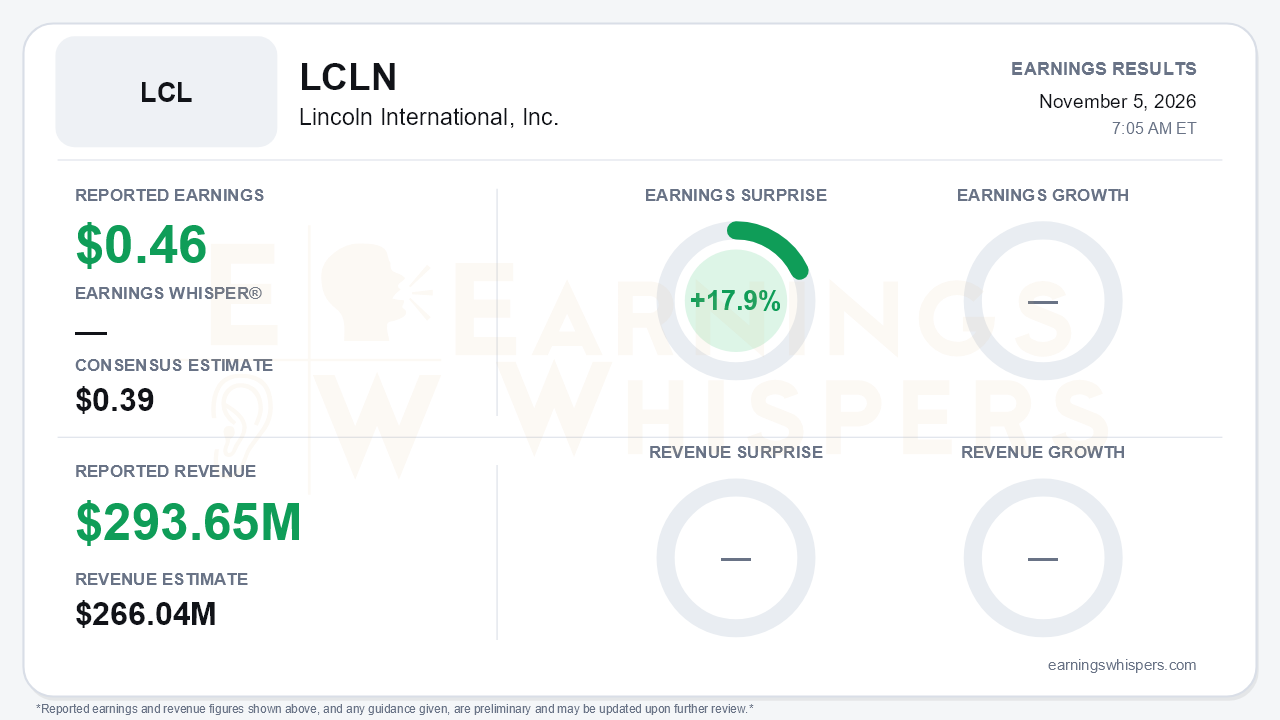
Lincoln International delivered the kind of quarter a newly public advisory firm needs. Adjusted earnings came in at $0.46 per share, beating the $0.39 consensus by 17.9%, and revenue of $293.65 million topped the $266.04 million estimate by 10.4%. Revenue rose 57% year over year, faster than the 45% year-to-date pace, so growth clearly accelerated into the third quarter. Adjusted net income jumped 150% to $50.2 million, compared with 76% growth for the first nine months. The central tension is timing. Management said a large deal expected in the fourth quarter closed in the third instead, so part of the beat came from next quarter's revenue. That makes the quarter strong but somewhat flattered.
The quality of the beat deserves scrutiny on two other fronts. First, GAAP and adjusted results diverge sharply. GAAP diluted EPS was $0.25, and GAAP operating income fell to $44.3 million from $51.3 million. The adjusted figures add back $27.6 million of costs, including $16.8 million of acquisition-related costs and intangible amortization, $4.8 million of IPO equity awards, and $3.2 million of deferred retention and earnout expense. Adjusted EPS also assumes a full exchange into roughly 110 million shares and a 31% tax rate. Second, growth was helped by the October 2025 MarshBerry acquisition, and the release does not separate organic from acquired revenue. Even so, the operating improvement is real. The adjusted compensation ratio fell to 61.0% from 68.5%, the adjusted non-compensation ratio dropped to 14.6% from 18.0%, and adjusted operating margin nearly doubled to 24.5% from 13.5%.
The call preserved a credible growth story beyond the timing benefit. Investment Banking Advisory revenue rose 70% to $239.9 million on 93 closed deals, and Lincoln posted its second consecutive record transaction fee. Average fees rose even excluding that record fee. Valuations and Opinions grew 18% to a record $53.8 million on 25% more portfolio valuations. Companies valued quarterly rose to about 7,600 from roughly 7,400 cited last quarter. Management's tone shifted noticeably: it described an "ice dam melting." In the second quarter it had said nothing was imminent in the M&A pipeline; now it says a handful of potentially impactful deals are "bubbling to the top." It also said sponsor activity is broadening to B and C assets and that the number of double-digit-million fees in the backlog is at record highs. Management credited share gains as well, noting newer managing directors account for more than half the backlog.
Guidance was reaffirmed, not raised. The roughly 61% comp ratio and high-single-digit pro forma non-comp growth targets were held steady, and fourth-quarter IB revenue is now expected at the low end of the 30-40% of annual revenue range. Bears have legitimate ammunition beyond the pull-forward:
- Section 162(m) is expected to push the 2027 tax rate above the current 31%.
- Lateral hiring is slowing as competition intensifies.
- About 20% of 2024-26 MD hires have underperformed or departed.
- Europe lags the U.S.
- 2026's above-trend growth, concentrated in industrials and services, sets up tough 2027 comparisons.
On the other side, management expects outsized 2027 growth in capital and private funds advisory and frames mid-teens advisory growth as sustainable. It also announced its largest-ever internal MD promotion class plus committed lateral starts in early 2027. The balance sheet supports that investment. Net cash stands at $261.2 million after long-term debt fell to $101.9 million from $270.4 million, though a new $85.2 million tax receivable agreement liability is part of the post-IPO structure.
The market setup is more complicated than the surprise implies. Shares rose 20.9% from the open after the prior report to $27.25. They entered the release just 3.1% below a 52-week high of $28.12 set on November 4 and 13.9% above the 200-day moving average. Yet investor sentiment moved the other way, falling from -0.15 to -0.38, a meaningful deterioration that leaves sentiment clearly negative. That gap suggests investors were skeptical of a stock that had already rallied into the print. A softer fourth-quarter framework gives those skeptics something to point to, even as the AVWAP trend remains positive.
The bottom line is that Lincoln posted a genuinely strong quarter: accelerating revenue, sharply wider adjusted margins, record fees, and a pipeline management describes as the best it has seen. But part of the beat was borrowed from the fourth quarter, and adjusted earnings sit well above GAAP. With the shares near their highs and sentiment souring, the next test is whether the backlog can fill the fourth-quarter gap and carry growth into tougher 2027 comparisons.
Read our earnings preview for Lincoln International, Inc.: https://www.earningswhispers.com/article/LCLN/22130
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Aug-13 | |
| Aug-06 | |
| Jul-17 | |
| Jul-16 | |
| Jun-04 |
The Anything-Goes Era in Private-Credit Lending Is Coming to an End
LCLN LCLN -5.98%
The Wall Street Journal
|
| May-21 | |
| May-20 | |
| May-20 |
